














Manufacturing activity across Australia lost momentum in September, pulling the industrial sector into contraction territory after recent expansion. According to preliminary survey findings published on Wednesday by S&P Global, Australia's Manufacturing Purchasing Managers Index retreated to 49.3 in September from the 52.0 registered in the previous month. Because the 50.0 threshold separates economic expansion from contraction, the drop below this boundary highlights renewed headwinds for goods producers, even as service-oriented sectors continued to record modest overall gains.
Services and Composite Gauges Signal Slower Expansion
The broader private sector also experienced a noticeable cooling trend during the same period. The S&P Global Services PMI for Australia moderated to 51.4 in September, down from the earlier level of 53.2. While service providers managed to remain on the expansionary side of the neutral mark, the pace of activity noticeably slackened. Reflecting the combined trends of factory output and services operations, the Composite PMI fell to 50.8 in September compared to 52.7 previously, highlighting an economy expanding at a much narrower margin.
Foreign Exchange Dynamics and the Australian Dollar
The preliminary release of Australia's PMI figures for August had exerted little to no tangible impact on the Australian Dollar. In currency trading, the AUD/USD pair held negative territory near 0.7115 before extending Monday's downward pressure. The exchange rate briefly breached below the vital 0.7100 contention area to touch three-day lows. Persistent strength in the US Dollar kept the Aussie under sustained pressure, while market participants positioned themselves ahead of the upcoming Trump-Xi summit scheduled for Thursday.
Central Bank Monetary Levers and Interest Rate Trajectories
Monetary policy settings established by the Reserve Bank of Australia represent one of the primary drivers steering the Australian Dollar. The RBA exerts influence over the currency by fixing the interbank cash rate, which sets the foundation for lending conditions across the wider financial system. The central bank's core objective centers on maintaining consumer price inflation within a 2% to 3% target corridor through interest rate adjustments. When Australian interest rates stand comparatively higher than those of other major central banks, the currency tends to receive upward support, whereas comparatively lower yields work in the reverse direction. In addition, the central bank can implement quantitative easing, which exerts negative pressure on the currency, or quantitative tightening, which generally provides positive momentum.
Commodity Export Valuations and the National Trade Balance
As an economy endowed with extensive mineral wealth, Australia's currency trajectory remains closely aligned with commodity markets, particularly iron ore. Iron ore stands as the nation's premier export commodity, generating $118 billion annually based on 2021 records, with Chinese industrial buyers serving as the dominant destination. Because export revenues flow back into the national financial framework, an increase in iron ore prices typically buoys the Australian Dollar by driving aggregate currency demand. Conversely, downturns in iron ore market values reduce foreign currency inflows and undermine exchange rate strength.
These commodity movements directly feed into the national trade balance, measuring the spread between export revenues received and payments sent abroad for imports. When Australia produces heavily demanded natural resources and merchandise, the resulting trade surplus bolsters the domestic currency as overseas buyers must acquire Australian funds to settle transactions. A net positive trade balance reinforces the Australian Dollar, whereas an unfavorable balance yields the opposite outcome.
Chinese Macroeconomic Demand and Shifting Risk Sentiment
Given that China functions as Australia's most prominent trading partner, the macroeconomic health of the Chinese market exerts a substantial sway over Australian Dollar valuations. When commercial conditions in China accelerate, demand expands for Australian raw materials, merchandise, and services, driving foreign exchange demand for the Australian currency and elevating its market worth. Conversely, when economic growth in China falls short of expectations, Australian export volumes encounter headwinds. As a consequence, unexpected deviations in Chinese economic performance regularly ripple across Australian Dollar exchange pairings.
Broader investor sentiment also acts as an influential swing factor. In environments characterized by risk-on sentiment, market participants actively allocate capital toward higher-yielding and cyclical assets, a trend that generally benefits the Australian Dollar. Conversely, periods of risk aversion prompt capital to seek safe-haven instruments, leaving growth-sensitive currencies vulnerable. Domestic inflation trends and broader gross domestic product expansion rates within Australia further shape how the currency navigates these shifting global currents.
Global Central Bank Actions and Parallel Market Movements
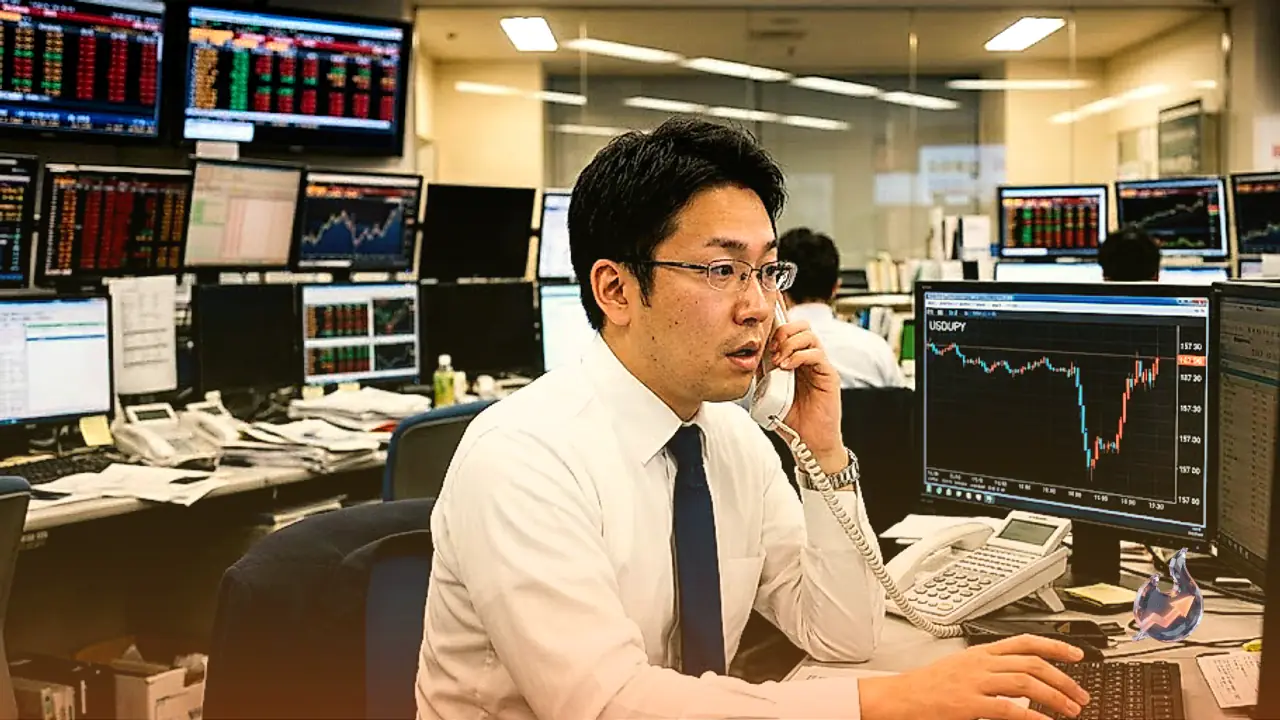
Cross-currency crosscurrents also captured trader attention across the Asia-Pacific region. The Bank of Japan lifted its short-term interest rate target from 1.00% to 1.25% in a 7-2 vote, marking a further stride in its monetary policy normalization path in line with widespread market expectations. While the rate hike brought borrowing benchmarks to a 31-year high, the dovish character of the policy adjustment kept Japanese Yen buyers on the defensive, though concerns over potential official intervention helped cap downside volatility. The USD/JPY pair hovered near 157.50 during Tuesday's Asian trading session, notching modest gains.
Concurrently, the US Dollar maintained a supportive underpinning due to hawkish expectations surrounding the Federal Reserve and elevated geopolitical friction across the Middle East. Meanwhile, gold displayed renewed strength on Tuesday, trading higher and approaching the key $4,400 per troy ounce threshold. The precious metal advanced despite a rebound in US Dollar buying, mixed yields across US Treasury securities, and ongoing geopolitical crosscurrents in global markets.