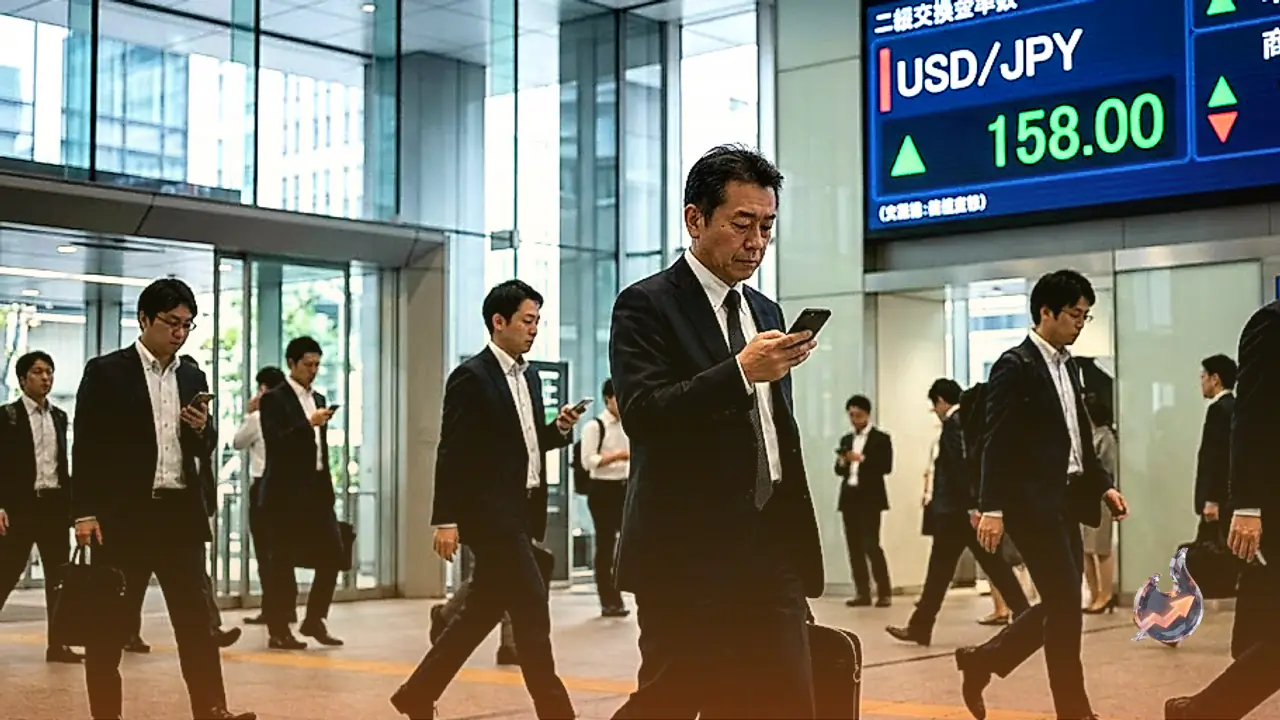















Currency markets witnessed sharp volatility as the Japanese Yen reversed an initial rebound against the US Dollar, with the exchange rate round-tripping a decline toward the 157.50 threshold before stabilizing near its familiar range. The whipsaw movement reflects elevated trader anxiety ahead of key central bank communication and impending domestic economic figures. Investors continue to scrutinize every development to assess whether monetary authorities will maintain their tightening trajectory or adopt a wait-and-see stance amid mixed macroeconomic indicators.
Governor Ueda's Key Address and October Rate Hike Expectations
Bank of Japan Governor Ueda is scheduled to deliver a major address on Tuesday at 06:35 GMT, marking his first significant public appearance since the central bank lifted its policy benchmark to 1.25% on September 18. This speech serves as the immediate crucible for market pricing surrounding the upcoming October 30 policy decision. Financial derivatives and interest rate traders currently assign roughly a one-in-four probability to a follow-up rate increase next month. Over the past three consecutive trading sessions, the USD/JPY pair has oscillated across the 158.00 mark in both directions, currently hovering just beneath this psychological milestone.
The central bank previously initiated rate hikes in June and followed up with another adjustment in September. Market participants have interpreted this three-month interlude as the institution's intended policy cadence. In remarks following the September adjustment, Governor Ueda signaled a clear evolution in central banking priorities, explaining that policymakers have transitioned from striving to pull inflation up toward the 2% target to actively preventing it from overshooting sustainably. Preempting an inflation overshoot before it takes root would logically necessitate an interest rate increase in October rather than delaying action until the December gathering.
Upcoming Japanese Wage Earnings and Technical Parameters
The macroeconomic backdrop faces another immediate milestone with Japan's August labor cash earnings data scheduled for release on Tuesday at 23:30 GMT. Consensus forecasts project cash earnings to decelerate to a 3.7% year-over-year increase, stepping down from the 4.7% expansion recorded in July. A wage deceleration of this scale would significantly weaken the empirical foundation required to justify an immediate October hike. Crucially, Governor Ueda takes the podium prior to the publication of these figures, meaning any policy guidance provided during his morning speech will arrive without the benefit of the latest wage metrics.
From a technical standpoint, the upward momentum in USD/JPY has met consistent friction. The last three sessions have seen daily rallies stall shy of 158.50, which serves as the ceiling established during the October 1 upswing, while the September 24 peak at 159.00 stands as the secondary overhead resistance barrier. On the downside, Monday's intraday trough just beneath 157.50 represents the highest low achieved across the last four sessions, whereas Friday's post-payrolls drop found a base just below 157.00. Technical bias remains tilted toward buyers as long as the 157.50 support holds on a daily closing basis, keeping targets aligned toward 158.50 and 159.00. The daily Stochastic Relative Strength Index (Stoch RSI) sits near 84 and is flattening above 80, suggesting that even a hawkish reception to Governor Ueda's address could trigger a retracement toward 157.50 without invalidating the broader constructive setup, whereas a confirmed close under 157.00 would negate the bullish pattern.
Live Valuation Metrics and Long-Term Structural Drivers
Live market observations show USD/JPY trading at 157.88, registering a 0.09% increase over the previous close of 157.73. Over the past 52 weeks, the currency pair has traveled across an expansive corridor spanning from 149.41 to 163.98, with current trading volume matching its 20-day historical mean at 1.00x. Real-time technical oscillators position the 14-day RSI at 53 in neutral territory. The MACD metric stands at 0.06 against a signal line of -0.19, generating a positive histogram reading of 0.25. Trend tracking moving averages place the 20-day EMA at 157.33, the 50-day EMA at 157.98, and the 200-day EMA at 157.73. With the 50-day EMA maintaining its golden cross above the 200-day EMA, broader trend dynamics point upward. Bollinger Bands outline a band envelope from 153.07 to 159.83 centered around a 156.45 midline, while the 14-day ADX sits at 20, indicating bounded trading conditions. The 14-day Average True Range (ATR) indicates daily volatility of 1.29, establishing an appropriate volatility buffer. The intraday pivot rests at 157.89, bordered by resistance thresholds at R1 157.97 and R2 158.07, and support floors at S1 157.79 and S2 157.71.
As one of the world's premier traded assets, the Japanese Yen's overarching trajectory is dictated by Japanese domestic productivity, central bank directives, differentials between sovereign yields, and prevailing international risk appetite. Between 2013 and 2024, the Bank of Japan maintained an aggressive ultra-loose monetary regime, creating an extreme monetary divergence with peers like the US Federal Reserve. This wide gap between 10-year US Treasury yields and Japanese sovereign debt heavily favored the US Dollar. The central bank's landmark pivot in 2024 to systematically dismantle ultra-loose policies, paired with monetary easing across Western central banks, has begun compressing this sovereign yield premium. Concurrently, the Yen retains its status as a premier safe-haven currency, frequently capturing defensive international capital flows whenever broader financial stress intensifies.
Cross-Currency Dynamics and Global Financial Developments
Tighter financial conditions continue to reverberate across external foreign exchange and commodity spaces. The Australian Dollar showed resilience against the Greenback, with the AUD/USD pair preserving an upward bid around 0.6970 ahead of Tuesday's Asian market open. The pair sustained its recovery trajectory toward the 0.7000 resistance threshold even as the US Dollar posted broad advances, with Australian domestic focus shifting to the incoming Westpac Consumer Confidence survey.
In commodities, Spot Gold regained upward traction, climbing back toward the $4,150 per troy ounce benchmark late on Monday. The precious metal navigated volatile price action as robust US Treasury yields across the yield curve and persistent Dollar demand competed against defensive allocation strategies. Across Europe, the European Central Bank confronts an intricate monetary dilemma; although standard central banking doctrine dictates raising interest rates when inflation runs near double the institutional target, shifting sovereign debt dynamics are already tightening broader financial conditions without direct intervention.