













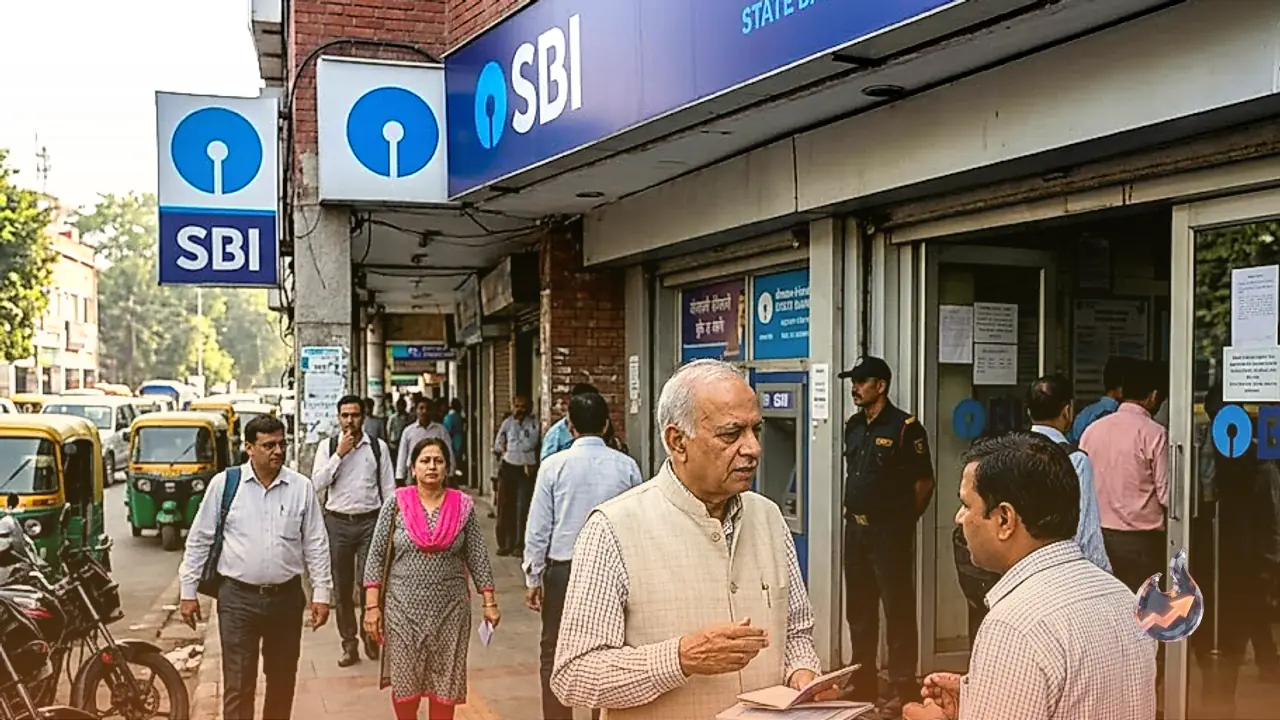

The Reserve Bank of India's decision to increase the repo rate after a hiatus of nearly three and a half years has sent ripples through the financial sector, prompting commercial banks to adjust their lending rates. While institutions like the public sector Uco Bank have quickly updated their repo-linked loan pricing, depositors hoping for a corresponding rise in Fixed Deposit (FD) returns will have to wait. State Bank of India (SBI), the country's largest public sector lender, has made it clear that an immediate upward revision in deposit rates is not on the horizon.
Abundant Liquidity Holds Back Deposit Rate Hikes
According to the newly appointed Chairman of State Bank of India, CS Shetty, the banking sector is currently backed by a substantial volume of excess liquidity. This abundant cash reserve means that major financial institutions are under no immediate pressure to attract fresh capital through higher deposit pricing. Consequently, savers are unlikely to see any upward adjustments in their fixed deposit interest rates for at least the next two to three months. The leadership at SBI indicated that the central bank's decision to raise the repo rate will initially boost the banks' financial health by expanding their Net Interest Margins (NIM) over the next two to three quarters. Only after this period of margin expansion will the bank evaluate the feasibility of raising deposit rates for its retail customers.
The Impact of RBI's Hawkish Monetary Turn
The Reserve Bank of India's Monetary Policy Committee recently chose to elevate the benchmark repo rate by 25 basis points, pushing it up to 5.50%. This policy shift also marked a transition toward a more restrictive, hawkish monetary stance aimed at controlling inflationary pressures within the domestic economy. This move has directly influenced borrowing costs, with more than half of the loans in the Indian banking system tied to external benchmarks. Because the repo rate serves as the primary external anchor for these floating-rate loans, any shift in the central bank's policy rate translates into a near-instantaneous rise in interest rates for borrowers, as demonstrated by Uco Bank's rapid rate revision.
Future Credit Demand May Trigger Rate Adjustments
The trajectory of fixed deposit interest rates in the coming months will largely depend on how credit demand behaves. SBI's top management highlighted that if credit growth continues to expand at its current elevated pace, banks will eventually face a squeeze on funds. To sustain this lending momentum, financial institutions will be forced to mobilize additional resources, which would naturally drive them to offer more competitive deposit rates to savers. Additionally, against a backdrop of persistent inflation, offering depositors a positive real rate of return is essential to encourage savings. The broader market expects that the central bank may implement a cumulative repo rate hike of 75 basis points across two or three separate phases, which would eventually compel the entire banking industry to adjust both loan and deposit pricing.
SBI Maintains Optimistic Credit Growth Forecasts
Despite the tightening monetary environment, State Bank of India remains highly optimistic about its operational performance. The public sector banking giant expects to maintain a robust credit portfolio growth rate of 14% to 15% in the current fiscal period. The bank's internal benchmarks mandate that its credit expansion rate should ideally outpace the nation's nominal Gross Domestic Product (GDP) growth rate by approximately two to three percentage points. Since over 50% of the credit portfolio across the banking industry is linked directly to external benchmarks, the repricing of these assets will occur automatically, providing a steady stream of revenue even as deposit rates remain temporarily frozen.