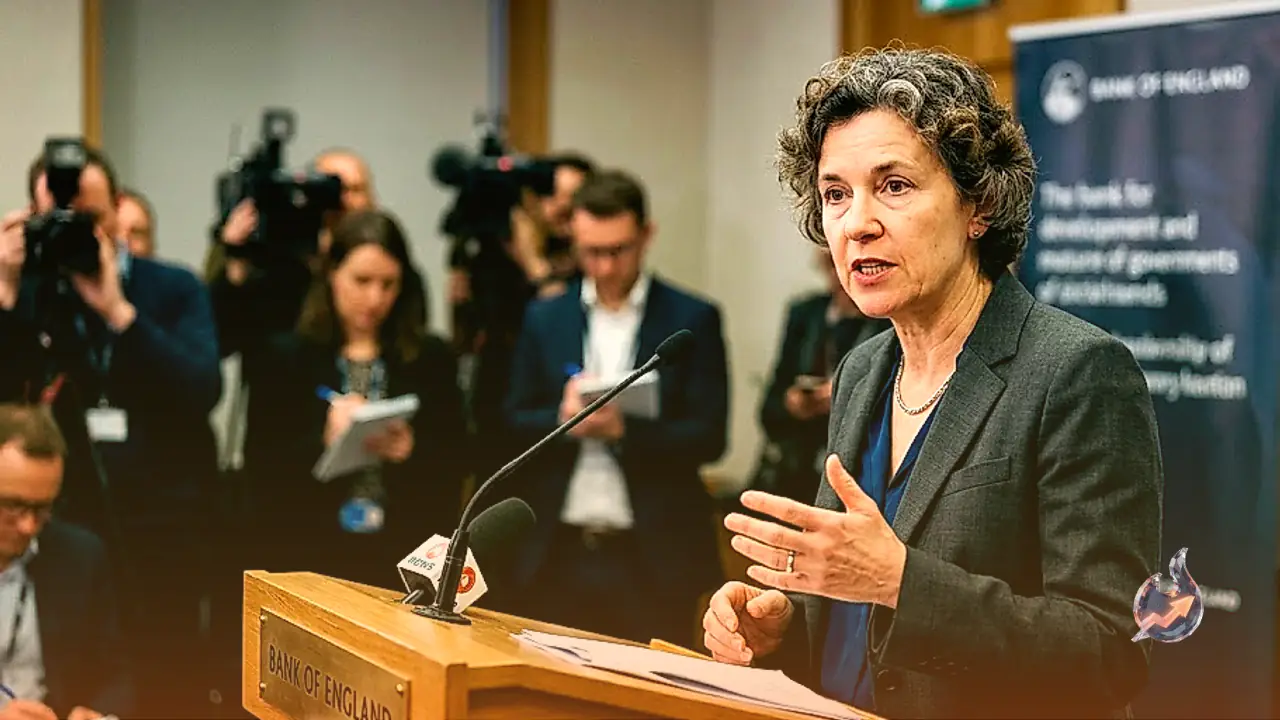














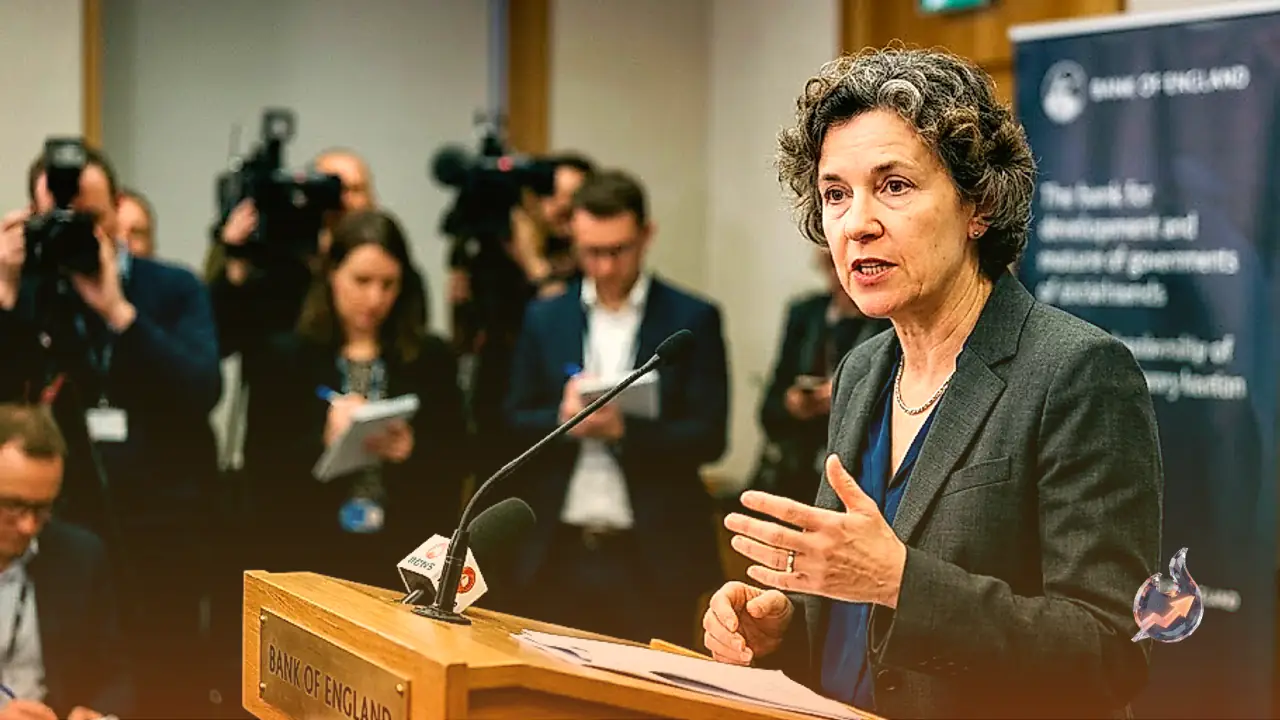

Bank of England policymaker Catherine Mann delivered an explicit call for tighter monetary policy on Thursday, stating that the central bank must raise the benchmark bank rate directly instead of expecting financial market risk premia to perform the heavy lifting of monetary tightening. Addressing the nature of current market conditions, she stressed that borrowing constraints driven by elevated inflation risk and policy uncertainty offer no genuine comfort to rate setters. Rather than waiting for passive tightening across debt markets, the central bank must act deliberately through its own official levers to re-establish monetary control.
The intervention stood out as an unusually aggressive hawkish signal. A specialized speech tracking assessment assigned the address a score of 9.4 out of 10, considerably higher than her historical average rating of 8.1 out of 10. The commentary underlined that tighter financial conditions become counterproductive when they stem from inflation premia and unresolved central bank communication rather than deliberate policy moves. Reflecting on recent missteps, she acknowledged that the Bank of England had not clearly communicated its reaction function following the geopolitical Middle East shock in March. She also noted that omitting a baseline economic forecast in April added unnecessary ambiguity to financial markets, reinforcing the argument that unambiguous rate hikes are now required to restore clarity and policy credibility.
The Mandate of the Bank of England and Rate Dynamics
Operating as the monetary authority for the United Kingdom, the primary objective of the Bank of England is maintaining price stability, anchored to an official 2% consumer inflation target. The principal mechanism for steering the macroeconomy toward this mark is the adjustment of the base lending rate. By dictating the interest rate charged to commercial institutions and the rates at which financial houses exchange funds overnight, the central bank sets the foundation for economy-wide borrowing costs, which in turn acts as a fundamental driver of the British Pound Sterling.
Whenever price increases breach the official 2% objective, policymakers generally respond by lifting borrowing rates to suppress excess domestic demand. Elevating the cost of credit makes mortgages, consumer finance, and commercial capital expenditure significantly more expensive. This dynamic traditionally provides fundamental support to the British currency, as international portfolio managers seek higher-yielding sovereign assets. Conversely, when economic activity cools and inflation undershoots the target threshold, the central bank explores rate cuts to stimulate business investment and credit creation, a sequence that typically places downward pressure on the British Pound.
Balance Sheet Operations: Quantitative Easing Versus Quantitative Tightening
When benchmark borrowing rates near lower limits during profound macroeconomic emergencies, the central bank relies on unconventional tools such as Quantitative Easing. Designed as a measure of last resort when conventional cuts fail to revive stalled credit channels, the process involves electronic asset purchases. The institution creates central bank reserves to buy sovereign debt and top-rated corporate bonds from commercial lenders and non-bank financial institutions. Expanding the national balance sheet in this manner floods the private financial network with capital, though it generally leads to a depreciating effect on the Pound Sterling.
The inverse process, known as Quantitative Tightening, comes into play when inflationary pressures reappear and the broader economic framework gathers momentum. Instead of absorbing debt from private books, the Bank of England halts fresh bond acquisitions and stops reinvesting the principal proceeds from maturing sovereign holdings. By shrinking the aggregate pool of circulating liquidity, Quantitative Tightening reinforces policy restraint and generally acts as a stabilizing or appreciating force for the British Pound.
Movements Across Foreign Exchange and Macro Indicators
Market reactions across international foreign exchange desks reflected sustained strength in the US Dollar on Thursday. In Asian trading hours, the Australian Dollar consolidated close to its two-month trough, navigating the mid-0.6900 territory against the greenback. Although US Personal Consumption Expenditures figures cooled speculation surrounding an October interest rate hike by the Federal Reserve, elevated crude oil costs kept US sovereign bond yields supported near multi-year highs. Domestically, Australia saw its trade surplus contract sharply in August to 495 million Australian Dollars, exerting modest overall influence on the exchange rate.
Concurrently, the US Dollar held firm above 158.00 against the Japanese Yen, lingering near the peak of its weekly range. Elevated American yields and geopolitical uncertainty stemming from the United States and Iran standoff boosted safe-haven allocations toward the greenback, overpowering hawkish expectations surrounding the Bank of Japan alongside intervention warnings from Tokyo. The Euro faced sustained selling pressure as well, dropping to 1.1312 on Wednesday, its lowest standing since May 2025 and well removed from the January high of 1.2082, though fresh Eurozone inflation figures could potentially offer near-term relief. In the background, currency traders remained divided ahead of the critical September Non-Farm Payrolls release, with analysts debating whether the greenback will extend its rally or succumb to overbought conditions.
Pressures on Bullion and Digital Assets
The broader advance of the US Dollar and rising Treasury bond yields also exerted strong friction across commodities and alternative asset classes. Spot Gold traded tightly on Thursday, hovering around $4,167 per ounce with a modest 0.26% gain on the day as precious metals struggled to sustain an early session rebound in the face of elevated real yields.
Digital currency markets exhibited similar consolidation under restrictive monetary conditions. Bitcoin remained confined to a narrow trading corridor bounded by primary support at $82,500 and overhead resistance at $85,000. Ethereum faced persistent headwinds below $2,700, depending on immediate buying interest around the $2,600 threshold to prevent deeper losses. Concurrently, Ripple drifted underneath its critical psychological mark of $1.50, demonstrating that risk assets remain tightly tied to global central banking expectations and bond market movements.