














A highly favorable macroeconomic and political landscape is aligning to drive sustained momentum in the Brazilian Real (BRL). The currency benefits from an intersection of shifting domestic political currents, broad-based commodity trade exposures, and an attractive risk-adjusted carry profile. According to market projections from TD Securities, the Brazilian currency maintains substantial room to appreciate against the US Dollar. While short-term fair-value models place USD/BRL around 5.00 when stripping out political risk premiums, extended forecasts suggest the currency pair is favored to break below 5.00 and approach a long-term fair value near 4.60.
Election Margins and Shifting Political Dynamics in Brazil
The outcome of Brazil's initial presidential ballot has introduced a notable catalyst across foreign exchange desks. The first round concluded with historically tight margins between the contenders. Historical precedents dating back to 1989 reveal that every candidate leading after the first round has ultimately gone on to secure victory in the subsequent runoff. Furthermore, the distribution of remaining voter support reveals a distinct center-right lean, which offers an incremental advantage to Bolsonaro. This favorable political backdrop has reinforced an already constructive narrative for the currency, sparking sharp gains across spot markets.
Macro Foundations, Carry Trade, and Central Bank Trajectory
Beyond headline electoral developments, the Real draws steady support from domestic economic fundamentals. Brazil continues to rely on diversified commodity shipments and healthy trade dynamics. Even as Banco Central do Brasil (BCB) navigates ongoing monetary easing cycles, the Real offers compelling volatility-adjusted carry yields. The initial electoral hurdle having passed also aligns Brazil with a broader rightward tilt seen across Latin America. Strategists note that transient spikes in USD/BRL prompted by global flight-to-safety flows would represent strategic opportunities to accumulate the Real. Should Bolsonaro secure a decisive triumph in the second round, the pair possesses technical momentum to pierce May lows and challenge the 4.80 threshold.
Global FX Markets: Australian Dollar and Japanese Yen Divergence
Across the broader currency sphere, the Australian Dollar encountered resistance early Tuesday during Asian hours. The AUD/USD pair halted a two-day rebound that had lifted it from the two-month trough recorded in the preceding week. Pressures across fixed income markets have held US government bond yields near multi-year peaks, sustaining broader Dollar strength alongside ongoing geopolitical tensions, even as expectations for an October Federal Reserve interest rate increase diminish. Conversely, potential tightening moves by the Reserve Bank of Australia this month offer counterbalancing support for the Aussie.
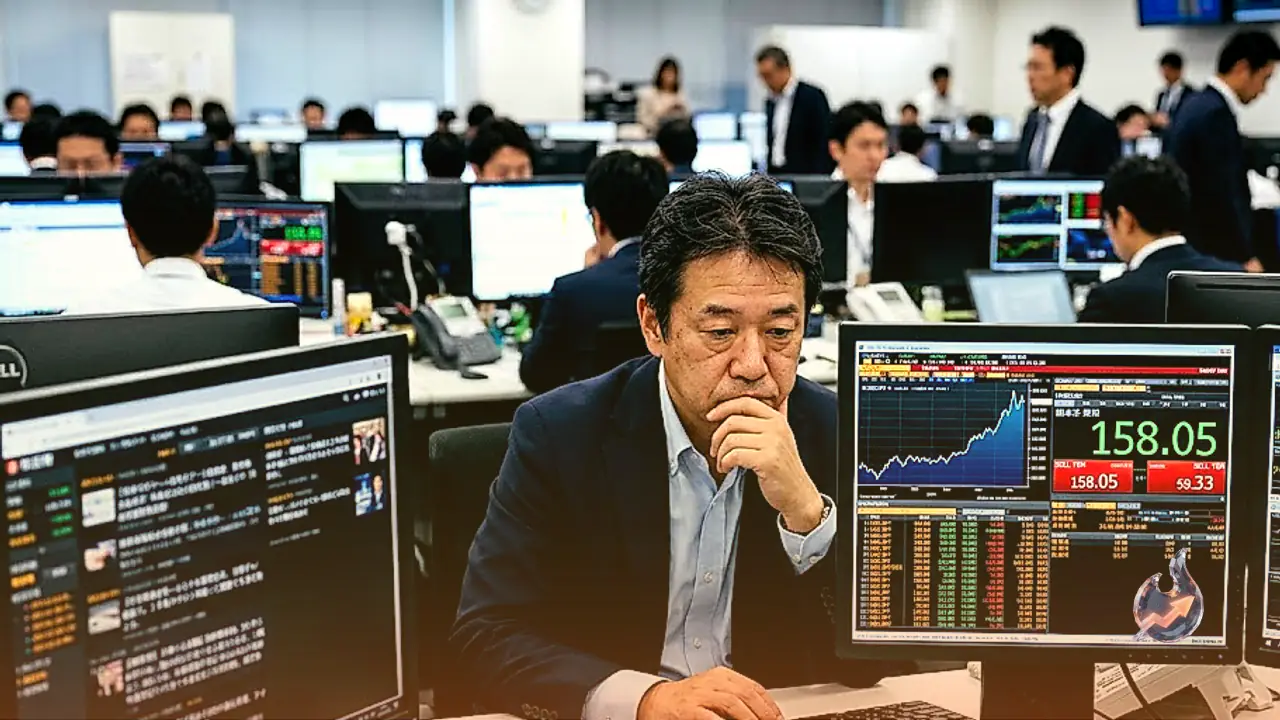
In Asia, USD/JPY pushed back above 158.00 as European trading got underway on Tuesday. The Japanese Yen struggled to find traction despite persistent speculation surrounding potential hawkish policy signals from the Bank of Japan and the ever-present threat of official market intervention. Sustained US Treasury yields and elevated geopolitical unease have anchored the greenback near its year-to-date peaks. The Yen trades tentatively around 158.00 against the backdrop of a dense Japanese macroeconomic calendar and ambiguity over the BoJ's tightening timeline.
Gold Recovery, Cryptocurrency Consolidation, and ECB Tightening Dilemmas
Precious metals experienced a turnaround on Tuesday as softening US Treasury yields tempered Dollar dominance. Gold (XAU/USD) climbed back toward $4,173, reflecting an intraday advance of 0.82%, after touching a two-month low of $4,104 during Asian market dealings.
Digital assets exhibited resilient momentum, with Bitcoin trading near $85,837 on Tuesday despite ongoing seller attempts to curb the prevailing uptrend. Alternative cryptocurrencies largely mirrored this range-bound activity; Ethereum held above $2,700 in sideways trade, while Ripple remained anchored around the critical $1.50 threshold.
Meanwhile, monetary authorities in Europe confront escalating challenges. Under typical economic conditions, an inflation rate tracking at nearly double the official objective would warrant decisive rate increases by the European Central Bank. However, autonomous tightening already executed by bond markets has complicated policy deliberations, presenting the ECB with an acute dilemma.