














Shifting employment dynamics in the United States have triggered a recalibration across global financial markets, as softening September payroll numbers and moderating wage expansion diminished expectations for an imminent interest rate hike by the Federal Reserve in October. Market participants have redirected their attention toward the forthcoming September Consumer Price Index inflation reading to gauge the future trajectory of monetary policy. While the cooling labor market clearly indicated a loss of economic momentum, expectations of eventual policy tightening further down the road remain intact, keeping cross-currency pairs, sovereign bonds, and alternative asset classes highly volatile.
Federal Reserve Outlook and Changing Market Odds
Pricing across interest rate derivatives experienced a substantial realignment in the wake of the latest employment figures. According to Bloomberg WIRP metrics, the implied probability of a rate hike at the October Federal Open Market Committee meeting dropped below 20% as of 5 October, a steep reduction compared to the 64% probability logged on 25 September. Despite this sharp pullback in near-term tightening wagers, financial markets continue to fully price in an interest rate increase by the conclusion of 2026. Evaluating the macroeconomic path, analyst Alvin Liew pointed out that consecutive rate increases for the October FOMC can be effectively dismissed, particularly given that the policy gathering takes place less than a week prior to the 3 November midterm elections.
Outlining the anticipated schedule of monetary adjustments, Alvin Liew observed that two additional rate increases are projected, one in December 2026 and another in the first quarter of 2027, followed by an extended pause throughout the rest of 2027. Consequently, the temporary relief from rate hikes in October is viewed as a deferral of tightening rather than a full pivot toward easing.
Currency Markets React to Treasury Yields and Geopolitics
Even with diminished prospects for an October policy hike, prolonged selling pressure across fixed income markets has kept US benchmark Treasury yields hovering near multi-year peaks. These elevated yields, paired with ongoing geopolitical concerns, provided durable support for the US Dollar, allowing it to sustain upward momentum against major counterparts. During Tuesday's Asian trading session, AUD/USD softened slightly, halting a two-day rebound from the two-month low established the preceding week. The Australian currency nevertheless retains potential support from domestic factors, as expectations for an additional rate hike by the Reserve Bank of Australia later this month could act as a favorable tailwind.
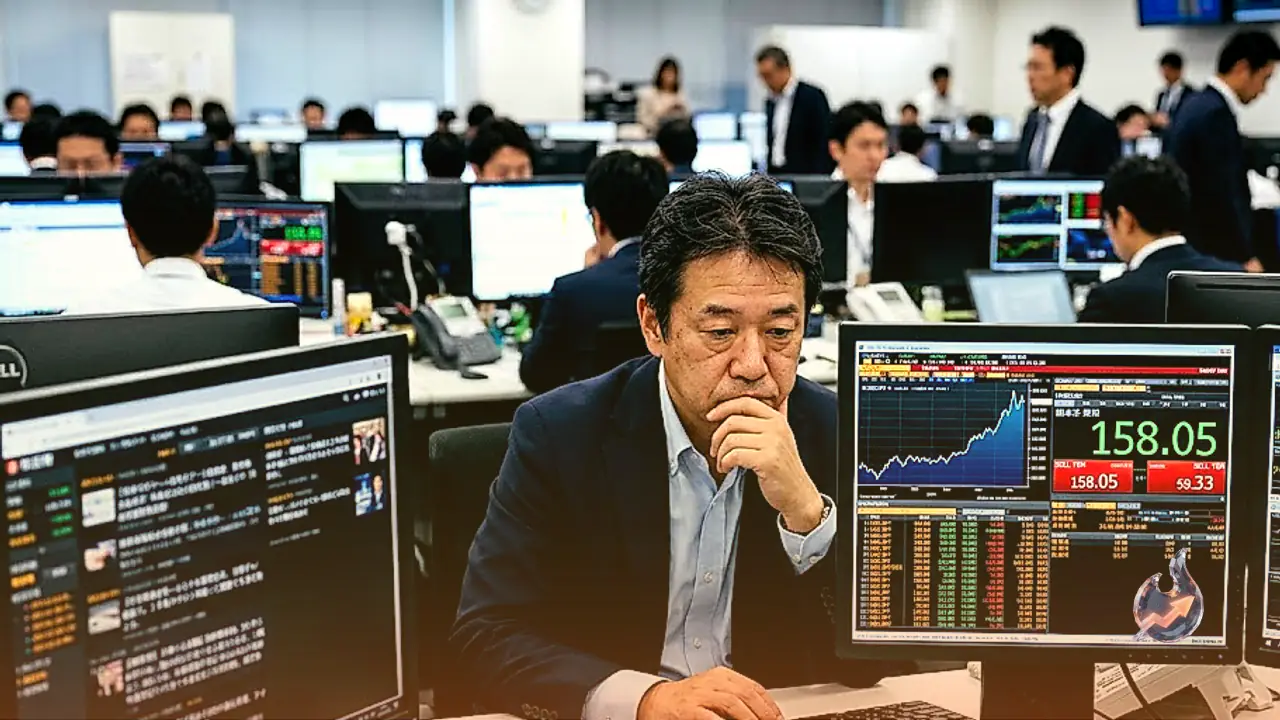
Concurrently, USD/JPY climbed back above 158.00 in early European dealings on Tuesday. The Japanese Yen struggled to generate upside momentum despite prevailing hawkish expectations surrounding the Bank of Japan and the recurring threat of official currency intervention. The Yen continued to drift near the 158.00 threshold against the greenback ahead of a data-dense week in Tokyo and persistent uncertainty regarding the Bank of Japan's normalization timetable. Bolstered by elevated yields and safe-haven flows, the US Dollar stayed pinned near its year-to-date highs, offering steady underpinning to the currency pair.
The European Central Bank Dilemma
In Europe, the macroeconomic landscape presents an intricate challenge for policymakers. Under standard economic conditions, an inflation rate tracking at nearly twice the stated target would typically prompt the European Central Bank to implement prompt interest rate hikes. Current circumstances, however, deviate sharply from historical patterns. Volatility and yield spikes in sovereign debt markets have already carried out a considerable degree of monetary tightening organically, confronting the ECB with a delicate balance between containing price pressures and avoiding unnecessary financial strain.
Gold Rebounds from Lows and Crypto Assets Consolidate
Commodities staged an intraday bounce on Tuesday, driven primarily by a slight softening in US Treasury yields that took the edge off the greenback. Spot Gold (XAU/USD) recovered ground after touching a two-month nadir of $4,104 during Asian business hours. At the time of evaluation, the yellow metal was trading in the vicinity of $4,173, reflecting a daily advance of 0.82%.
Meanwhile, the cryptocurrency market displayed resilience, with Bitcoin maintaining a constructive posture around $85,837 on Tuesday while sellers attempted to regain sway over prevailing price action. Major alternative digital currencies shadowed Bitcoin's consolidation, with Ethereum moving horizontally above the $2,700 benchmark and Ripple fluctuating closely around the key $1.50 psychological barrier.