













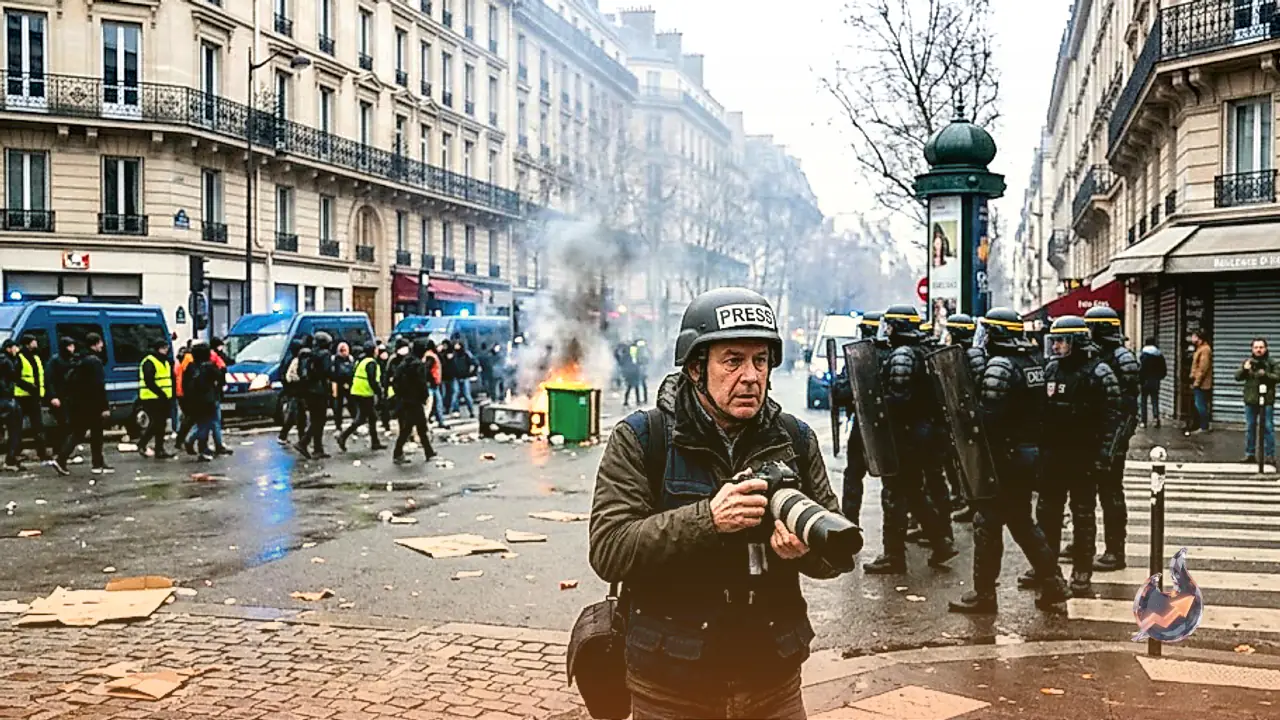

Trading momentum across global foreign exchange desks saw the single European currency backpedal, with the EUR/USD exchange rate losing ground in recent sessions. The decline reflects a confluence of escalating internal unrest in France alongside persistent budgetary anxieties, both of which have weighed heavily on investor sentiment across the continent. Simultaneously, the US Dollar and benchmark US Treasury yields have begun to consolidate and recover footing after enduring a steep correction during the preceding week. Market participants widely project that both the Federal Reserve and the European Central Bank will keep their respective policy rates unchanged at their upcoming October gatherings, though the probability of additional tightening before the close of the calendar year remains an active consideration for institutional desks.
Domestic Unrest in France Elevates Regional Political Risk
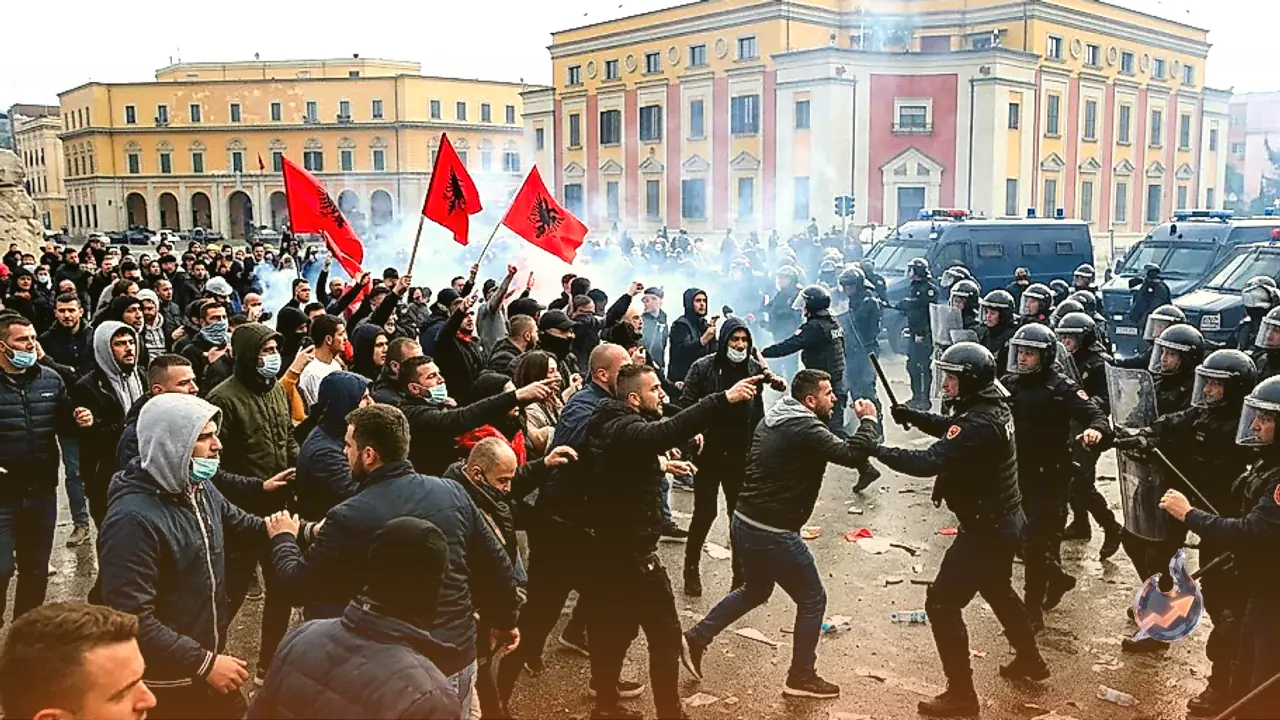
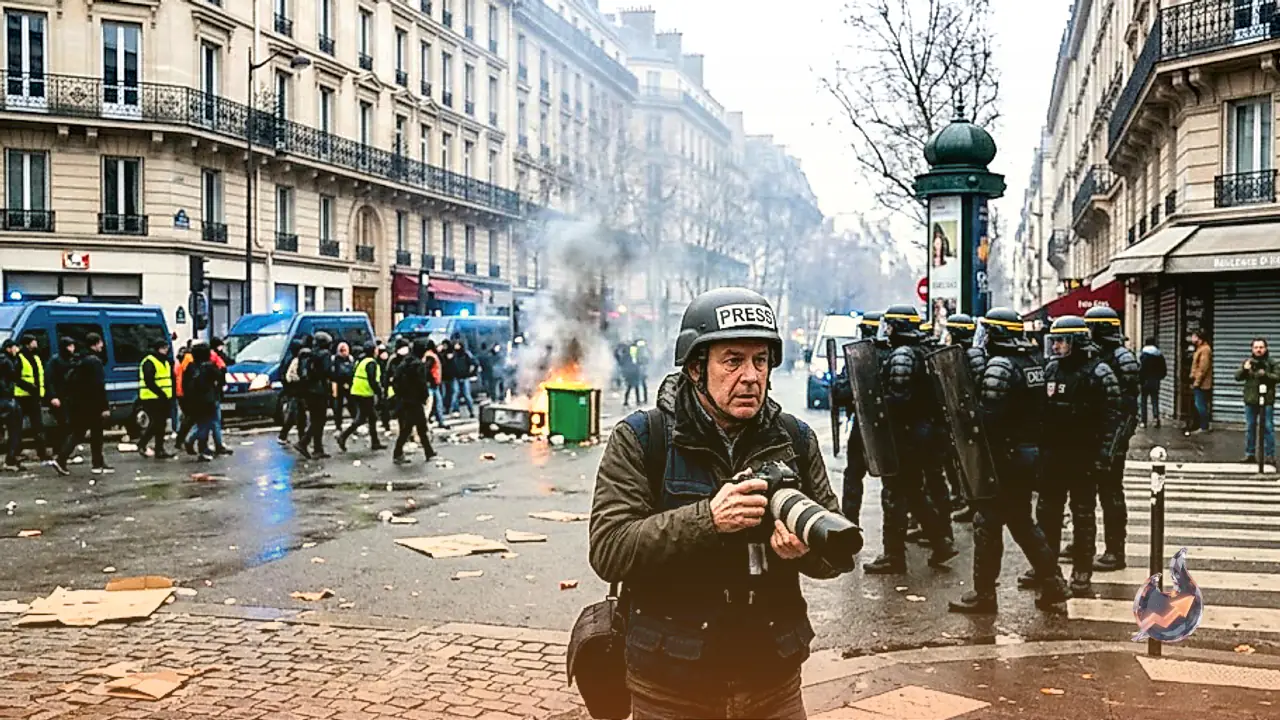
The underperformance of the Euro is occurring against a backdrop of complex and multifaceted macroeconomic crosscurrents. Analysts at Rabobank highlighted that this weakness is unfolding while the broader international economy continues to manage the fallout of severe energy market shocks stemming from conflicts across Europe and the Middle East. Against this fragile international setting, French President Macron has found himself confronted with severe domestic instability, as widespread protests over recent days escalated into destructive civil disorder, rioting, and public looting.
Widespread circulation of visual material showing the historic town hall in Limoges engulfed in flames illustrated the intensity of the civic breakdown, while casualty reports indicated that roughly 1000 police officers sustained injuries amid the clashes. This sharp deterioration in internal stability within France has intensified wider investor scrutiny regarding Europe's sovereign and political risk environment. When a cornerstone economy within the currency union faces institutional gridlock and civil disorder, the execution of critical fiscal consolidation and structural economic reforms becomes significantly compromised, dampening foreign demand for euro-denominated financial instruments.
Resilient US Inflation Data Complicates the Federal Reserve Outlook
Compounding the headwinds confronting the Euro is the renewed vigour of the US Dollar, underpinned by economic indicators that show inflationary pressures within the United States remaining stubbornly elevated. Economists at Deutsche Bank noted that consumer price data exceeded consensus projections, with the headline Consumer Price Index rising by 0.65% month-on-month in September. This acceleration pushed the annualized rate upward from 3.4% to 3.7%.
Underlying inflation trends mirrored this persistent strength, as core CPI registered a 0.33% monthly advance, lifting its annual trajectory by two-tenths to 2.6%. The Producer Price Index similarly topped expectations, and tracking estimates from Deutsche Bank analysts indicate that the core Personal Consumption Expenditures price gauge for September is positioned to rise by 0.36% on a monthly basis, translating to approximately 3.14% year-on-year in the absence of revisions.
These persistent inflationary pulses have revitalized speculative wagers on monetary tightening. While remarks from Fed Chair Warsh have solidified expectations for an operational pause at the scheduled October 28 meeting, fixed-income markets are positioning for a sequential monetary path: a temporary stand-still in late October followed by a potential benchmark interest rate increase at the subsequent policy gathering on December 9. The prospect of an elevated terminal rate in the United States continues to provide underlying yield support to the greenback relative to continental peers.
The Euro's Systemic Scale and Currency Market Structure
The Euro serves as the unified legal tender for 20 member states comprising the Eurozone bloc within the European Union. In the architecture of international finance, it occupies the position of the second most traded currency worldwide, trailing only the US Dollar. Historical transaction metrics from 2022 establish that the Euro was involved in approximately 31% of all foreign currency transactions, facilitating an average daily turnover exceeding $2.2 trillion.
Within cross-border currency pairings, EUR/USD reigns as the most heavily traded vehicle on foreign exchange desks, accounting for an estimated 30% of total worldwide trading volume. Other principal pairings include the Euro against the Japanese Yen (EUR/JPY) at 4% of aggregate volume, the Euro against the British Pound (EUR/GBP) at 3%, and the Euro against the Australian Dollar (EUR/AUD) at 2%. This substantial market footprint ensures that macroeconomic and political developments originating within core European capitals reverberate instantly across the international monetary landscape.
Central Banking Mechanics and the European Central Bank Mandate
Headquartered in Frankfurt, Germany, the European Central Bank operates as the monetary anchor for the entire euro area. The institution bears the responsibility of formulating monetary policy, administering reserve management, and determining policy interest rates across the bloc. The primary legal mandate guiding the ECB is the maintenance of price stability, which necessitates balanced interventions designed to suppress excessive price growth or invigorate flagging economic output.
The central bank executes this objective primarily by adjusting the cost of borrowing. A regime of comparatively higher interest rates, or institutional signalling portending future rate hikes, typically enhances the capital appeal of the Euro by incentivizing global investors to allocate funds into euro-denominated yields. Policy determinations are made by the ECB Governing Council across eight scheduled convenings per calendar year. The governing assembly comprises the central bank governors from each of the Eurozone's constituent nations alongside six permanent executive members, guided by ECB President Christine Lagarde.
Critical Economic Indicators and the Influence of Core Nations
Forex valuations for the Euro remain acutely sensitive to incoming econometric data. The Harmonized Index of Consumer Prices provides the foundational metric by which the ECB monitors domestic price pressures. When inflation readings outstrip expectations and diverge from the established 2% official target, the central bank faces institutional pressure to implement rate hikes to curb runaway aggregate demand.
Broader measures of economic health, such as Gross Domestic Product readings, Manufacturing and Services Purchasing Managers' Indices, employment reports, and consumer sentiment surveys, continuously calibrate market pricing for the single currency. Sustained economic resilience generally fortifies the Euro by drawing non-domestic direct investment and providing monetary authorities with the leeway to maintain firm interest rate settings. Conversely, deterioration in underlying macroeconomic indicators dampens currency demand. In particular, economic outputs generated by the four largest member economies, Germany, France, Italy, and Spain, command exceptional scrutiny, as these four nations collectively generate roughly 75% of the aggregate Eurozone gross domestic product.
Trade Dynamics and the External Balance
The international trade balance represents another pivotal data stream impacting Euro valuation trends over medium-term horizons. This econometric barometer tracks the net divergence between foreign revenue accrued through domestic merchandise exports and sovereign expenditure directed toward foreign imports. When member countries produce desirable, high-value goods that command strong external demand, overseas buyers must acquire the domestic currency to finalize settlements, generating structural upward price pressure on the Euro. Consequently, a persistent surplus in the net trade balance acts as a fundamental tailwind for currency valuation, whereas an expanding deficit tends to erode foreign exchange purchasing power.
Developments Across Parallel Currencies, Commodities, and Crypto Assets
Beyond the European corridor, broad asset classes demonstrated significant realignments across global sessions. The Australian Dollar gathered steady upside momentum, allowing the AUD/USD pair to stretch its recovery trajectory toward the 0.7000 threshold during Asian hours for a second consecutive session. This advance was reinforced by firmer-than-projected third-quarter Chinese GDP prints and resilient September economic activity reports, complemented by hawkish policy commentary delivered by Reserve Bank of Australia Assistant Governor Chris Kent.
Concurrently, the USD/JPY pair hovered defensively near the 158.00 territory. While softer US Treasury yields pulled the greenback near two-week lows, market chatter surrounding sovereign currency intervention alongside hawkish remarks from Bank of Japan Governor Kazuo Ueda provided sustained underpinning for the Yen. Nevertheless, the lingering potential for Federal Reserve rate hikes and broader geopolitical tensions continued to limit substantive downside for the US Dollar.
In commodity markets, Gold (XAU/USD) encountered consolidation headwinds following a constructive weekly opening, as bullion traders digested shifting Federal Reserve interest rate probabilities against the backdrop of firming US bond yields. In digital asset markets, Bitcoin demonstrated resilience by consolidating above $82,000, establishing robust technical support despite weathering roughly $229 million in exchange-traded fund outflows over the previous weekly cycle. Ethereum simultaneously mounted a recovery above $2,400, supported by an inflection in short-term momentum indicators as buyers sought to regain directional control.