













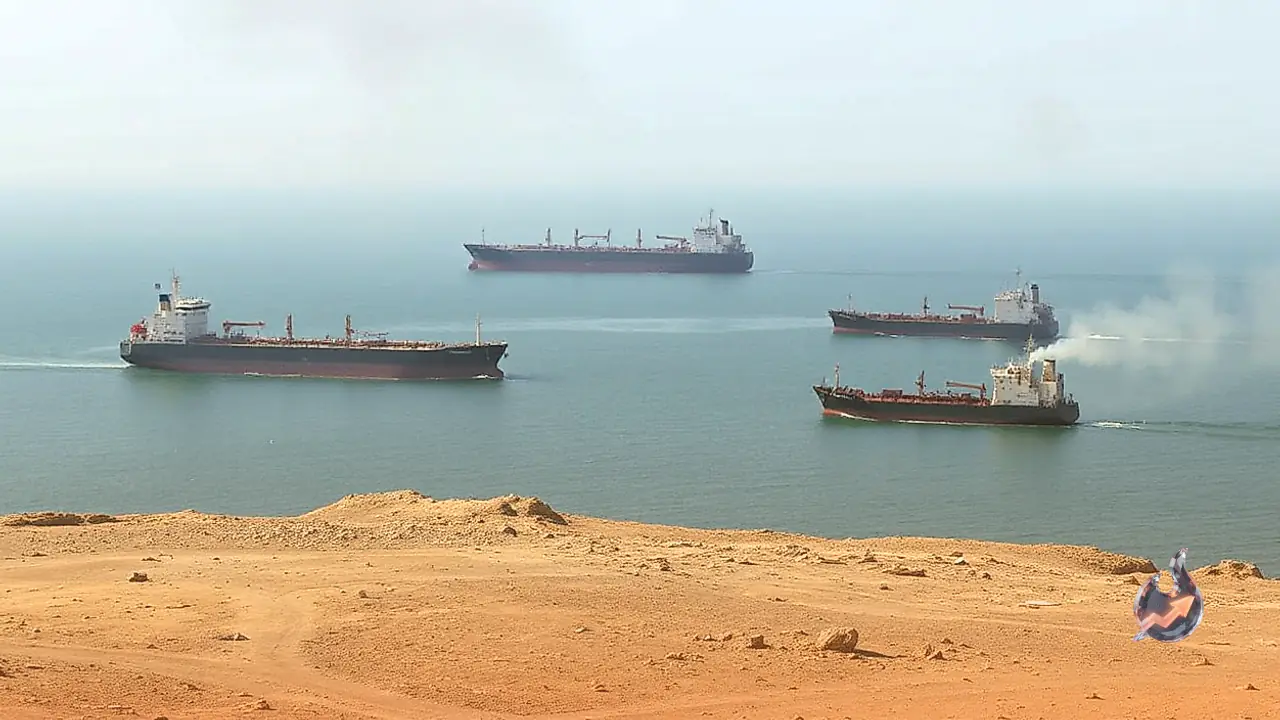

Four crude tankers were destroyed after striking naval mines in waters near the Strait of Hormuz, according to an official statement issued by Iran's Islamic Revolutionary Guard Corps (IRGC). The military body stated that the impacted vessels remained ablaze following the underwater detonations. In the same operation, maritime forces seized two other ships in the surrounding area. The maritime incidents in this vital energy chokepoint unfold against a complex backdrop of shifting commodity valuations and heightened macroeconomic developments across international markets.
Crude Valuations and the Structure of WTI
Despite the severe maritime disruption reported in the Persian Gulf passage, West Texas Intermediate (WTI) crude experienced a downward move, falling 1.30% during the trading day to stand at $94.55 per barrel at the time of writing. WTI represents one of the three principal global benchmarks used to price physical crude oil contracts worldwide, operating alongside North Sea Brent and Dubai Crude.
Within physical commodity trading, WTI is widely characterized as a 'light' and 'sweet' crude stream. The designation reflects its physical properties: a comparatively low density (low gravity) combined with minimal sulfur content. These characteristics make the grade particularly attractive to refiners, as it can be converted into gasoline and other high-value refined products with fewer processing stages. Extracted across fields in the United States, WTI is routed directly through the storage and transit hub located at Cushing, Oklahoma. Often termed 'The Pipeline Crossroads of the World', Cushing serves as the delivery settlement nexus for NYMEX crude futures, making WTI one of the most visible and quoted pricing gauges across financial news services.
Macro Drivers, Geopolitics, and Physical Crude Supply
Pricing dynamics for WTI crude mirror general asset market fundamentals, driven primarily by fluctuations in worldwide supply and aggregate industrial demand. Periods of robust international economic expansion typically lift aggregate fuel consumption, fostering higher equilibrium prices, whereas cooling macroeconomic momentum reduces demand across industrial supply chains. Beyond broader economic cycles, direct structural shocks such as geopolitical conflicts, regional hostilities, and multilateral economic sanctions regularly interfere with logistics corridors and extraction infrastructure.
Coordinated production strategies executed by the Organization of the Petroleum Exporting Countries (OPEC) represent another primary price determinant. Furthermore, because physical barrels trade internationally almost exclusively in US Dollar denominations, foreign exchange fluctuations directly alter physical purchasing power. A softer greenback reduces the cost of dollar-denominated barrels for import nations deploying foreign currencies, whereas a stronger dollar effectively raises import costs and dampens international appetite.
Inventory Gauges: Monitoring API and EIA Weekly Releases
Physical supply balance changes in the United States are tracked closely through consecutive weekly inventory audits released by two dedicated entities: the industry-backed American Petroleum Institute (API) and the official Energy Information Administration (EIA). Net changes in stored crude volumes serve as a barometer for real-time demand absorption relative to refinery throughput.
A drawdown in headline commercial inventories typically signals that current consumption is outpacing new extraction and imports, creating upward price momentum. Conversely, substantial additions to storage facilities suggest oversupplied conditions, dampening spot and futures values. Market participants digest API inventory estimates every Tuesday, followed by the EIA statistical report the subsequent morning. Historically, directional and volumetric readings from both reports align closely, settling within a 1% differential approximately 75% of the time. However, trading desks assign higher credibility to the EIA dataset due to its standing as an official arm of the US government.
OPEC Quotas and the Influence of OPEC+
The Organization of the Petroleum Exporting Countries constitutes a unified coalition of 12 sovereign crude-exporting nations that coordinate aggregate output limits during biannual ministerial conferences. Adjustments to these formal national production quotas generate immediate pricing reactions across global energy exchanges. When member delegations agree to suppress export ceilings, the ensuing supply restriction generally exerts upward pressure on WTI and Brent contracts. Conversely, decisions to expand extraction limits bring additional physical supply to the market, pushing price levels lower.
The market footprint of the cartel broadened through the creation of OPEC+, an extended pact integrating ten sovereign producers outside the original organization. Among these non-cartel partners, Russia maintains the most prominent role, coordinating joint extraction policies that govern a substantial share of total world petroleum exports.
Currency Fluctuations and US Midterm Election Uncertainty
Parallel to movements in raw materials, foreign exchange pairings experienced notable shifts during Wednesday's Asian trading session as vote tabulations from the US midterm elections injected political uncertainty into global capital flows. The Australian Dollar held above a two-week trough against its American counterpart, with AUD/USD changing hands near 0.6965. Early election returns weakened the greenback across several major crosses, while an emergence of defensive positioning prompted a pullback in US sovereign bond yields, counteracting prior market wagers regarding Federal Reserve monetary tightening. Nevertheless, an accommodating stance from the Reserve Bank of Australia (RBA) restrained additional upside for the currency pair.
Concurrently, USD/JPY came under persistent selling interest, retreating below the 158.00 threshold during Asian trade. The dollar sank toward one-month lows as market observers evaluated the likelihood of political gridlock emerging in Washington. This prospect accelerated capital migration toward defensive instruments, dragging Treasury yields lower and reinforcing downward pressure on the dollar.
Treasury Yield Retracement and Bullion Performance
Broader valuation measures tracking the greenback echoed this retreat, with the US Dollar Index facing visible pressure around 101.30 early Wednesday in Asia. Financial market participants maintained focus on incoming legislative tallies to gauge future fiscal and budgetary policy paths. Sovereign borrowing costs retreated across maturities, led by the 2-year Treasury yield, which shed five basis points to reach 4.566%. Meanwhile, the benchmark 10-year Treasury yield fell by six basis points, settling near 4.90%.
Within the precious metals sector, spot gold demonstrated rangebound trading, changing hands near $3,930 per ounce during Asian market hours. Bullion prices struggled to establish sustained direction as market participants analyzed election updates suggesting that the Democratic Party was positioned to secure a working majority in the US House of Representatives.