













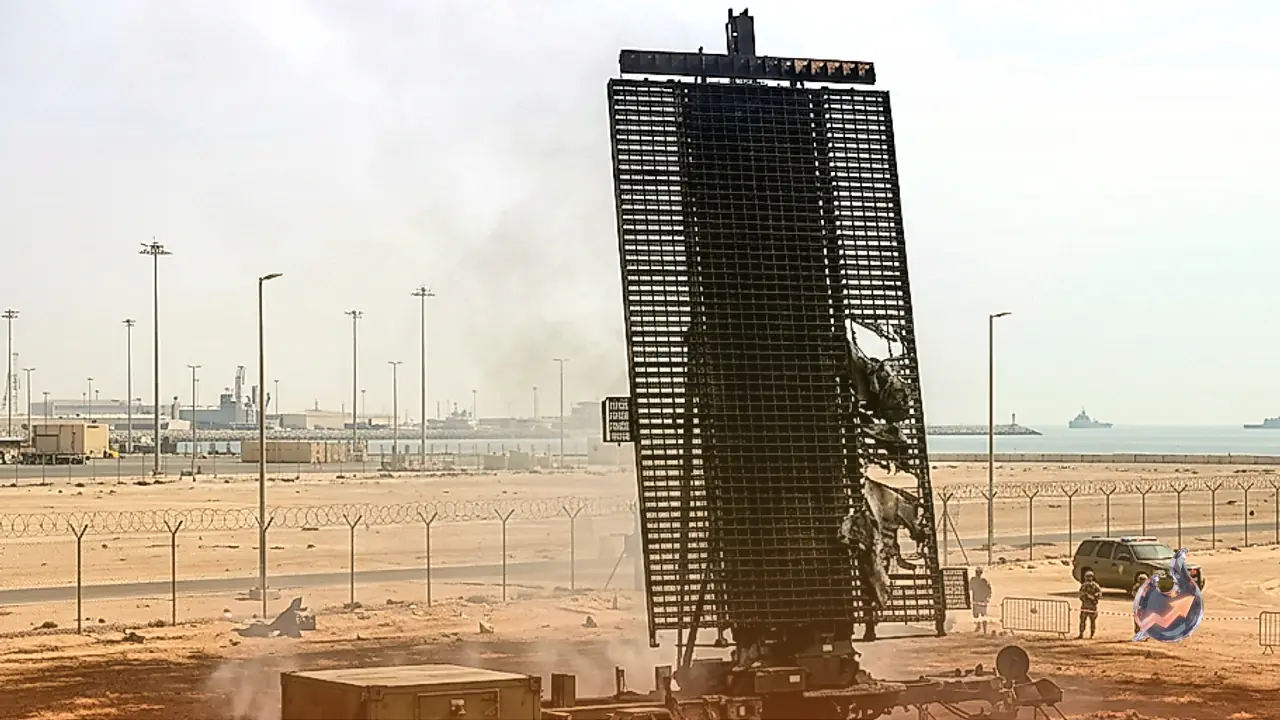

Geopolitical turbulence across the Persian Gulf escalated sharply following an official declaration by the Islamic Revolutionary Guard Corps (IRGC) of Iran, which announced that it had targeted and completely destroyed a United States early-warning radar installation situated in Bahrain. Alongside the military assertion, the IRGC issued an explicit warning declaring that any subsequent strikes or retaliatory operations would precipitate an unrestricted and unlimited confrontation across the theater. Furthermore, the Iranian military apparatus issued direct threats against corporate shipping entities, cautioning that severe penalties would be imposed on any commercial operators collaborating with the United States on crude oil transportation through the Strait of Hormuz.
Immediate Repercussions Across Crude Oil Benchmarks
The immediate reaction across international energy markets highlighted ongoing frictions between physical supply disruptions and broader macroeconomic constraints. In the immediate aftermath of the announcement, West Texas Intermediate (WTI) crude oil registered a decline of 0.65 percent on the day, slipping to trade at $87.47 per barrel. While heightened regional hostilities typically exert sharp upward momentum on energy prices due to maritime transit threats, prevailing foreign exchange strength and monetary policy projections have introduced competing pressures, keeping the primary American benchmark trading in a constrained band despite the volatile security backdrop.
Structural Characteristics and Global Role of WTI Crude
West Texas Intermediate functions as a fundamental pricing cornerstone in international petroleum commerce. Alongside Brent crude and Dubai crude, WTI represents one of the three principal grades that anchor global physical transactions and speculative derivative contracts. In industry terminology, WTI is universally characterized as light and sweet, a designation derived directly from its physical properties. It possesses a relatively low specific gravity, qualifying it as light, combined with a minimal sulfur content, which designates it as sweet.
Because of this refined chemical makeup, WTI crude yields high percentages of premium transport fuels, such as gasoline and low-sulfur diesel, while requiring significantly less complex refining processes than heavier sour alternatives. Originating from oil fields across the United States, physical volumes of WTI converge at the physical storage and terminal network in Cushing, Oklahoma. Revered globally as the pipeline crossroads of the world, Cushing serves as the designated delivery point for physical futures contracts and the central balancing hub for North American crude distribution, making WTI valuations a ubiquitous reference across international financial press and commercial trading desks.
Fundamental Supply and Demand Catalysts
Like all commodities, the market valuation of WTI crude responds primarily to shifting balances between physical supply availability and aggregate global consumption. Robust economic expansion across industrial hubs typically drives heightened petroleum consumption for manufacturing and freight, generating sustained upward pressure on energy prices. Conversely, periods of sluggish international growth or monetary contraction tend to diminish commercial fuel requirements, dampening benchmark valuations.
Beyond macroeconomic trends, geopolitical disruptions, interstate wars, and trade sanctions represent potent catalysts capable of abruptly curtailing physical output or choking maritime corridors. The coordinated decisions implemented by the Organization of the Petroleum Exporting Countries (OPEC) represent another paramount pricing driver, as collective quota modifications directly alter available commercial supply. Furthermore, because global oil contracts are settled predominantly in United States Dollars, the valuation of the greenback exerts an inverse influence: a softening dollar enhances the affordability of crude for foreign currency holders, stimulating broader physical demand, whereas currency appreciation renders energy procurement more costly across international importing nations.
Tracking Storage Dynamics: API and EIA Inventories
Market participants continuously assess real-time supply and demand imbalances by scrutinizing weekly crude inventory audits published by two primary organizations: the American Petroleum Institute (API) and the Energy Information Administration (EIA). Fluctuations in commercial stockpiles offer empirical evidence regarding consumption velocities versus upstream production volumes. A reported contraction in nationwide inventories generally signals that demand is outpacing incoming production, which tends to drive benchmark crude prices upward. Conversely, sizable inventory builds point toward surplus conditions, typically pulling market prices lower.
The scheduling of these data releases follows a standardized weekly cadence, with the American Petroleum Institute presenting its industry-compiled survey late Tuesday, followed by the official government figures from the Energy Information Administration on Wednesday. Historically, the two datasets exhibit a high degree of correlation, producing matching directional figures within a 1 percent variance approximately 75 percent of the time. Nonetheless, market participants assign greater reliability and institutional weight to the EIA release, given its status as an official federal statistical agency.
The Strategic Influence of OPEC and the OPEC+ Coalition
The Organization of the Petroleum Exporting Countries encompasses 12 petroleum-producing nations that systematically coordinate national production volumes to influence global petroleum prices. Convening at formal biannual assemblies, member states agree upon binding export and extraction quotas. When the organization elects to curtail member production quotas, it tightens physical availability on global exchanges, prompting sharp price increases. Conversely, quota expansions inject additional barrels into international channels, exerting downward pressure on market valuations.
The institutional scope of this pricing power broadened significantly through the formal creation of the OPEC+ alliance, which integrates ten supplementary non-OPEC oil-producing states alongside the original cartel members. Among these additional participating nations, Russia stands as the most strategically vital and influential counterweight. The unified decisions executed across the broader OPEC+ framework represent one of the single most influential determinants of sovereign crude pricing worldwide.
Refined Product Divergence and Persistent Inflation Risks
While crude oil benchmarks have shown volatility, wider downstream dynamics present a complex inflationary picture. Brent crude has dropped by roughly one-third since mid-October, largely fueled by persistent diplomatic expectations surrounding a potential conclusion to the Iranian conflict. Nevertheless, downstream retail realities have sharply decoupled from raw crude trajectories, as production costs for diesel, maritime freight, and agricultural fertilizers have failed to replicate the decline observed in crude contracts.
Energy economists warn that these stubborn underlying transport and industrial inputs do not impact end consumers instantly; rather, elevated diesel and logistics expenses filter through to United States consumer prices in progressive stages extending through 2027. Consequently, even as everyday gasoline becomes noticeably more affordable at the retail pump, persistent freight and fertilizer overheads threaten to entrench broader consumer inflation over the extended medium term.
Foreign Exchange Pressures and Bullish Dollar Momentum
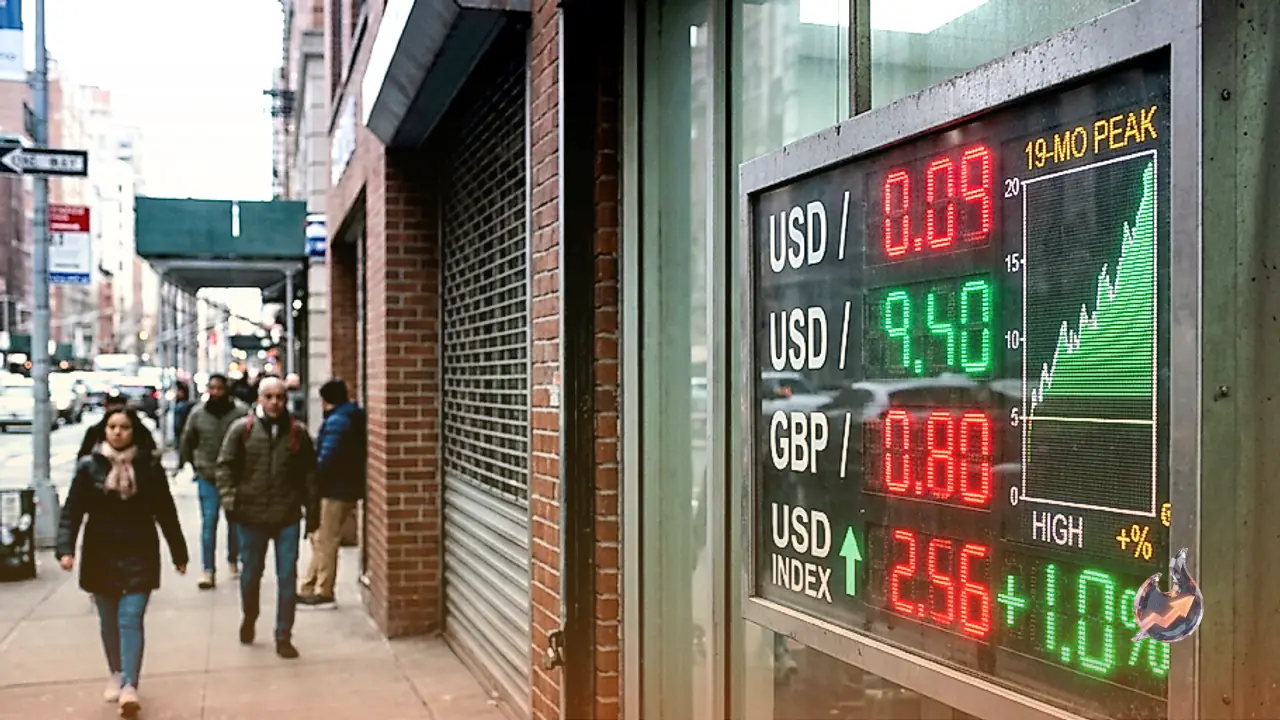
Currency markets have concurrently absorbed the dual shocks of heightened Middle Eastern instability and evolving interest rate expectations. During Friday's Asian trading session, the Australian Dollar struggled near a 10-month trough against the greenback (AUD/USD), testing critical support zones and awaiting an explicit break below 0.6800 before initiating another downward leg. Resurgent expectations surrounding aggressive Federal Reserve rate hikes, paired with evaporating optimism regarding United States-Iran diplomatic rapprochement, have propelled the US Dollar to its strongest valuation since April 2025. Concurrently, a decidedly dovish policy tilt adopted by the Reserve Bank of Australia (RBA) has further weakened the Aussie currency, reinforcing institutional projections of continued downside.
Simultaneously, the US Dollar versus the Japanese Yen (USD/JPY) entered an extended consolidation phase near its highest price levels since early September. Upward momentum grew cautious as market participants positioned around the psychological 160.00 barrier due to acute currency intervention risks by Japanese authorities. However, substantial downside retracements appear tightly buffered, as the wide interest rate disparity between Washington and Tokyo maintains the profitability of the classic Yen carry trade. Bolstered by the lingering potential for a jumbo Federal Reserve rate increase and escalating Middle Eastern uncertainty, the greenback holds firmly near a 19-month peak, providing steady underlying support to the currency pair.
Precious Metals and Cryptocurrency Trends
Alternative asset classes have similarly experienced significant volatility under current macro pressures. Spot gold advanced by nearly 0.9 percent to approach $3,915 per ounce during early Friday transactions, following a steep drop to a 13-month low near $3,850 in the preceding trading session. Despite the immediate rebound, analysts suggest that this technical recovery from the sharp selloff that commenced on Tuesday may prove short-lived, as multiple macro headwinds, including soaring real yields and aggressive dollar demand, enable bearish market forces to retain overall control.
In the digital asset sector, Bitcoin confronted heavy institutional liquidation, driving prices below the crucial $70,000 threshold on Friday after experiencing a drop exceeding 3 percent during the prior day. The premier cryptocurrency has lost more than 5 percent across the current weekly stretch, positioning the asset for a potential sixth consecutive week of net losses. Although technical momentum indicators suggest the downtrend is severely stretched into oversold territory, the broader technical setup remains decidedly negative as sellers continue to dominate market liquidity.
International Profiles in an Evolving Economy
As international capital markets adapt to complex cross-currents spanning military posturing, monetary tightening, and commodity volatility, individuals and enterprises are increasingly traversing globalized operational landscapes. Exemplifying this borderless commercial environment is Lallalit Srijandorn, a digital entrepreneur operating across both Paris and Bangkok. Having established her residence in France in 2019 while maintaining deep cultural affinity for Paris, her cross-continental business activities reflect the interconnected nature of contemporary commerce, where digital enterprise and real-world geopolitical realities continually intersect across global financial centers.