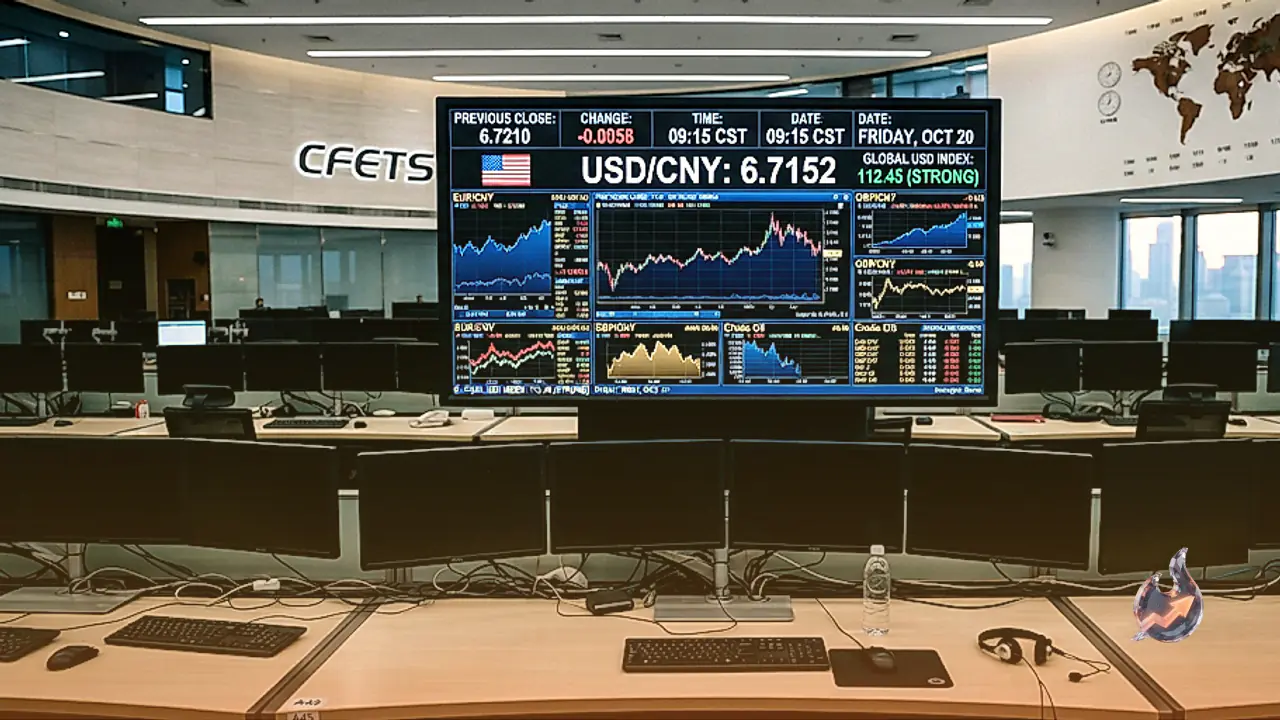















The United States Dollar continues to find strong underlying support in global financial markets, driven by stubborn inflationary pressures in the United States and growing expectations of additional monetary tightening by the Federal Reserve. A broad deterioration in global risk appetite has pushed market participants toward safe-haven assets, providing further momentum to the greenback. While upcoming midterm elections are viewed as a medium-term headwind, market strategists anticipate that the currency will stay underpinned through the end of the year before entering a gradual cooling phase in 2025 as the boost from relative interest rate advantages reaches its peak.
After an initial pause in October, another firm consumer price index report has solidified market expectations of tighter policy moves before the close of the calendar year. Stéfane Marion and Kyle Dahms, strategists at the National Bank of Canada, highlighted this dynamic, noting that safe-haven flows triggered by fragile global risk sentiment are reinforcing the currency. The strategists expect the dollar to remain supported through year-end before weakening gradually in 2025 as relative-rate support peaks.
Dollar Dominance Weighs on Major Currency Pairs
The persistent strength of the US Dollar has reverberated across foreign exchange markets, putting pronounced downward pressure on other major counterparts. During Friday's Asian trading session, the AUD/USD pair hovered near a 10-month low, waiting on a potential break below the 0.6800 threshold amid strong dollar demand. Mounting expectations of additional rate increases from the Federal Reserve, combined with diminishing prospects for diplomatic resolutions between the United States and Iran, have sustained the dollar near its highest level since April 2025. Adding to the pair's vulnerability, the Reserve Bank of Australia has adopted a dovish tilt, reinforcing expectations of further downside for the Australian currency.
Simultaneously, the USD/JPY currency pair entered a consolidation phase around its highest mark since early September, with market participants turning cautious near the 160.00 zone due to the threat of official market intervention. Despite that overhead risk, significant downside appears cushioned because the substantial interest rate differential between the United States and Japan keeps the Yen carry trade highly active. Coupled with the possibility of a jumbo rate hike from the Federal Reserve and lingering uncertainties in the Middle East, the dollar has held near a 19-month high, lending steady support to the cross.
Gold Price Rebound and the Inflation Transmission Pipeline
In precious metals, gold staged a recovery of nearly one percent from the year-to-date low touched on Thursday, managing to reclaim the $3,900 mark despite an otherwise bearish fundamental backdrop. A minor pullback in the US Dollar from its 19-month peak provided temporary breathing room for bullion ahead of the release of US producer price index data. Nonetheless, aggressive rate-hike projections from the Federal Reserve continue to present a serious headwind that could restrict further upside for non-yielding bullion assets.
Energy markets have displayed divergent dynamics. Brent crude oil has tumbled approximately one-third since the middle of October as market participants price in expectations that the conflict involving Iran may be drawing toward a resolution. However, critical downstream expenses such as diesel fuel, logistics freight, and fertilizer prices have failed to drop in tandem. These elevated input costs are projected to feed into US consumer price measures in distinct stages through 2027, raising the prospect that broad inflation measures could remain sticky even as retail gasoline becomes more affordable.