













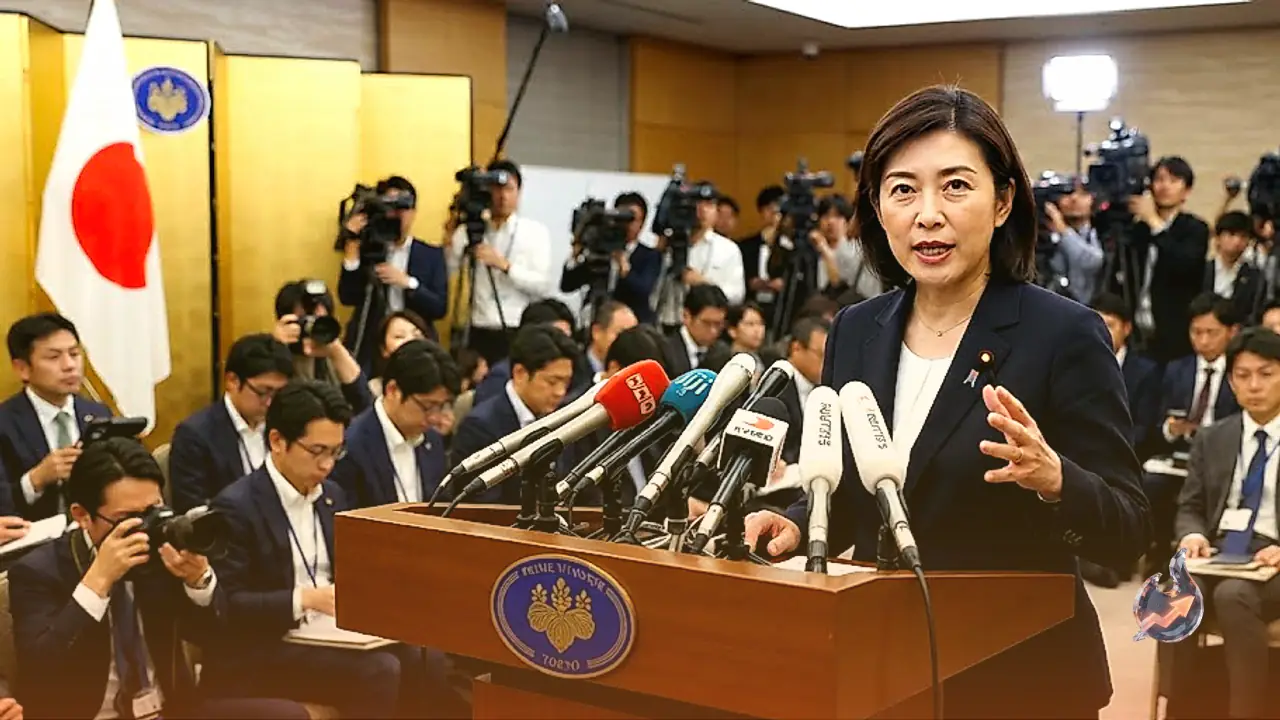

Japanese Prime Minister Sanae Takaichi clarified the administration's fiscal and debt management direction on Monday, stating that the government holds no predetermined position regarding the compilation of a supplementary budget. Takaichi underscored that official plans center on keeping the issuance of Japanese Government Bonds (JGB) at a well-balanced and appropriate volume. The Prime Minister stressed that establishing a resilient domestic economic foundation remains the primary requirement for bolstering financial market confidence in the Japanese yen. Following these statements, trading desks witnessed steady movement across currency pairs, with the yen edging upward against major counterparts.
Fiscal Discipline and Currency Market Adjustments
During trading operations, the USD/JPY pair reflected early sensitivity to the remarks, shedding 0.07 percent to hover near 157.90. The issuance volume of Japanese Government Bonds carries substantial weight for national debt sustainability and market liquidity. Excessive sovereign debt issuance risks diluting fiscal credibility and placing downward pressure on currency valuation. By stressing an appropriate issuance pace and refraining from an automatic commitment to supplementary spending, the administration signaled a disciplined fiscal posture aimed at promoting economic strength without triggering unnecessary domestic borrowing.
The Bank of Japan Mandate and Monetary Evolution
The Japanese Yen ranks among the most liquid and widely traded currencies across international foreign exchange desks. Its valuation is traditionally shaped by Japan's broader economic indicators, Bank of Japan policy decisions, the spread between domestic and foreign bond yields, and general investor appetite for risk. A cornerstone of the Bank of Japan's core mandate involves maintaining currency stability, making its policy pivots vital for global currency traders. While direct foreign exchange market interventions have occurred historically to curb excessive currency swings, policymakers typically exercise restraint to avoid diplomatic friction with core international trading partners.
Between 2013 and 2024, the Bank of Japan pursued an extensive ultra-loose monetary policy framework characterized by negative interest rates and yield curve controls. This prolonged policy caused a dramatic divergence between Tokyo and other leading central banks that were actively raising rates to combat domestic inflation. Consequently, global capital flowed toward higher-yielding foreign sovereign debt, driving prolonged depreciation in the Japanese yen. The recent, measured dismantling of this ultra-accommodative framework has started offering structural support to the currency, limiting further downside risks.
Yield Differentials and Shifting Pressure on the US Dollar
The yield disparity between 10-year United States Treasuries and corresponding Japanese government paper served as the primary engine powering the US Dollar against the Yen over the last decade. Widening spreads persistently favored dollar-denominated assets. However, the Bank of Japan's 2024 shift away from extreme monetary easing, combined with interest rate cuts undertaken by several international monetary authorities, has begun compressing this sovereign spread.
Fresh selling interest greeted the USD/JPY pair during Asian market hours on Monday, keeping price action above the previous week's cyclical swing low. A concurrent softening in United States Treasury yields anchored the greenback near a two-week low. Furthermore, remarks delivered by Bank of Japan Governor Kazuo Ueda reinforced expectations of policy vigilance, keeping speculative currency intervention risks in play. Nevertheless, market expectations regarding Federal Reserve rate trajectories and persistent geopolitical friction globally may mitigate deeper losses for the dollar, offering an underlying floor to spot rates.
Safe-Haven Dynamics and Investor Allocation
The Japanese Yen retains a distinct standing as a classic safe-haven asset among international fund managers. During periods of pronounced cross-asset volatility or geopolitical stress, capital routinely moves into yen-denominated holdings due to Japan's strong net external asset position and perceived institutional reliability. Heightened financial market unease frequently triggers yen appreciation relative to riskier emerging and commodity-linked currencies. Prime Minister Takaichi's emphasis on building a robust economy directly targets the reinforcement of this underlying structural confidence.
Movements Across Australian Dollar and Precious Metals
Parallel developments unfolded across other asset classes on Monday. The Australian Dollar gained sustained traction for a second consecutive session, extending its recovery from sub-0.6900 marks toward fresh multi-month highs. Hawkish guidance from Reserve Bank of Australia Assistant Governor Chris Kent provided direct momentum to the antipodean currency ahead of scheduled Chinese macroeconomic data releases. The subdued tone in US yields added further upward momentum to the AUD/USD pair.
Simultaneously, gold commenced the week on firm footing, eyeing a sustained breakout above the crucial $4,200 threshold. Depressed US yields diminished the holding cost of zero-yield bullion, encouraging buyers. However, persistent safe-haven interest tied to geopolitical conflicts and lingering debate around prospective Federal Reserve policy moves provided sufficient dollar stability to contain runaway advances in spot gold pricing.