













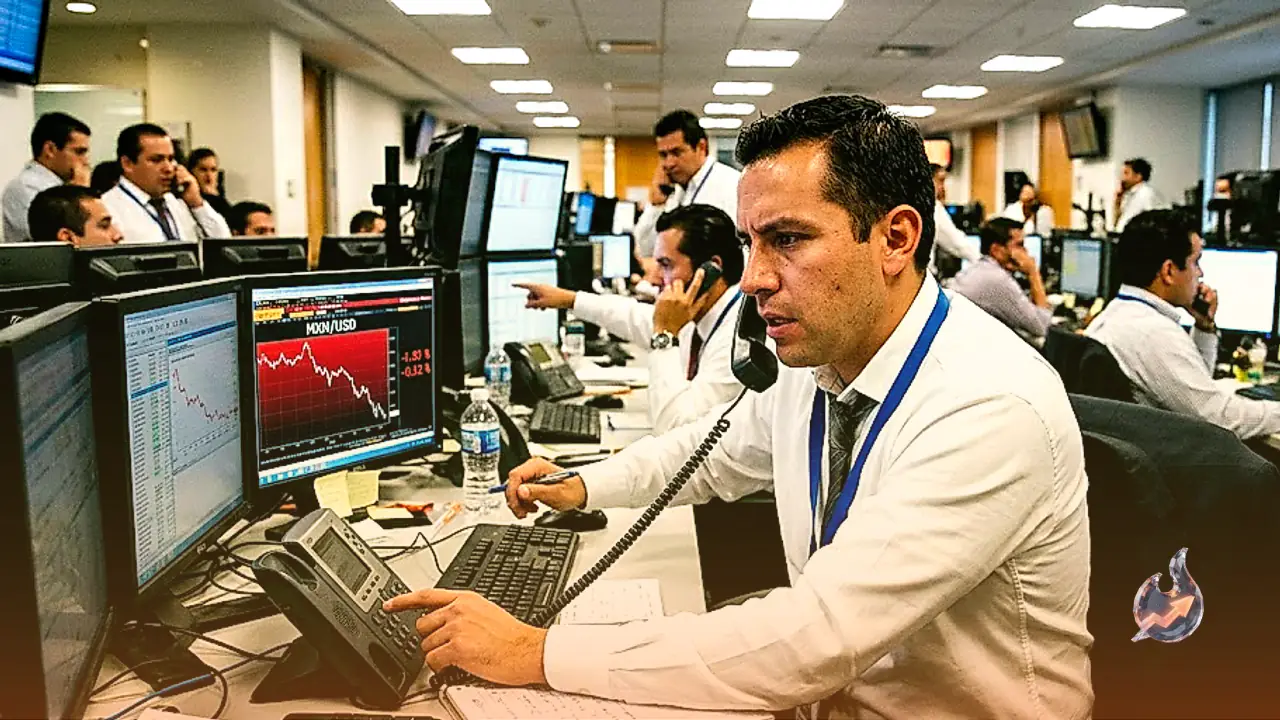

Global foreign exchange markets are experiencing notable tremors across emerging economies, marked by a pronounced retreat from carry trade strategies as September draws to a close. The Mexican Peso has taken the brunt of this shift, falling 6% against the US Dollar on a spot basis during the month, while logging a 5.2% decline on a total return basis. Market strategists point out that whether this currency adjustment deepens through the fourth quarter will hinge largely on the trajectory of US Treasury yields, global oil prices, and the broader fiscal policy consequences stemming from the US mid-term election results.
Carry Trade Unwinding and Pressure on Emerging Currencies
Carry trades, where investors borrow in low-yielding currencies to buy higher-yielding emerging market assets, experienced aggressive liquidation over recent weeks. Kenneth Broux of Societe Generale identified this rapid unwinding across emerging markets as one of the defining developments of September, with the drop visible most sharply in the Mexican Peso. Looking into the final quarter of the year, an extended sell-off in US long-dated bonds alongside a potential rebound in the Japanese Yen could intensify the strain on carry positions, worsening the tactical pullback across currencies such as the Peso and the South African Rand.
The South African Rand (ZAR) is navigating an equally critical technical threshold. Having recovered from levels below 16.00, the Rand is trading around its 200-day moving average near 16.38. This precarious positioning persists despite the South African Reserve Bank (SARB) delivering a 25 basis point interest rate hike, an adjustment that the currency market effectively overlooked as broader global macro pressures dominated sentiment.
Asia Session FX Movements: Australian Dollar and Japanese Yen
Currency action in Wednesday's Asian trading session showcased contrasting dynamics across major pairs. The Australian Dollar hovered near two-month lows around 0.6950 against the greenback. The weakness came after Australia's underlying Consumer Price Index (CPI) figures for August arrived softer than expected, dampening projections for additional interest rate increases from the Reserve Bank of Australia (RBA). Concurrently, fresh Chinese Purchasing Managers' Index (PMI) data failed to provide upward momentum for the Australian currency, despite a temporary halt in the US Dollar's recent run.
In contrast, USD/JPY sustained losses below the 157.00 mark during Asian trading hours. The Japanese Yen drew support from lingering expectations of a hawkish Bank of Japan (BoJ) stance as well as market vigilance regarding potential official currency intervention. These factors counterbalanced downbeat Japanese domestic retail sales and factory output readings, while a broader step back in the greenback further aided the downside move in the currency pair.
Gold Consolidates Around $4,200 as Bitcoin Stalls Near $83,000
Trading in commodities and digital assets reflected a similar mood of hesitation. In the European session, gold maintained its consolidative posture, changing hands near the $4,200 threshold. Declining US bond yields pulled the US Dollar back from the two-month peak recorded on Tuesday, offering a modest tailwind for bullion. Nonetheless, expectations that the Federal Reserve will maintain a hawkish leaning continued to cap upside price potential, as commodity desks waited for fresh macro signals before committing capital.
Meanwhile, Bitcoin moved sideways around the $83,000 handle on Wednesday. The pause followed an unsuccessful attempt by buyers earlier in the week to secure a daily close above the $85,000 resistance milestone. Elevated US Treasury yields and an extensive slate of major US economic releases scheduled throughout the week have kept cryptocurrency market participants firmly in a risk-managed holding pattern.
Focus Shifts to US PCE Inflation Release
Investors across all asset classes are closely calibrating exposure ahead of top-tier economic releases from Washington. The United States Bureau of Economic Analysis is slated to release the Personal Consumption Expenditures (PCE) Price Index for August on Wednesday at 12:30 GMT. The PCE metric serves as the Federal Reserve's preferred inflation barometer, making its outcome pivotal in dictating upcoming interest rate expectations and the near-term path of the dollar.