













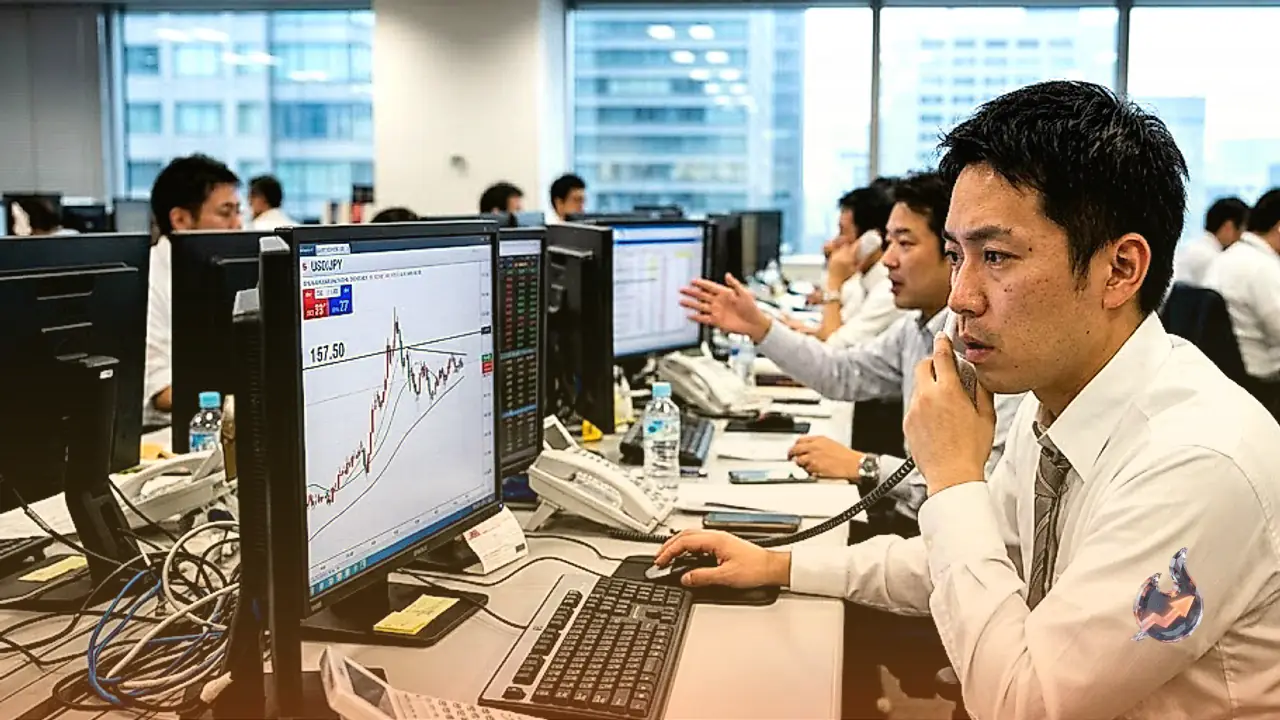

Trading in the USD/JPY currency pair settled into a narrow band following a sharp retreat from the 159.00 threshold. The pair concluded Monday's trading session just beneath 157.50, successfully defending the bulk of the decline triggered late last week. During the session, spot rates touched an intraday low of 156.50 before rebounding to recoup ground. Live market readings show USD/JPY trading at 157.41, representing a marginal change of negative 0.04 percent from the prior close of 157.46, within a broader 52-week trading span of 149.41 to 163.98. Market participants remain focused on potential sovereign intervention, incoming macroeconomic metrics, and lingering interest rate differentials.
Bilateral Discussions Highlight Trade Strains From Weak Currency
The catalyst behind the currency pair's sudden reversal emerged after Finance Minister Katayama confirmed that President Trump expressed reservations regarding the weakness of the Japanese currency during a bilateral summit with Prime Minister Takaichi held on Tuesday in New York. Prime Minister Takaichi corroborated that the exchange rate levels were cited as creating trade difficulties for the United States. Furthermore, Katayama stated that future coordinated intervention alongside US authorities remains an active option, with both leaders affirming that stance.
Given that monetary authorities in Japan and the United States previously executed joint yen purchases in late July, the public acknowledgment by an American president has reinforced the credibility of another collaborative market operation. Katayama had previously reiterated that the foundational principles governing the July intervention remained intact, an environment that had initially pushed USD/JPY to 159.00 on Thursday before Friday's disclosure forced the pair below 157.00 within the same trading session.
Technical Indicators Outline Critical Support and Resistance Zones
From a chart perspective, the 50-day Exponential Moving Average located near 158.00 forms the initial ceiling for any upward movement. USD/JPY established daily closes above this technical marker on September 23 and September 24 before slipping back beneath it on Friday. In live technical calculations, the 50-day EMA stands at 158.04, with the 20-day EMA positioned at 157.08 and the 200-day EMA at 157.69. A clearance of this immediate barrier would expose Thursday's peak situated slightly above 159.00, the origin point of the latest corrective slide, with longer-term resistance mapped around 160.38.
On the downside, Monday's intraday base around 156.50 acts as initial support. A sustained break beneath that floor points to the September 18 low registered just beneath 156.00, followed by broader support around 152.90. The prevailing market bias remains positive above 156.50, carrying upside targets toward 158.00 and 159.00, though the threat of official market intervention presents a notable hurdle near 159.00. A daily close beneath 156.50 would effectively nullify this constructive setup. Momentum readings show the daily Stochastic Relative Strength Index near 66, recovering from the low 20s recorded in mid-September. Live readings indicate a 14-period RSI of 51, Stochastic lines at 72 and 81, an ADX of 27 confirming trend presence, and a central daily pivot at 157.40, flanked by support at 157.21 and resistance at 157.60.
Economic Releases and Official Intervention Scrutiny
Market attention is shifting toward incoming Japanese economic data. Projections for Tokyo core consumer price inflation indicate an acceleration to 2.4 percent year-on-year for September, up from 1.8 percent previously. Concurrently, the Bank of Japan's Tankan large manufacturers' sentiment index is anticipated to climb to 25 from 22. In their recent actions, both the Federal Reserve and the Bank of Japan implemented 25 basis point interest rate hikes, with policymakers in both jurisdictions confronting inflation pressures and underscoring that subsequent adjustments will hinge strictly on economic prints.
Additionally, Japan's Ministry of Finance is scheduled to release official data on Wednesday detailing the aggregate volume of yen purchases conducted between August 27 and September 28. This disclosure will clarify whether the rate checks conducted on September 18 were followed by actual capital deployments in the foreign exchange market.
Monetary Divergence and Macroeconomic Headwinds
The Japanese yen ranks among the world's most actively exchanged currencies, with its valuation dictated by underlying macroeconomic performance, central bank directives, bond yield variations against US Treasuries, and cross-asset risk appetite. Currency stabilization forms an integral part of the Bank of Japan's policy mandate, though direct market intervention is deployed selectively due to political sensitivities among major trading partners. The protracted era of ultra-loose monetary policy maintained between 2013 and 2024 widened the policy divergence with foreign central banks, depressing the yen as spreads on 10-year sovereign debt favored the dollar. The gradual dismantling of those stimulus measures initiated in 2024, set alongside rate cuts by global peers, has begun compressing that yield gap.
While the yen traditionally attracts flows as a safe-haven asset during phases of international instability, broader financial markets reflect heightened turbulence. Diminishing expectations for a diplomatic resolution between the United States and Iran have underpinned crude oil prices, reinforcing inflation worries and bolstering expectations for an October interest rate hike by the Federal Reserve. Consequently, the Australian Dollar softened by 0.10 percent against the greenback to 0.7016 ahead of the Reserve Bank of Australia's policy meeting. Concurrently, spot gold slipped toward 4,125 dollars per ounce during early Asian trade under pressure from firmer Treasury yields, while diesel prices in the United Kingdom reached fresh records amid escalating operational costs.