














The persistent advance of the US Dollar across international currency markets is facing significant resistance following recent employment indicators. While macroeconomic evaluations describe the broader American labor landscape as steady, neither overheating nor deteriorating sharply, softer payroll metrics have exerted moderate downward pressure on the currency. Pricing for aggressive policy tightening by the Federal Reserve appears to have reached its crest, leading market participants to anticipate an easing in near-term interest rate hike expectations across both the United States and Europe. Consequently, institutional positioning reflects stronger conviction in fading greenback rallies rather than chasing new peaks.
Major Currency Pairs React to Shifting Central Bank Trajectories
Profit-taking ahead of pivotal nonfarm payrolls figures prompted the US Dollar to pull back from 17-month highs. In Asian trading on Friday, the Australian Dollar rebounded toward 0.6950 against the greenback (AUD/USD). This rebound gained momentum from revived expectations of an interest rate hike in November, supported by persistent inflation concerns and elevated sovereign bond yields across major international debt markets.
Concurrently, the greenback struggled to generate upward momentum against the Japanese Yen, hovering near 158.00 (USD/JPY). This consolidation moved the pair away from the upper threshold of its weekly range. A hotter-than-projected Tokyo consumer price index report combined with broad weakness in the dollar forced currency traders to recalibrate their exposure ahead of key US economic releases.
European Headwinds and Pressure on the Single Currency
In contrast to other currencies, the Euro slipped to its lowest valuation since May 2025. The EUR/USD cross touched 1.1312 on Wednesday, representing a steep drop from its January high of 1.2082. This extended downward trajectory underscores a difficult combination of persistent dollar strength, geopolitical instability, and ongoing vulnerabilities linked to European reliance on costly energy imports. An unfolding energy crisis and surging bond yields continue to dominate trading activity despite an otherwise quiet macro schedule.
Precious Metals Fluctuations and Cryptocurrency Rebound
In commodities trading, gold was unable to maintain its post-payrolls push above the $4,200 threshold per troy ounce. By the close of the week, the metal retreated toward the $4,180 level. Despite fresh selling across the US Dollar, price action in gold remained largely indecisive as market participants weighed employment data against broader rate expectations.
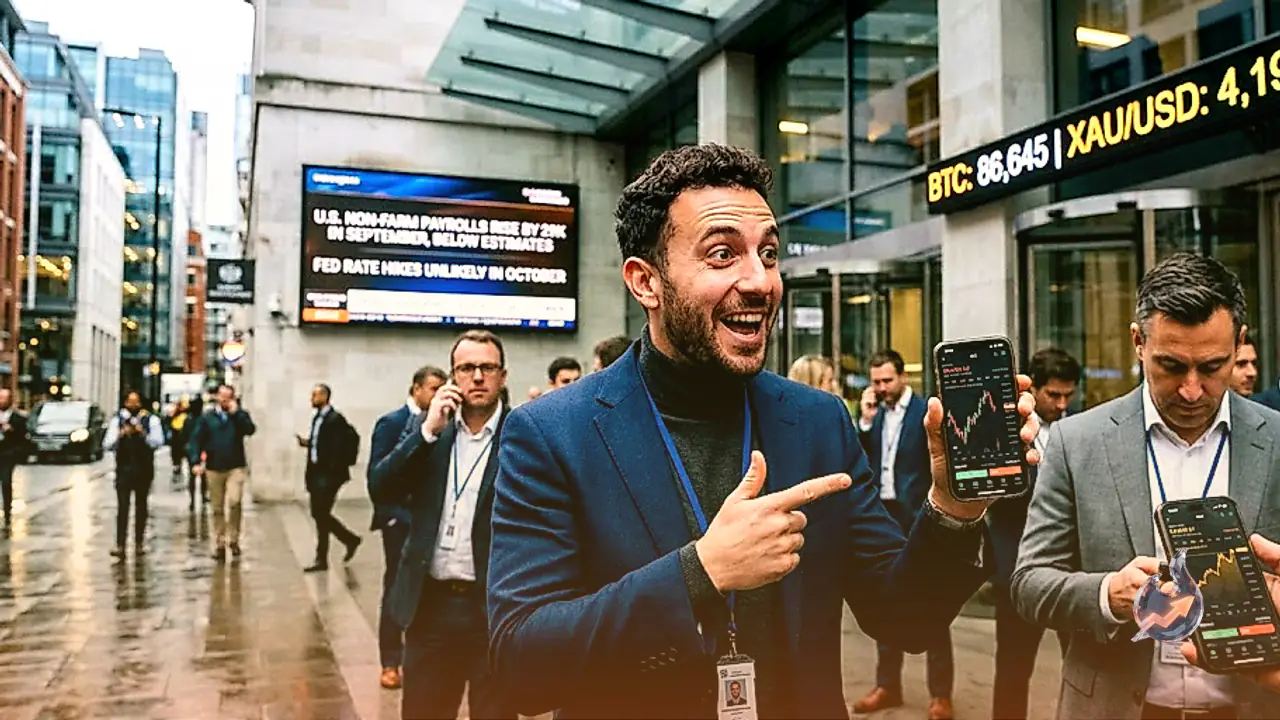
Meanwhile, digital currencies registered a broad-based recovery on Friday. Bitcoin advanced beyond the $86,000 level, improving overall risk appetite across crypto markets. Ethereum reinforced its bullish footing by trading above $2,700, though immediate overhead resistance remains present near $2,800. Ripple held steady, changing hands around $1.54.
Critical Economic Data and Central Bank Minutes Ahead
Market attention is now pivoting toward several major macro catalysts scheduled over the coming days. Following a noticeable decline in expectations for an October interest rate hike, the upcoming publication of Federal Reserve meeting minutes will be scrutinized for clarity on monetary policy. Additionally, investors are monitoring US ISM Services PMI readings and Treasury auctions, alongside Canadian employment figures, Japanese wage growth updates, and policy minutes from the European Central Bank.