
















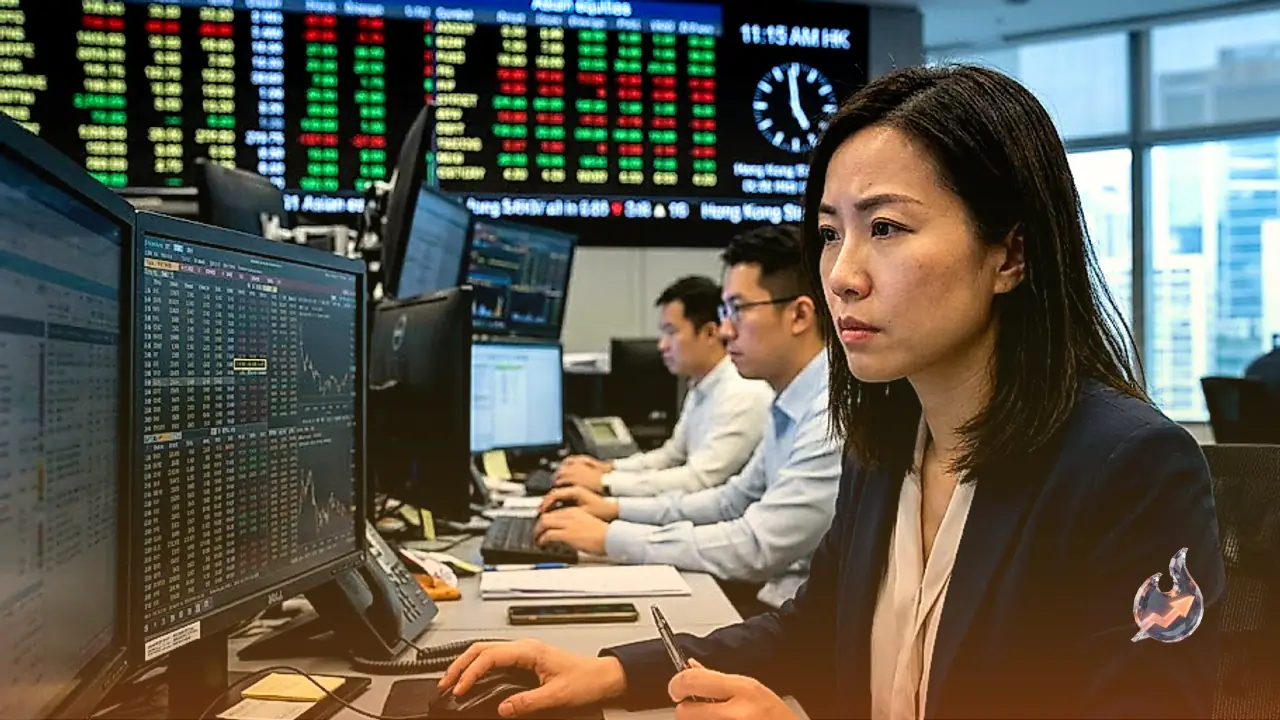

Asian equity markets registered modest advances on Wednesday, though overall trading activity reflected persistent caution as investors awaited the critical monetary policy decision from the US Federal Reserve. Broader sentiment across regional trading floors remained constrained by inflation risks originating in the energy complex and the likelihood of sustained hawkishness from global monetary authorities. At the same time, mounting geopolitical frictions continued to place a firm ceiling on broader market optimism.
Crude oil prices had already escalated on Tuesday to reach their highest mark since May 20, driven by escalating concerns regarding potential supply interruptions across the Middle East. Elevated energy expenses threaten to pass directly into wholesale and retail inflation metrics around the globe, creating conditions that could force central banks to lean toward more aggressive monetary policy settings. Compounding these inflationary worries, an expansion in public and corporate borrowing fueled a broad retreat in debt markets, driving the benchmark 10-year US Treasury bond yield above the 5% threshold for the first time since 2023, marking its highest reading since 2007.
Regional Economic Weight and Key Asian Stock Benchmarks
Asia serves as a primary engine of the global economy, generating roughly 70% of worldwide growth and providing a home to several leading stock market benchmarks. Across the developed markets within the region, Japan's Nikkei, which tracks 225 listed corporations on the Tokyo Stock Exchange, and South Korea's Kospi represent key bellwethers. The Chinese market features three prominent barometers: the Hang Seng in Hong Kong, alongside mainland China's Shanghai Composite and Shenzhen Composite. Concurrently, Indian equity markets are commanding elevated international attention as a premier emerging economy, drawing sustained capital allocations toward companies listed on the Sensex and Nifty indices.
The structural composition of Asia's primary economies displays considerable diversity, with distinct industry sectors driving individual markets. Technology enterprises occupy a dominant role within equity gauges across Japan, South Korea, and increasingly mainland China. In contrast, financial services form the core of exchanges in Hong Kong and Singapore, which serve as foundational international financial hubs. Industrial manufacturing remains a critical pillar in both China and Japan, characterized by heavy concentrations in automotive manufacturing and consumer electronics. Furthermore, the expanding middle-class demographics across China and India are propelling strong commercial prominence for retail and e-commerce companies.
Fundamental Catalysts Behind Regional Market Valuations
A multiplicity of elements governs the trajectory of Asian stock benchmarks, with the cumulative financial outcomes disclosed in quarterly and annual corporate earnings standing out as the foremost determinant. Individual domestic macroeconomic fundamentals, central bank rate determinations, and sovereign fiscal policies also exert direct influence over equity performance. On a structural level, conditions surrounding political stability, the pace of technological development, and the institutional integrity of the rule of law can alter investment appetites. International linkages remain equally decisive, with Asian markets regularly taking directional guidance from overnight momentum on Wall Street. Finally, broad risk appetite across asset classes plays a defining role, given that equities represent a higher-risk category relative to fixed-income assets.
While equity investments carry inherent operational and market risks, allocating capital to Asian equities introduces specific structural dynamics unique to the region. The political landscape across Asia encompasses an expansive spectrum spanning established democratic systems to authoritarian governance, resulting in stark differences in political stability, public disclosure standards, the rule of law, and corporate governance rigor. Cross-border frictions, including trade confrontations, territorial disputes, and natural disasters, routinely inject acute volatility into equity pricing. Currency movements represent another pivotal factor for corporate valuations, especially within export-focused economies that encounter headwinds from domestic currency appreciation while capitalizing on competitive pricing gains when local currencies depreciate.
Foreign Exchange, Commodity, and Fixed-Income Dynamics
Within currency trading, AUD/USD extended its downward trajectory for a third consecutive session, defending the 0.7100 handle while hovering near a monthly low during Wednesday's Asian hours. The US Dollar held steady near a two-week peak, buoyed by multi-year highs in Treasury yields that reflect anticipated Federal Reserve policy firming alongside oil-induced inflation worries. Concurrently, rising tensions in the Middle East bolstered safe-haven allocations toward the greenback while sapping enthusiasm for the risk-correlated Australian Dollar.
In dollar-yen trading, USD/JPY advanced to a fresh one-week peak above 155.00 during the Asian session on Wednesday, supported by broad-based US Dollar demand. The combination of oil-linked inflation pressures and projected Fed rate hikes continued to sustain upward momentum in US Treasury yields, while escalating US-Iran frictions reinforced the reserve currency appeal of the dollar. The currency pair nonetheless held below the mid-155.00 zone, as participants exercised restraint before the conclusion of the Federal Reserve meeting later in the day and the start of the Bank of Japan's policy gathering on Thursday.
Gold undertook another push above $4,300 early Wednesday, mirroring the modest recovery seen during Tuesday's Asian hours. The precious metal's next directional trajectory rests heavily on the Federal Reserve's monetary policy outcome and subsequent guidance delivered later in the session. In digital asset markets, Ethereum fell to $2,400 on Tuesday following the lack of advancement for the Clarity Act in the US Senate. Despite this regulatory setback and widespread market expectations of an interest rate increase at the upcoming Federal Reserve meeting, the prominent cryptocurrency maintained fresh capital inflows, with buying activity consistently exceeding sell-side volumes in recent trading sessions.
In Europe, the United Kingdom Office for National Statistics is scheduled to release the August Consumer Price Index report on Wednesday at 06:00 GMT. This inflation reading could spark substantial volatility across British Pound pairs, as it arrives just one day ahead of the Bank of England's monetary policy determination. Meanwhile, Japan's era of ultra-low interest rates, which provided trillions of dollars in global investment financing for more than a decade and established the Japanese Yen as a premier low-cost funding mechanism worldwide, faces a potential transition. With the Bank of Japan anticipated to tighten policy once more this week, the yen's long-standing status as a global low-rate outlier is moving into an evolving regulatory landscape.