














West Texas Intermediate crude retreated below the $91.00 per barrel threshold on Friday, tipping into negative territory on the weekly performance chart. The retreat came as reports indicated a substantial rebound in oil shipments moving out of Gulf nations during September, an improvement that provided relief to energy markets that had been pricing in severe supply bottlenecks. However, downward momentum remained constrained as fresh military reinforcements dispatched by the United States to the Middle East underscored persistent geopolitical risks in the region.
Rebounding Export Volumes Ease Supply Anxieties
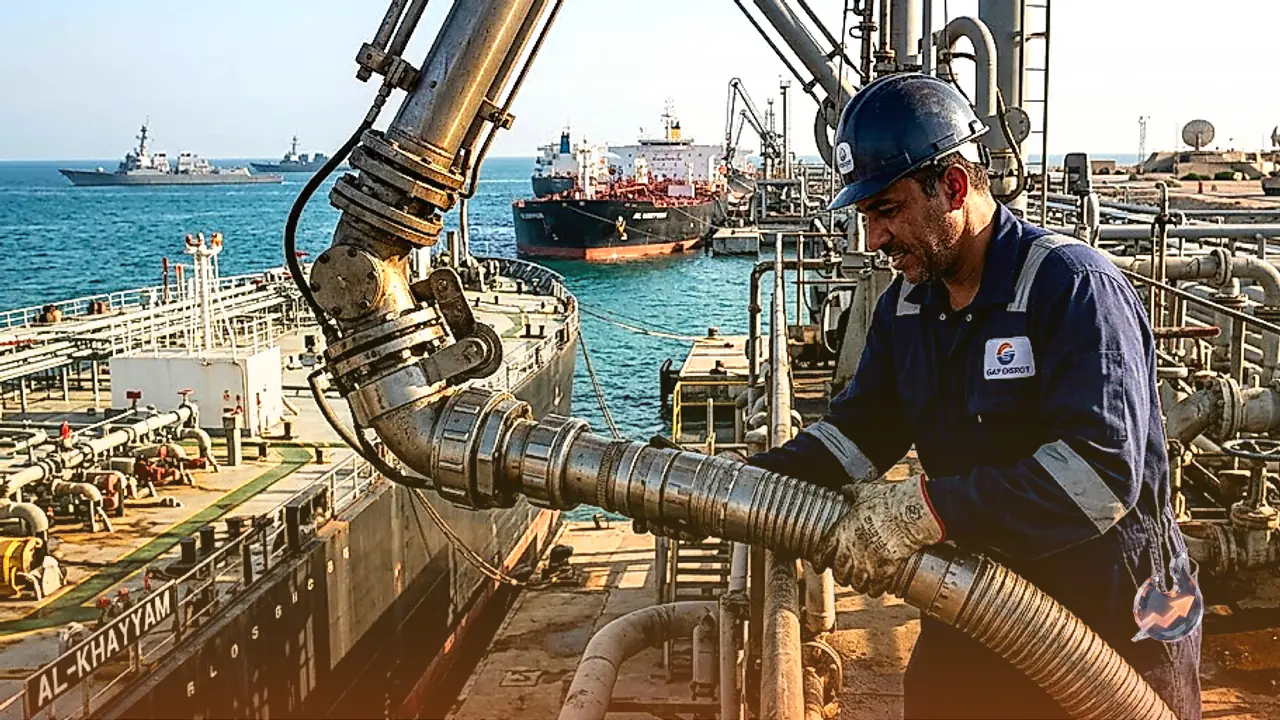
Market sentiment shifted following an assessment released on Thursday by JP Morgan, which showed that crude flows emerging from Middle Eastern producers averaged 17.7 barrels per day across September. This figure represents approximately 98 percent of the shipment volumes recorded prior to the outbreak of regional hostilities. Additionally, refined fuel exports from the area held an average of 3 million barrels per day over the same monthly timeframe, recovering to roughly 58 percent of pre-conflict supply levels. The evidence of sustained seaborne trade helped calm nervous buyers who had bid prices higher on fears of prolonged physical shortages.
Further downward pressure on crude pricing materialized after US President Donald Trump publicly demanded that European partners release their domestic fuel reserves. Trump called upon France and Germany to initiate an immediate release of their strategic diesel inventories, cautioning that failure to act could trigger a ban on exports originating from the United States. This political push introduced expectations of expanded near-term product availability on global markets, taking some of the immediate premium out of prompt contracts.
Military Buildup and Hormuz Attack Establish Price Floor
Despite the supply relief from increased export tallies, crude declines were tightly restricted by mounting friction between Washington and Tehran. The Pentagon moved to deploy a third aircraft carrier strike group alongside roughly 10,000 military personnel to the Middle East, according to statements from US officials reported on Thursday by The Wall Street Journal. Market participants interpreted this notable buildup as a direct warning that active combat operations could escalate or resume across the region in short order.
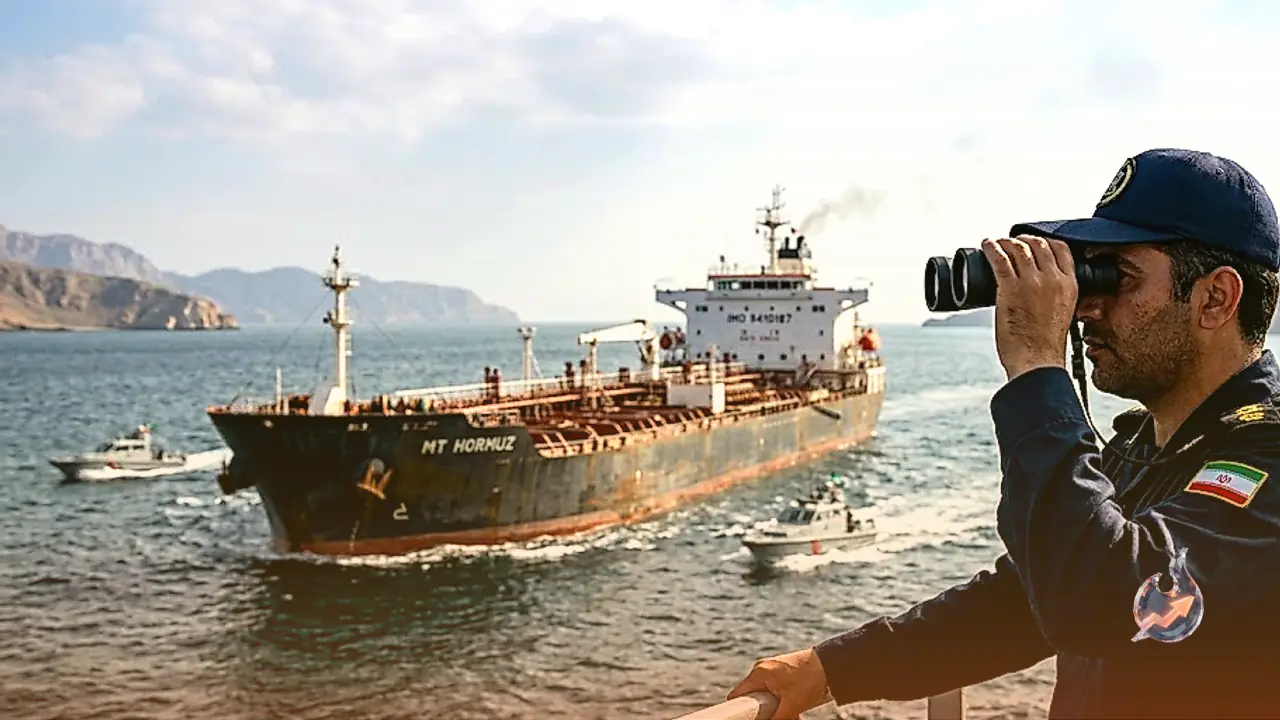
Maritime security alerts added to the underlying market anxiety. The UK Maritime Trade Operations, an arm of the Royal Navy dedicated to overseeing international shipping routes, confirmed that a commercial oil tanker was struck by an unidentified projectile while transiting the Strait of Hormuz on Thursday. Given that the strait represents one of the world's most critical transit passages for petroleum shipments, the incident served as a stark reminder that navigation in the corridor remains highly vulnerable, setting a firm floor under selling pressure and keeping WTI from breaking substantially lower.
Characteristics of the WTI Crude Benchmark
West Texas Intermediate represents one of the premier benchmarks utilized by energy traders globally. Alongside Brent and Dubai Crude, WTI serves as one of three primary reference grades against which global oil transactions are evaluated. The grade is widely characterized as light and sweet, designations that reflect its low density and minimal sulfur content. These intrinsic chemical properties make WTI an exceptionally high-quality crude that requires less intensive processing during the refining stage, yielding substantial fractions of gasoline and distillate fuels.
Sourced entirely within the United States, physical distribution of WTI centers on the storage and pipeline infrastructure at Cushing, Oklahoma. Cushing is recognized industry-wide as The Pipeline Crossroads of the World, connecting major extraction basins with refining complexes. Due to its liquidity and transparent trading on international exchanges, the price of WTI is widely cited across global media as an indicator of broader energy costs.
Key Drivers of Crude Price Movements
The pricing trajectory of WTI crude is governed by standard dynamics of aggregate supply and demand. Accelerated worldwide economic expansion typically drives up industrial throughput, transportation needs, and commercial energy consumption, pulling oil prices higher. Conversely, slowing global output or recessionary trends dampen crude demand, prompting price corrections. Beyond broad macroeconomic health, market equilibria are routinely altered by geopolitical disruptions, armed conflicts, and economic trade sanctions that physically impede production or cut off traditional transport conduits.
Currency valuations, particularly the strength of the US Dollar, also exert a powerful influence over oil valuations. Because international petroleum contracts are priced and settled predominantly in US Dollars, movements in foreign exchange rates directly alter real purchasing power. A depreciating greenback makes crude acquisitions more cost-effective for international buyers using foreign currencies, stimulating broader buying interest. In contrast, a strengthening US Dollar increases the effective cost of crude for foreign consumers, which can curtail consumption and weigh on spot prices.
The Market Influence of OPEC and OPEC+
Production strategies orchestrated by the Organization of the Petroleum Exporting Countries carry immense weight in setting global crude prices. Comprising 12 oil-producing member states, OPEC convenes twice every year to establish coordinated extraction quotas. When the bloc determines that the market is oversupplied and chooses to constrain quotas, the resulting reduction in available barrels drives crude values upward. When the cartel elects to open taps and expand aggregate output, the market faces looser supplies, leading to downward price adjustments.
The cartel's sphere of influence expanded with the formation of OPEC+, a broader collaborative framework that integrates the 12 original member nations with 10 allied non-OPEC oil-producing states. Among these supplemental producers, Russia stands as the most influential counterweight, coordinating closely with core members to shape global balance sheets and manage collective export allocations.
Impact of Weekly Inventory Disclosures
Short-term price action in WTI contracts is frequently dictated by weekly oil storage audits conducted inside the United States. Two separate entities compile these crucial figures: the American Petroleum Institute, an industry trade group, and the Energy Information Administration, an arm of the US government. These disclosures track weekly net adjustments in crude and fuel stockpiles, offering a real-time window into prevailing consumption versus production trends.
Depletions in recorded inventories generally point to strong refiner demand or tightening inputs, prompting upward price reactions. On the other hand, unanticipated stockpile builds reflect slack demand or excess throughput, putting downward pressure on contract prices. The API presents its survey on Tuesday afternoons, followed by the official EIA release on Wednesday mornings. Historically, the two reports record directional conclusions within 1 percent of each other in approximately 75 percent of instances. However, market participants place greater reliance on the EIA data due to its statutory standing as an official governmental statistical agency.