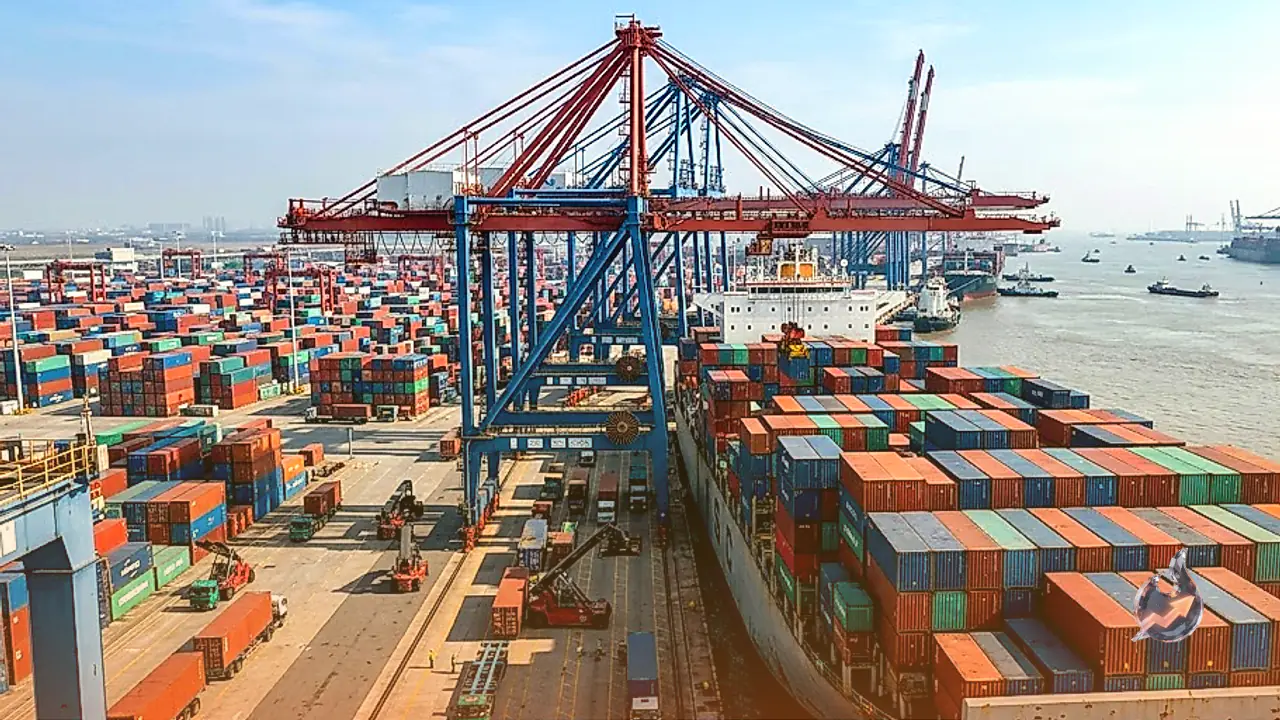















Liquefied natural gas deliveries originating from the Persian Gulf remain severely depressed, running approximately 80% below levels recorded a year earlier. This acute supply squeeze has pushed benchmark European natural gas prices on the TTF exchange to their highest levels since December 2022. As the region moves directly into the high-demand space-heating season, energy markets face intensifying vulnerability, particularly because the recovery observed in regional petroleum flows has failed to replicate across seaborne gas operations.
Energy market participants are adjusting to the reality that shipments from the Persian Gulf may stay largely absent from international trading routes throughout the broader Northern Hemisphere winter. With fewer volumes leaving export docks, European and Asian energy importers have entered a sustained bidding contest to secure flexible spot cargoes. This continuous scramble for replacement volumes is maintaining a firm floor beneath wholesale quotations and keeping regional pricing exposed to sudden upward shocks.
Depleted European Storage and Germany's Procurement Mandate
Inventory levels across underground gas facilities in Europe continue to generate concern among energy planners. Aggregated European storage is currently sitting just beneath 75% of full capacity, trailing significantly behind the historical five-year seasonal norm of 89%. This shortfall has compelled public authorities to intervene directly into commercial markets to reinforce supply security ahead of deep winter temperatures.
In response to these thin inventory reserves, the German federal government instructed state-owned utility SEFE to source and inject an additional 8TWh of natural gas into domestic storage by 15 December. This non-discretionary procurement directive introduces involuntary demand into an already constrained physical market. By requiring sizable purchases on a firm deadline, regulatory mandates have added a reliable layer of structural support beneath gas futures.
Weather Uncertainty and Revised Winter Price Trajectories
Because an immediate rebound in Persian Gulf tanker dispatches appears improbable, atmospheric conditions across Europe will serve as the primary variable determining consumption velocity this season. Forecasters note that the ongoing El Niño phenomenon could generate milder-than-normal winter temperatures across parts of the continent, offering tangible consumption relief. Nevertheless, historical meteorological correlations remain inconsistent, meaning El Niño offers no dependable guarantee against prolonged cold spells.
Reflecting the difficult inventory baseline and persistent maritime supply deficits, projections for the TTF benchmark across the 26/27 winter have been upgraded to average EUR73/MWh, advancing from the prior projection of EUR65/MWh. Trading is expected to remain intensely volatile throughout this window due to the constrained buffer in physical storage. A steep sell-off is anticipated from 2Q27 onward, supported by normalising shipments from the Persian Gulf alongside expanding liquefaction and export capacity in the United States.
Cross-Asset Reaction Across Foreign Exchange and Sovereign Debt
Tension in primary commodities coincided with widespread adjustments across international macro assets. In currency markets, AUD/USD hovered near 0.6950 following disappointing employment metrics from Australia, deepening a retracement from its monthly peak to touch a fresh weekly trough during Thursday's Asian trading session. Softening United States government bond yields pulled the US Dollar back from its April 2025 high, which had been set following hotter-than-expected US consumer inflation data, softening downside momentum for the Australian currency.
Similarly, USD/JPY retreated from a three-week peak, encountering persistent selling pressure that pulled spot rates below 158.00 during Thursday's Asian session. Market participants maintained high vigilance over possible direct intervention by Japanese monetary authorities to stabilize the Yen. Concurrently, US yields pulled lower on chatter regarding Chinese sovereign bond purchases, reversing the post-CPI dollar advance and intensifying downward pressure on the currency pair.
Gold Strength, Bullish Crypto Signals, and the UK Fiscal Backdrop
Precious metals captured robust defensive capital on Thursday as equity retreats caused by growing nervousness around artificial intelligence capital expenditure triggered lower Treasury yields. With the greenback retreating from its yearly zenith, spot gold (XAU/USD) climbed roughly 1.21% on the session to change hands around $4,155 per ounce.
Sentiment within digital asset ecosystems has also maintained an optimistic tone. Key metrics tracking Bitcoin, Ethereum, Solana, BNB, and XRP reveal that market sentiment has remained bullish since July. The recovery trajectory across the five leading tokens proved noticeably swifter and sturdier than rebounds observed across the 2022-2023 market cycle. In the United Kingdom, financial markets are approaching the Chancellor's inaugural budget with less than 2 weeks to go under unusually constructive conditions. Gilt yields have benefited from rallying debt prices, the FTSE 100 has emerged as the week's strongest performer among major benchmarks, and the British Pound has found firmer footing against the US Dollar.