













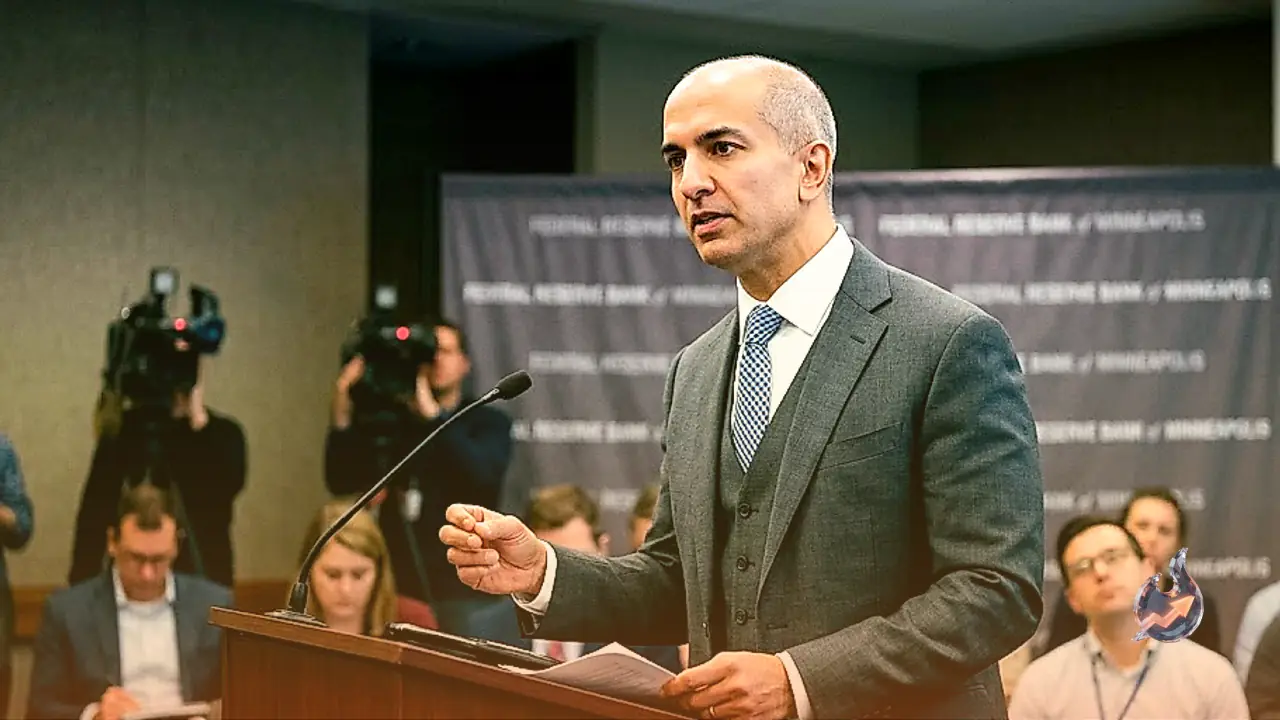

Fresh assessments from Federal Reserve policymaker Kashkari have brought renewed attention to the trajectory of United States borrowing costs. Reaffirming a cautious stance, he noted that his projections from September continue to penciled in an additional interest rate increase during the current year, alongside another adjustment in 2027. Such a path would steer the federal funds rate toward a band of 4.25% to 4.50%, underscoring that policymakers have not closed the door on further monetary firming if conditions warrant.
Addressing the upcoming October meeting directly, Kashkari indicated that he does not hold an entrenched viewpoint regarding an immediate rate hike and remains receptive to adjusting the pace of monetary tightening. In his evaluation of incoming numbers, current policy settings do not appear to be exerting substantial restraint across the broader economy. Recent data shows that overall financial conditions have yet to experience meaningful tightening, while economic activity has consistently beaten projections since the central bank met in September.
Inflation Pressures and the Federal Reserve's Policy Arsenal
On the consumer price front, Kashkari expressed guarded confidence that elevated inflation will eventually moderate, though unexpected shocks persist in disrupting progress. The central bank's rate move in September served as a clear signal that authorities are determined to tackle rising living costs. Financial markets have taken note that Fed Chairman Warsh intends to act decisively to damp down inflationary momentum. If the broader economy maintains its resilient momentum, borrowing costs might need to climb higher than currently projected.
While temporary supply-side disturbances are anticipated to resolve over time, higher rates serve primarily to anchor broader price expectations across businesses and households. Market-derived expectations for inflation continue to hover around the Federal Reserve's target of 2%. Examining the health of the financial apparatus, Kashkari confirmed that he detects no emerging signs of systemic instability, emphasizing that the US Treasury debt market continues to function smoothly even as yields push higher.
Foreign Exchange Movements and Greenback Strength
The currency landscape continues to reflect broad support for the greenback, with the US Dollar displaying its firmest performance against the Euro. Interbank foreign exchange heat maps indicate steady preference for the currency across major trading desks. When market participants track bilateral exchange movements, assessing the Dollar as the base currency against quoted counterparts like the Japanese Yen illustrates the ongoing strength driven by elevated yields.
In Asian market action, the Australian Dollar consolidated near a two-month trough against the greenback, hovering around the mid-0.6900 territory. Although softer US personal consumption expenditures figures somewhat pared expectations for an October interest rate increase, lingering inflation concerns tied to crude oil kept Treasury yields buoyant. Simultaneously, trade data from Australia revealed a sharp contraction in its August trade surplus down to AUD495 million, though the release exerted limited influence on the AUD/USD pair.
Yen Pressure and Divergent Safe-Haven Flows
The US Dollar kept the Japanese Yen pinned near the top of its weekly corridor, trading above 158.00 during Thursday's Asian hours. Despite softer US PCE numbers, the persistent risk of energy-driven inflation has sustained US bond yields near multi-year peaks. Geopolitical friction between Washington and Tehran has simultaneously reinforced safe-haven bids for the dollar. This broad-based dollar demand effectively neutralized hawkish bets on Bank of Japan policy shifts as well as speculation regarding official Japanese market intervention.
Meanwhile, bullion failed to establish a distinct trend, holding under the significant threshold of $4,200 per troy ounce. Gold experienced choppy trading conditions as the upward push in the US Dollar counterbalanced demand stemming from ongoing friction across the Middle East, leaving traders awaiting fresh catalysts.
Cryptocurrency Volatility Under Macro Tightening
Digital currency markets have remained pinned under broader macroeconomic constraints. Bitcoin traded largely confined within a consolidation band, encountering firm floor support at $82,500 and facing technical resistance near $85,000. Ethereum also contended with selling pressure, slipping beneath $2,700 while leaning on immediate support around $2,600. Ripple likewise lost ground, breaking below the key $1.50 threshold.
Market consensus regarding upcoming Federal Reserve decisions has undergone notable fluctuations. Just a week prior, investors viewed an interest rate increase in October as the most probable scenario. However, recent softer inflation prints and measured rhetoric from central bankers have shifted consensus toward an imminent policy pause, keeping risk assets in a state of watchful consolidation.
How the Federal Reserve Governs Monetary Conditions
The Federal Reserve holds sole statutory responsibility for setting monetary policy across the United States. Its framework is guided by a dual mandate granted by law: safeguarding price stability and fostering conditions for maximum sustainable employment. The primary mechanism utilized to pursue these mandates is the target range for short-term policy interest rates. When inflation outpaces the desired 2% target, the central bank raises interest rates, lifting the cost of credit across mortgages, business loans, and consumer borrowing. Higher yields generally bolster the US Dollar by attracting international institutional capital into Dollar-denominated assets. Conversely, when economic growth falters or unemployment climbs excessively, the Fed lowers rates to stimulate economic activity, which tend to depress the Dollar.
Monetary decisions are made by the Federal Open Market Committee during eight scheduled gatherings throughout the calendar year. The committee is formed of twelve voting officials: the seven members of the Board of Governors, the head of the Federal Reserve Bank of New York, and four presidents chosen on a one-year rotational system from the remaining eleven regional reserve banks.
Quantitative Easing Versus Quantitative Tightening
During severe financial dislocations, the Federal Reserve can deploy Quantitative Easing (QE) to restore liquidity. This emergency mechanism injects credit directly into frozen financial markets by creating new central bank reserves to purchase high-rated securities from financial institutions. Deployed extensively in the wake of the 2008 global financial crisis, quantitative easing tends to weaken the exchange value of the US Dollar as monetary supply expands.
Conversely, Quantitative Tightening (QT) unwinds this balance sheet expansion. Under QT, the Federal Reserve ceases secondary market purchases and allows maturing debt instruments to roll off without reinvesting the principal proceeds into fresh issuance. This process drains excess liquidity from the commercial banking sector and traditionally serves to support the purchasing power and foreign exchange value of the greenback.