













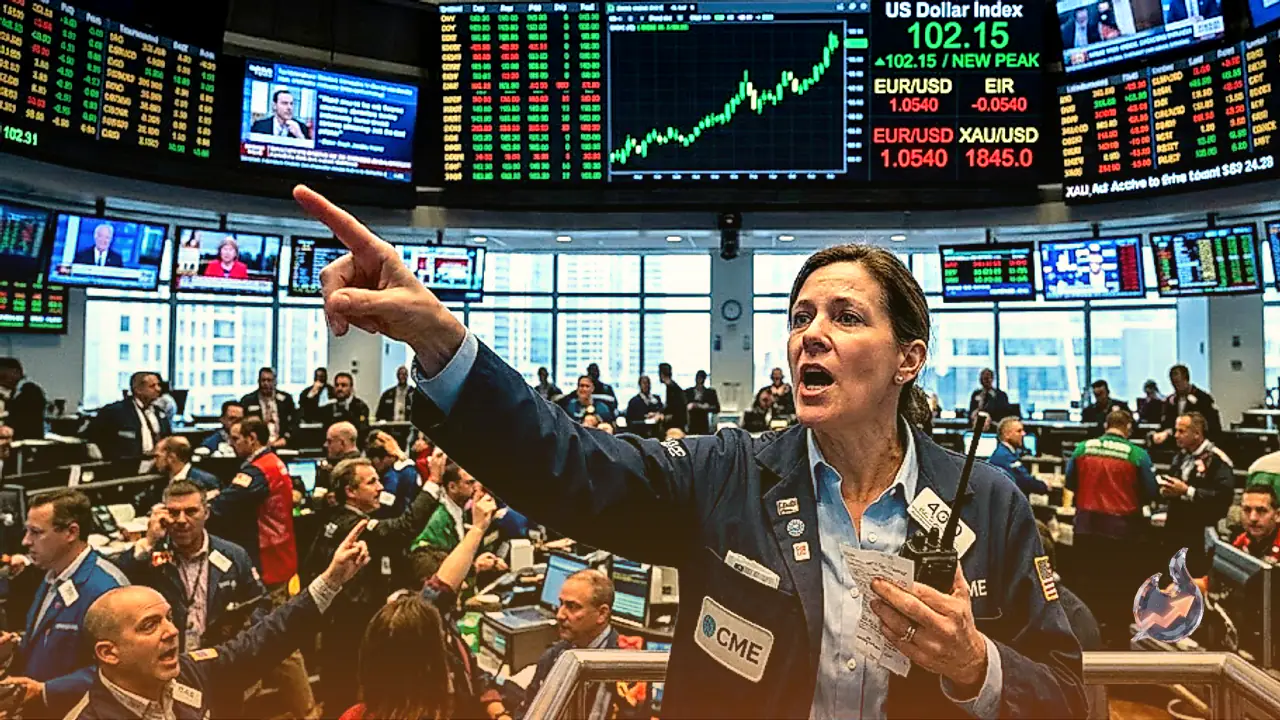

A broad-based rally lifted the US Dollar on Thursday, driving the greenback to levels unseen since early April 2025 as currency sentiment turned sharply positive. Escalating geopolitical uncertainty, an intensifying standoff between the US and Iran, and renewed fiscal worries regarding the French economy combined to reinforce the currency's safe-haven appeal. Against this backdrop, the US Dollar Index broke cleanly above the critical 102.00 benchmark, clinching an 18-month high as global traders positioned ahead of decisive macroeconomic indicators due at the close of the week, most notably the Non-Farm Payrolls, the official unemployment rate, and factory orders.
Major Currencies Retreat Under Broad Greenback Strength
The dollar's upward trajectory delivered widespread losses across rival currencies. The British Pound quickly relinquished the prior day's recovery, sinking below the 1.3200 threshold to plumb fresh four-month lows against the dollar. With the Bank of England's Decision Maker Panel survey serving as the lone scheduled UK data release, sterling traders found little domestic counterweight to offset the prevailing dollar dominance.
Down under, the Australian Dollar displayed similar weakness, consolidating near a two-month nadir around the mid-0.6900s during Thursday's Asian trading hours. Fresh economic figures revealed that Australia's trade surplus narrowed sharply in August to AUD495M. While the release had a limited immediate reaction on the AUD/USD pair, broader risk dynamics kept the Aussie subdued. Recent US Personal Consumption Expenditures price data dampened expectations of an October interest rate hike by the Federal Reserve, but ongoing worries that rising crude oil prices will sustain stubborn inflation kept long-term US Treasury yields elevated, preserving an attractive yield advantage for the dollar.
Yen Fluctuates Near 158.00 as Oil Eyes $93 Mark
In Asian trading, USD/JPY breached the 158.00 ceiling, touching the top boundary of its weekly channel. Even though the pair could not permanently hold ground above that barrier and subsequently slipped toward the low 157.00s, it preserved solid net gains on the day. The strength of the greenback has continually overridden hawkish expectations surrounding the Bank of Japan, as well as lingering risks of direct foreign exchange intervention by Tokyo authorities. Market participants are now awaiting a batch of domestic Japanese data, including the Tokyo Consumer Price Index, the national unemployment rate, and the monetary base, to gauge whether the central bank will step in.
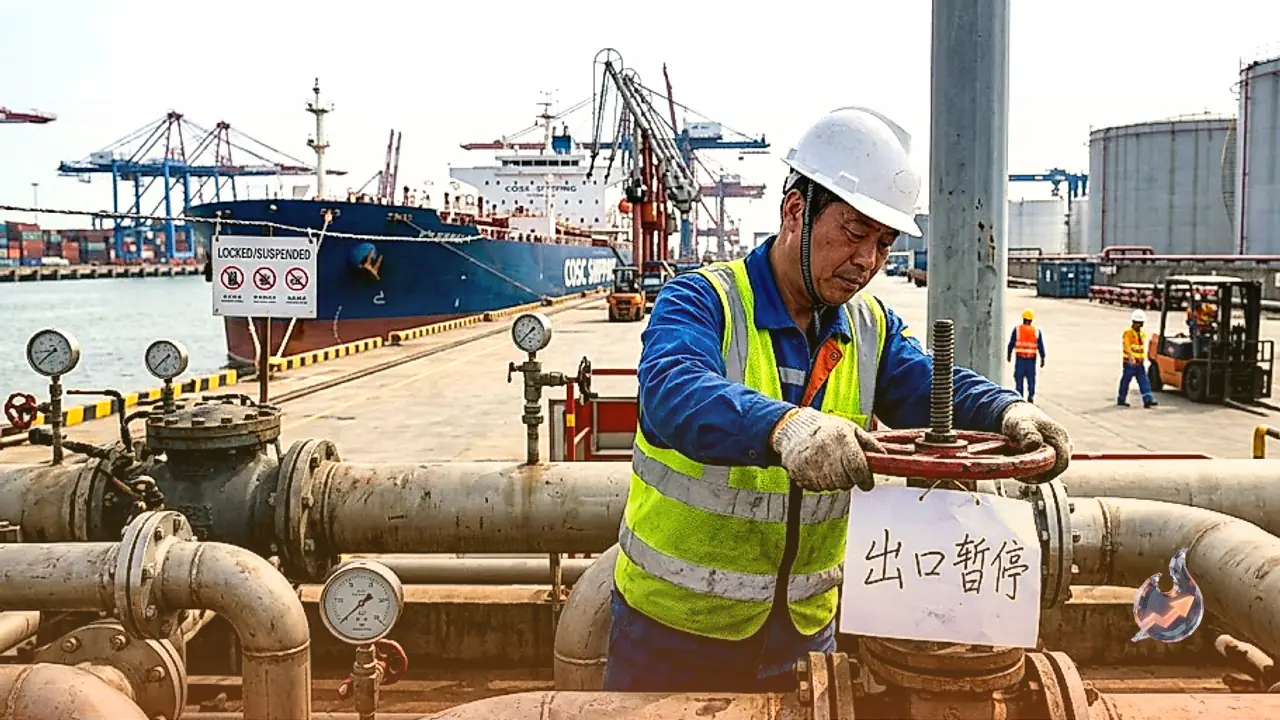
Concurrently, energy commodities registered fresh gains, directly feeding into broader inflation worries. Front-month WTI crude oil futures added to Wednesday's advance, making a determined run toward the $93.00 per barrel mark. This surge in oil prices followed Beijing's move to suspend outbound shipments of refined oil products, immediately reawakening global supply anxieties and compounding the geopolitical risk premium already embedded across the energy complex.
Gold Hesitates Below $4,200 as Cryptocurrencies Soften
Precious metals experienced choppy trading conditions throughout Thursday. Gold struggled to establish directional clarity, remaining capped beneath the key $4,200 per troy ounce threshold. The ongoing escalation in the Middle East provided steady defensive support to the yellow metal, but those gains were consistently neutralized by the dollar's multi-month highs and firm bond yields. At the same time, bullion investors continued to evaluate the Federal Reserve's realistic rate trajectory following the latest batch of slightly softer inflation readings.
Digital asset markets faced comparable headwinds. Bitcoin remained confined to a tight band, oscillating between foundational support at $82,500 and firm resistance at $85,000. Ethereum also stayed under noticeable selling pressure, unable to reclaim ground above $2,700 while leaning directly on initial support near $2,600. Meanwhile, Ripple fell through the pivotal $1.50 psychological level, reflecting a broader pullback across speculative risk assets amid elevated borrowing yields and greenback strength.
Shifting Federal Reserve Expectations Steer Global Sentiment
Market sentiment regarding upcoming monetary policy has witnessed a swift transformation. Merely a week prior, financial markets were actively pricing in an October interest rate hike from the Federal Reserve as the most probable baseline. That outlook has quickly dissolved in favor of a rate pause, spurred by cooler price indicators and cautious public commentary from central bank officials. With the Fed's Logan scheduled to speak, and factory orders arriving alongside the crucial employment report, market participants are bracing for heightened volatility as they seek final confirmation on whether the US economy is headed for a higher-for-longer regime or an extended policy standstill.