













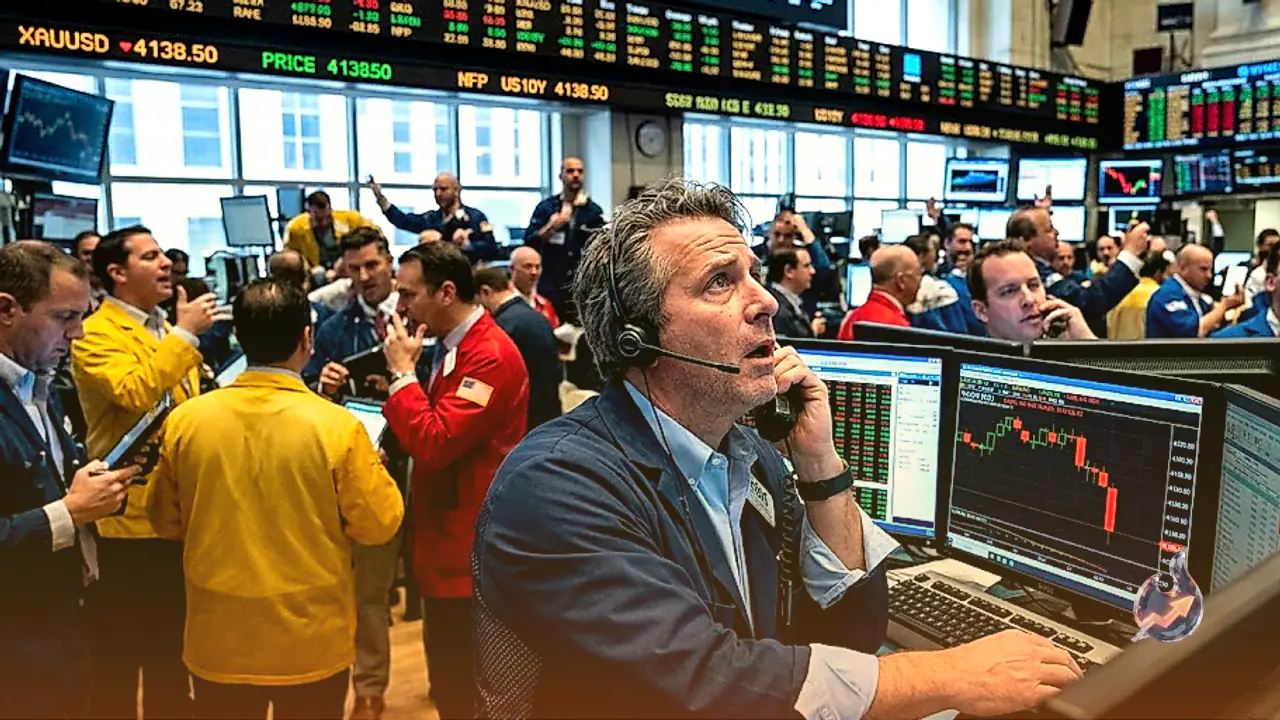

Gold faced renewed downward momentum on Friday, failing to sustain an advance above the critical $4,200 per troy ounce threshold despite an overwhelmingly weak reading in the headline United States labor data. Spot gold slid nearly 1% throughout the trading session as a continuous advance in benchmark US Treasury yields overshadowed the broader weakness in macroeconomic employment figures. The XAU/USD pair tumbled toward $4,138 after reaching a session peak of $4,227, illustrating persistent distribution near psychological resistance as bond market dynamics dictated capital allocation across safe-haven instruments.
Disappointing Payroll Additions and Upward Creep in Joblessness
The September United States Nonfarm Payrolls report delivered an unexpected blow to labor market expectations, recording the addition of merely 29,000 positions against widespread consensus projections of 90,000 jobs. Adding to the negative revision trend, August payroll additions were downgraded to 133,000, underscoring sequential deceleration in workforce hiring across primary sectors. Consequently, the headline US Unemployment Rate ticked up from 4.1% to 4.2%. While this reading sits one-tenth of a percentage point above the Federal Reserve's medium-term baseline projections for 2026 and 2027, labor economists observed that the modest uptick was partially cushioned by a higher overall labor force participation rate.
Federal Reserve Trajectory and Persistent Dollar Headwinds
Implied interest rate probabilities reflected on Prime Terminal point to an overwhelming conviction that the Federal Open Market Committee will leave the target policy rate unchanged at its upcoming October 28 policy gathering, with the likelihood of a hold standing at approximately 77%. Looking toward the final scheduled meeting on December 16, interest rate futures indicate an 88% probability that policymakers will maintain existing rate corridors. Interestingly, bullion was unable to stage a sustained rebound even as the Greenback experienced broad-based liquidations. The US Dollar Index (DXY), which gauges the dollar's performance relative to a basket of six major trading peers, fell 0.14% to 101.89. The inability of gold to capitalize on dollar soft spots highlights the overriding influence of the 10-year Treasury yield, which held firm near 5.29%.
Technical Indicators Point to Deepening Bearish Grip
The inability of buyers to confirm a daily closing print above the $4,200 barrier following the intraday spike to $4,227 has significantly amplified technical vulnerability for the precious metal. Momentum metrics depict a market controlled by institutional sellers, with the Relative Strength Index (RSI) holding decisively beneath the neutral 50-mark threshold. Market participants are monitoring the initial horizontal support shelf situated at the $4,100 landmark. A decisive breakdown below this foundation would expose the July 29 daily low at $3,996, followed closely by the secondary downside support pocket at the July 17 trough of $3,959. Conversely, buyers face the arduous task of conquering $4,200 on daily closing bases to open an assault on the 100-day Simple Moving Average (SMA), which currently slopes near $4,279. Complementary live tracking indicates that the 14-period RSI sits at 34 with an MACD of -63.26 against a signal line of -38.58, reinforcing prevailing downward momentum.
Sovereign Reserve Allocations and Safe-Haven Utility
Gold maintains an enduring foundational role within the global financial architecture as an unencumbered store of value and premier medium of exchange. Outside of industrial and jewelry applications, bullion commands widespread demand during phases of systemic macroeconomic distress and geopolitical fragmentation. Given that physical gold lacks counterparty insolvency risk and is not bound to sovereign fiscal liabilities, institutional treasuries utilize it extensively to hedge against chronic currency depreciation and persistent inflationary trends. Central banks have solidified their standing as dominant net purchasers in the physical market. World Gold Council figures highlight that central banks acquired an unprecedented 1,136 tonnes of bullion in 2022, commanding an estimated value of $70 billion and establishing the highest annual accumulation figure on historical record. Emerging sovereign institutions, notably across China, India, and Turkey, continue to accelerate their reserve diversification programs to fortify national balance sheets.
Structural Correlations: Dollar, Treasuries, and Equities
The valuation dynamics of precious metals are inherently tethered to the behavior of sovereign debt yields, the US Dollar, and broader investor risk appetites. A depreciating greenback traditionally enhances accessibility for cross-border purchasers pricing bullion in alternative currencies. Similarly, prolonged sell-offs across speculative equities frequently steer capital flows into the physical metal, while aggressive equity rallies siphon liquidity away from defensive holdings. Because gold yields no recurring coupon or dividend distribution, higher borrowing costs and elevated risk-free yields severely penalize allocation models. Consequently, even amid mounting signs of economic stagnation, the yellow metal remains tethered to sovereign fixed-income yields and the relative trajectory of the US Dollar.
Divergent Movements in Foreign Exchange and Digital Assets
Global financial venues reflected notable cross-currents alongside the pullback in bullion. The Australian Dollar gathered firm bids in Friday's Asian trading session, driving the AUD/USD pair toward 0.6950 as foreign exchange desks priced in rising probabilities of a November interest rate adjustment by the Reserve Bank of Australia amid sticky inflation expectations. The USD/JPY pair hovered near 158.00 following robust consumer price figures from Tokyo that tempered dollar demand. In contrast, the common currency faced substantial structural headwinds, with EUR/USD plumbing its lowest level since May 2025 at 1.1312, deeply eroded from its January zenith of 1.2082 due to ongoing energy infrastructure strain and sovereign yield divergence. Meanwhile, alternative speculative markets demonstrated resilience; Bitcoin reclaimed terrain north of $86,000, Ethereum pushed toward $2,700 beneath immediate resistance at $2,800, and Ripple oscillated near $1.54. Global market participants now pivot their focus toward upcoming ISM services data, Federal Reserve meeting minutes, and US sovereign debt auctions.