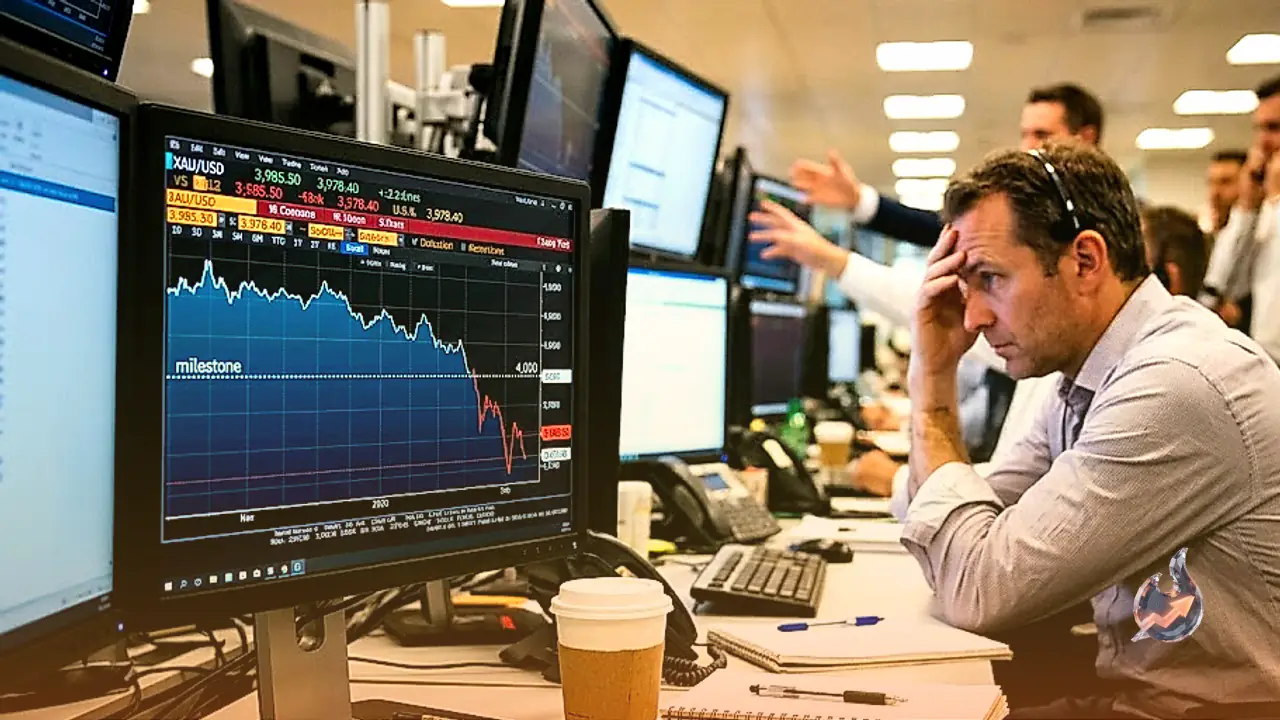
















Bullion markets faced intense selling pressure into the close of the week, driving Gold prices below the critical $3,900 mark to log fresh lows for 2026 despite an initially constructive start to trading. The near-term technical configuration signals an entrenched bearish structure as sellers maintain firm control across key momentum indicators. Market participants now face an eventful stretch marked by major US macroeconomic data releases alongside Tuesday's congressional midterm elections. Live market tracking indicates Gold closed the session at $3,921 per ounce, slipping 2.73% from its prior settlement at $4,031. Over the past 52 weeks, prices have traded between $3,901 and $5,586, with trading volume running at 1.13 times the 20-day moving average.
Federal Reserve Decision and Resilient Macro Data
Midweek momentum was initially shaped by the Federal Reserve, which announced that it left the target range for the federal funds rate unchanged between 3.75% and 4.00%. The decision was not unanimous, as two policymakers cast dissenting votes favoring an immediate 25-basis-point rate hike. During the post-meeting press conference, Fed Chair Kevin Warsh stopped short of confirming an interest rate hike for the December meeting, though he reaffirmed the central bank's steadfast commitment to restoring price stability. The initial market reaction triggered modest softness in the US Dollar, providing room for XAU/USD to generate minor midweek advances.
That brief respite evaporated rapidly on Thursday following heavy macroeconomic releases. The initial estimate published by the US Bureau of Economic Analysis revealed that third-quarter US Gross Domestic Product expanded at an annualized clip of 3.4%. This performance followed the 2.2% pace registered in the second quarter and comfortably exceeded consensus forecasts calling for 3.2% growth. Concurrently, the Bureau of Economic Analysis reported that the Personal Consumption Expenditures Price Index climbed 3.6% in September compared to 3.4% in August. Core PCE inflation, the preferred benchmark utilized by Federal Reserve policymakers, rose to 3.1% over the same stretch, matching projections.
Tech Sector Sell-Off Escalates Downward Pressure
Risk sentiment took another hit as equity markets wobbled under corporate pressure. Shares of Alphabet, Google's parent entity, tumbled nearly 13% on Thursday to reach their lowest valuation since April, dragging down the NASDAQ Composite. In its quarterly filing, the technology giant reported that artificial intelligence search overviews were diminishing digital advertising revenues, while also revealing negative free cash flow totaling approximately $9 billion.
After dropping more than 1% on Thursday and erasing most of its accumulated weekly advance, Gold accelerated its slide on Friday. The breakdown below the key $4,000 threshold, combined with an intensifying retreat in major US tech names, weighed heavily on the yellow metal, culminating in a decline beneath $3,900 to levels not seen since October 2025.
ISM Manufacturing Gauge and Midterm Election Dynamics
Attention now shifts to Monday's release of the Institute for Supply Management Manufacturing Purchasing Managers Index. Barring an unforeseen plunge into contraction territory below the 50 mark, overall market volatility is projected to stay relatively subdued ahead of Tuesday's midterm elections.
Commerzbank analyst Nguyen highlighted that the United States appears to be heading toward a divided government structure, with election outcomes likely confronting the executive branch with an assertive Democratic majority in Congress. The bank observed that Democratic lawmakers would probably seek to limit administrative leeway on high-profile public matters, particularly the ongoing conflict involving Iran that has driven living costs substantially higher, even if wartime executive powers restrict legislative intervention.
Geopolitics, Governance Scenarios, and Bullion Trajectory
Direct correlations between legislative election results and near-term Gold pricing remain challenging to establish. Nevertheless, a divided government could cap appropriations for overseas military engagement, potentially creating conditions for de-escalation across the Middle East. Given that escalating energy costs and their upward pressure on inflation expectations have impeded Gold throughout the hostilities, a divided legislature could offer XAU/USD a firmer base. Conversely, such an outcome might lead President Donald Trump to deploy emergency powers and executive orders to execute policy priorities, where heightened systemic unpredictability could reignite safe-haven allocations into Gold. In contrast, should Republicans retain bicameral control of both the House and Senate—a scenario considered least likely by prediction markets—Gold could encounter a swift negative knee-jerk reaction.
Technical Structure, Moving Averages, and Key Price Levels
Technical readings on the daily time frame highlight sustained selling pressure. While the standard daily Relative Strength Index sits narrowly above 30, live indicators place the 14-period RSI at 29, entering oversold territory. The Moving Average Convergence Divergence indicator reflects persistent weakness, with the MACD line at -74.35 below the signal line at -64.55 and a negative histogram reading of -9.80. The 14-period Average Directional Index stands at 29, confirming an active trend.
Spot prices remain positioned well underneath descending channel parameters and the 20-day Simple Moving Average at $4,100. From an exponential perspective, the 20-day EMA sits at $4,111, the 50-day EMA at $4,211, and the 200-day EMA at $4,415, while the 50-day SMA is at $4,295 and the 200-day SMA stands at $4,519. The established death cross reinforces the primary multi-month downtrend. Bollinger Bands (20, 2) span from $3,967 to $4,265, with current price action testing beneath the lower envelope.
Immediate downside support rests at the $3,900 static boundary, complemented by live technical pivots: the central pivot is located at $3,953, with S1 support at $3,869 and S2 support at $3,816. A sustained breach beneath these levels exposes secondary targets at $3,800 and $3,720. On the recovery side, overcoming the $3,960 to $4,000 zone brings initial resistance at $4,006 (R1) and $4,091 (R2). Above that, the 20-day SMA at $4,100 and the 100-day SMA at $4,220 represent overhead barriers, ahead of $4,300, which marks the 23.6% Fibonacci retracement of the March-to-August downward move. The 14-day Average True Range of 79.83 provides an objective measure of prevailing daily volatility for protective stop positioning.
Currency Crosses and Structural Reserve Purchases
Foreign exchange markets witnessed distinct moves elsewhere. During Asian trading on Friday, AUD/USD advanced toward 0.7035 as higher Australian consumer price index figures reinforced projections for policy tightening by the Reserve Bank of Australia. Concurrently, USD/JPY fell for a third straight session to test near 157.00 before paring losses following the Bank of Japan's scheduled decision to keep policy settings unchanged.
Over long historical horizons, Gold has served as a primary store of value and medium of exchange, retaining safe-haven appeal and functioning as an inflation hedge unencumbered by sovereign liability. Official institutions remain premier participants: central banks accumulated 1,136 tonnes of Gold worth approximately $70 billion in 2022 according to World Gold Council records, representing the largest single-year total on record. Emerging monetary authorities across China, India, and Turkey continue to expand strategic reserve holdings. As Gold typically exhibits an inverse relationship with the US Dollar and Treasury yields, upcoming macroeconomic data points and geopolitical shifts will remain pivotal drivers for upcoming trading cycles.