













Mounting inflationary pressures across the United Kingdom are confronting monetary policymakers with an increasingly urgent challenge. Projections indicate that the headline Consumer Price Index accelerated to an annual pace of 3.4% in September, advancing from the 3.1% reading registered in August. Should the forthcoming official data validate these expectations, consumer price growth will mark its highest reading since December of last year. Soaring energy expenses have begun rippling through the wider domestic economy, driving underlying core prices higher as well. Consequently, financial markets are solidifying expectations that the Bank of England will move to raise its benchmark borrowing costs at its scheduled November meeting.
September Inflation Release and Economic Indicator Suite
The UK Office for National Statistics is scheduled to publish the official September Consumer Price Index report on Wednesday at 06:00 GMT. The inflation release will be accompanied by corresponding data from the Producer Price Index and monthly retail sales figures. Global financial market participants and institutional investors are focusing intently on these numbers to glean clear signals regarding the impending monetary policy trajectory of the Bank of England.
On a month-over-month basis, the consensus among economists anticipates consumer prices climbing 0.3% in September, a moderation compared to the 0.5% advance recorded in August. However, the annual rate continues its upward path toward 3.4%. Core inflation, an underlying measure that excludes volatile energy, food, alcohol, and tobacco prices, is likewise projected to climb to 2.8% from 2.6% in the prior month. This uptick in core consumer costs provides concrete evidence that the energy price shock triggered by ongoing Middle East conflicts has permeated basic goods and everyday consumer services.
Global Energy Spikes and Central Bank Policy Stance
Elevated commodity prices remain the predominant force driving persistent inflationary momentum worldwide. Crude oil benchmarks have rallied more than 10% during October alone, compounding a cumulative advance of nearly 50% since July. Brent crude oil has climbed above $108.00 per barrel, marking five-month peaks. Given deepening geopolitical friction among regional powers, energy markets show few signs of returning to pre-conflict price ranges in the foreseeable future.
This prolonged escalation in energy input costs poses a distinct danger that central banks might fall behind the curve should they hesitate to implement restrictive monetary policy. The Bank of England stands out as one of the few prominent central banking institutions that has refrained from tightening monetary conditions during 2026. While individual officials, including Governor Andrew Bailey, have pointed out the necessity of lifting interest rates to curb stubborn price growth, precise guidance on timing has remained elusive. However, Governor Bailey vocalised distinct frustration regarding persistent above-target inflation during the International Monetary Fund summit in Bangkok last week, consolidating investor conviction that a rate increase is imminent before year-end.
Macroeconomic Resilience Eases Monetary Tightening Hurdles
Recent British macroeconomic indicators have bolstered the case for an immediate policy response. The International Labour Organization unemployment figures released on Tuesday reflected ongoing durability across the domestic workforce, notwithstanding a reduction in vacant positions and a higher-than-expected rise in claimant counts. Furthermore, monthly Gross Domestic Product figures surprised to the upside in August, demonstrating unexpected economic expansion underpinned by robust output across the manufacturing and industrial sectors.
Market analysts at Commerzbank observed that the latest batch of economic statistics provides the Bank of England adequate flexibility to implement an interest rate increase without generating disproportionate drag on broader economic activity. The firm noted that this economic buffer also alleviates pressure on the Chancellor, who remains dedicated to paring down the fiscal deficit. Additional clarity on how the government plans to reconcile fiscal consolidation with cost-of-living relief for energy-burdened households and commercial enterprises is expected upon the formal delivery of the budget later this month.
Foreign Exchange Dynamics and Currency Market Developments
Propelled by robust domestic statistics and elevated expectations of a quarter-point rate adjustment in November, the British Pound has emerged as one of the standout performers across major foreign exchange pairings this week. Market concerns regarding the eventual funding costs of tax-relief initiatives pledged by Prime Minister Andy Burnham's administration have subsided. In parallel developments, the US Dollar has encountered headwinds as investors scale back expectations of consecutive rate increases from the Federal Reserve, while the Euro faces downward pressure amid widespread civil unrest and municipal curfews in Paris.
Across broader currency pairings, AUD/USD maintained an upward trajectory for a fourth consecutive session, trading above 0.7000 during Wednesday's Asian trading hours to touch three-week highs. Hawkish guidance from Reserve Bank of Australia Deputy Governor Andrew Hauser and ongoing inflation considerations have underpinned the Australian currency, though geopolitical developments between the United States and Iran have limited further appreciation. USD/JPY traded within a familiar range near 158.50 as uncertainty regarding the Bank of Japan's rate timeline constrained trading activity. Gold traded near weekly lows below $4,100 per ounce, restrained by high yields, while corporate earnings reports from Netflix, Meta Platforms, and Tesla are poised to direct risk sentiment across global equity markets.
GBP/USD Technical Structure and Pivotal Price Barriers
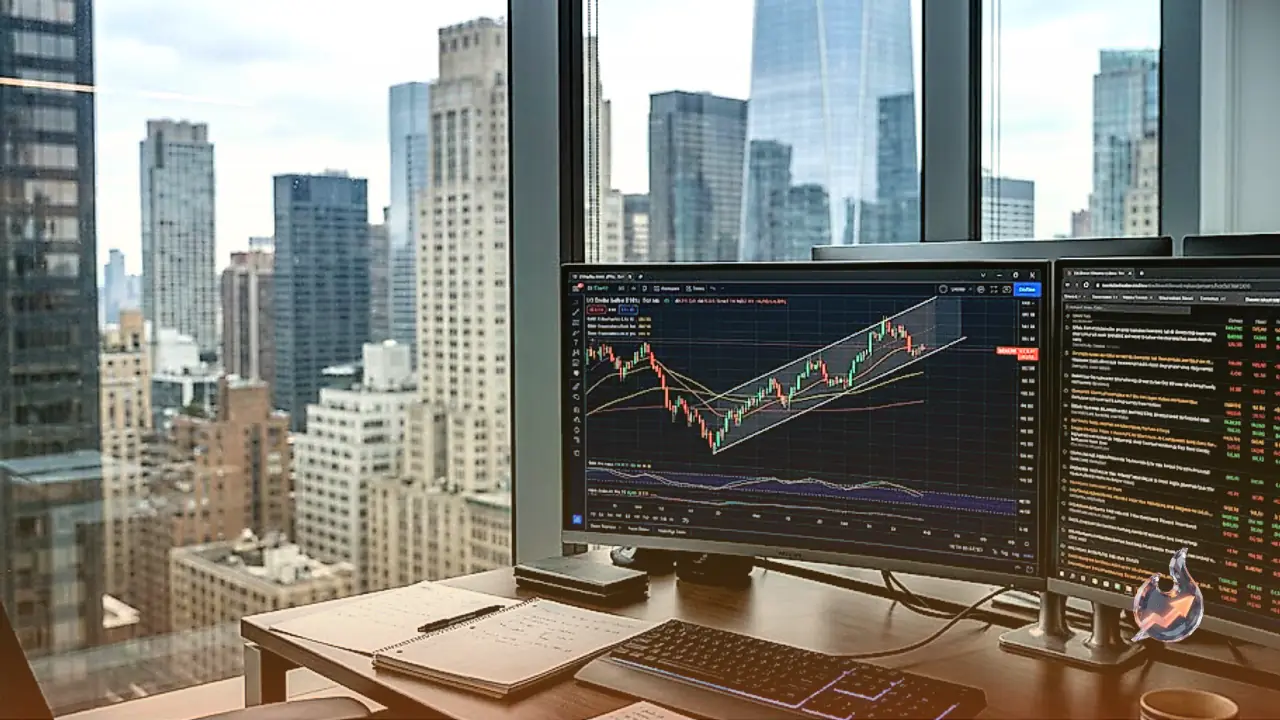
Examining the 4-hour technical chart, GBP/USD exhibits an immediate constructive configuration following a breakout above its late-August downward resistance trendline, which underwent a successful retest on Monday. The 14-period Relative Strength Index remains situated above 60, confirming positive momentum, though a relatively neutral Moving Average Convergence Divergence indicator hovering near zero suggests underlying vulnerability in the prevailing uptrend.
According to live market tracking, GBP/USD trades at 1.34, representing an advance of 0.50% from the prior closing mark of 1.33 within a 52-week trading span of 1.30 to 1.38. Technical metrics indicate a 14-period RSI of 56. The 20-day exponential moving average sits at 1.33, with both the 50-day and 200-day exponential moving averages placed at 1.34. The presence of a death cross where the 50-day EMA tracks below the 200-day EMA reflects a long-term downward trend, yet near-term movement remains firm. Upside resistance is concentrated between Friday's peak of 1.3370 and the September 22 high around 1.3400. A decisive push beyond this barrier brings the 61.8% Fibonacci retracement level at 1.3467 and the previous support boundary at 1.3470 into focus. On the downside, trendline support near 1.3295 shields against selling pressure, with any drop below exposing year-to-date lows near 1.3140.
Foundational Economics of Central Bank Interest Rate Frameworks
Interest rates function as the fundamental mechanism governing borrowing expenses levied by financial institutions and yields delivered to household savers. These commercial rates are benchmarked against the base lending rates determined by national central banks navigating fluctuating macroeconomic cycles. Standard central banking charters mandate maintaining consumer price stability, typically defined as preserving core consumer inflation near an annualized 2% benchmark. When inflation substantially exceeds this boundary, central banks lift base lending rates to cool borrowing and spending, whereas policy easing is deployed during periods of sub-target inflation to stimulate economic expansion.
Elevated domestic interest rates typically bolster a nation's currency by rendering domestic financial assets more attractive to global capital. Conversely, rising interest rate environments generally exert downward pressure on gold prices by raising the opportunity cost of holding non-yielding physical bullion. In the United States, the federal funds rate serves as the foundational overnight interbank lending benchmark set by the Federal Open Market Committee, heavily monitored through the CME FedWatch gauge. In the United Kingdom, the Bank of England's strict 2% headline target makes each monthly inflation release a vital indicator of impending policy adjustments, where stronger inflation often triggers rate hikes and currency appreciation.