














Trading in global foreign exchange markets turned cautious on Tuesday as the US Dollar Index lost momentum after posting modest early gains, easing to trade near 101.80 during European trading hours. The greenback continues to hold ground above its 50-day Exponential Moving Average, preserving a mildly constructive technical framework over the intermediate horizon, yet immediate upward progress remains capped under the nine-day EMA. Currency traders are closely watching the index as it tests the lower trendline boundary of an ascending price channel on the daily timeframe, setting up a decisive juncture between a trend-continuation bounce and a corrective breakdown.
Technical Structure and Key Chart Boundaries
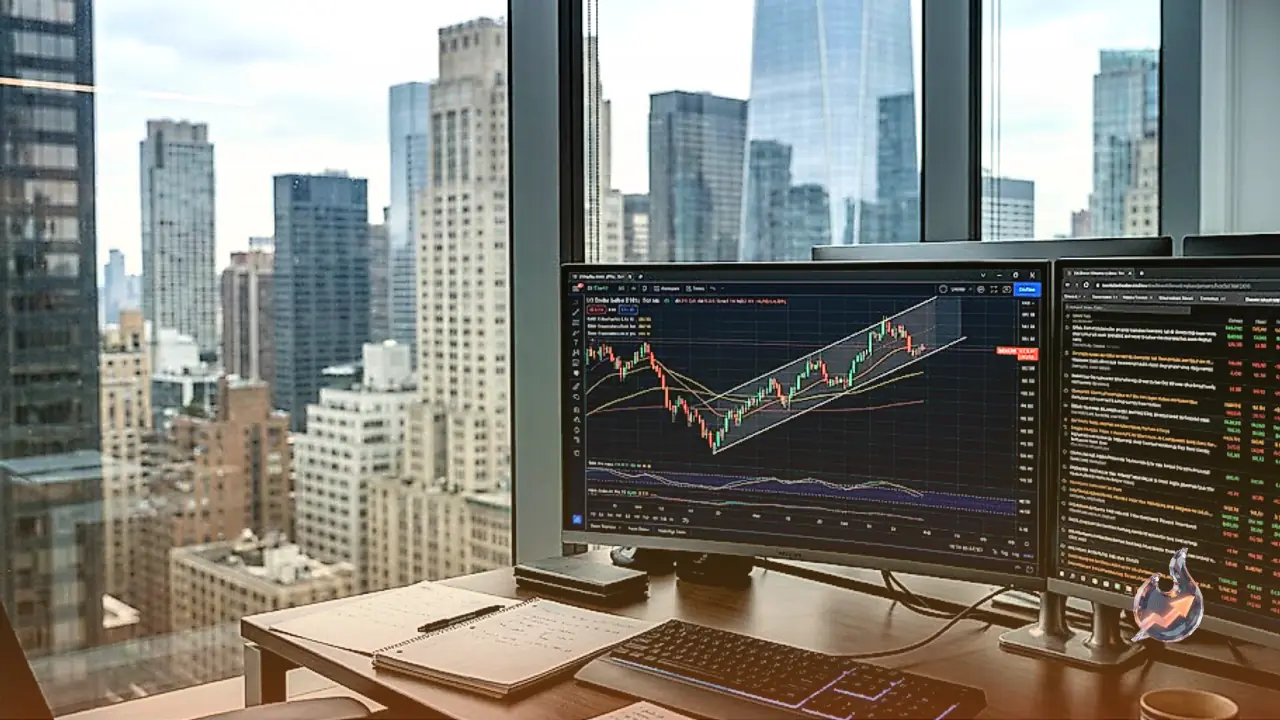
The daily chart indicates that the greenback gauge is actively testing the lower limit of an established ascending channel pattern. A defense of this diagonal boundary would offer buyers an opportunity to stage a bullish rebound and preserve the multi-week upward sequence. Conversely, a sustained violation beneath trendline support would flag the onset of a deeper bearish leg, pulling the index away from recent multi-month highs.
Immediate downside cushioning is located at the channel boundary around 101.70, followed directly by the 50-day EMA at 100.94. Live technical readings show the 20-day EMA positioned at 101.68 and the 50-day EMA at 100.99, while the 200-day EMA sits significantly lower at 99.75. The presence of a golden cross formation, with the 50-day average running comfortably above the 200-day metric, confirms an underlying long-term bullish bias. Should sellers force prices through the primary moving average cushion at 100.94, broader downward pressure would expose the five-month low of 98.56, established on August 20.
On the topside, initial supply is concentrated at the nine-day EMA of 101.98. Clearing this dynamic barrier would improve short-term momentum and encourage market participants to target the 18-month high of 102.94 reached on October 14. An extension beyond that cycle peak would open the door for a test of the ascending wedge upper boundary marked at 103.90. Bollinger Bands across the 20-day timeframe stretch from 101.03 to 102.73 with a median line at 101.88, confirming that current spot quotes remain securely within standard historical dispersion parameters.
Momentum Indicators and Volatility Metrics
Momentum readings paint a picture of steady stabilization rather than overextended enthusiasm. The 14-day Relative Strength Index sits around 55, reflecting balanced underlying sentiment that avoids overbought extremes. This neutral-to-positive RSI posture provides room for additional upside without immediate technical exhaustion, though broader price confirmation remains absent.
Additional technical diagnostics reveal the Moving Average Convergence Divergence line at 0.41 beneath its signal reading of 0.52, generating a slightly negative histogram reading of -0.12. Meanwhile, the 14-day Average Directional Index stands at 41, signaling a strong prevailing trend environment across daily charts. The stochastic oscillator reflects a fast line at 19 against a signal line of 29, hovering near oversold territory. The 14-day Average True Range registers at 0.47 points, providing active market participants with a practical daily volatility buffer for risk management. Intraday pivot calculations place primary equilibrium at 101.79, flanked by immediate resistance marks at 101.81 and 101.84, alongside underlying support levels at 101.76 and 101.74.
Federal Reserve Outlook and Policy Signals
Broader monetary policy dynamics remain the primary driver of dollar valuations across international venues. Readings from the Fed Sentiment Index hover near 127.51, suggesting that broader expectations for monetary tightening are no longer aggressively supportive, thereby limiting room for substantial expansion on rallies.
Recent remarks from Federal Reserve Chair Warsh registered a 5.6/10 rating on the Speechtracker metric, pointing to a milder tone compared to the historical benchmark of 6.1/10. While Warsh offered positive assessments regarding structural expansion and accelerated private investment, his wider narrative was characterized by measured caution. The observation that policymakers remain heavily scarred by the fallout of the global financial crisis indicates an acute awareness of systemic vulnerability, dampening the impact of orthodox inflation warnings ahead of pivotal policy meetings in October and December.
Furthermore, Chair Warsh highlighted artificial intelligence as a primary demand-side driver while simultaneously drawing attention to financial stability tail risks. These remarks indicate that the central bank is receptive to structural productivity enhancements but remains firmly unwilling to lock in a rigid policy trajectory for the remainder of 2026.
The US Dollar's Role in Global Reserve Architecture
The US Dollar functions as the principal currency of the United States and serves as a de facto medium of exchange across multiple foreign economies where it circulates alongside domestic cash. According to international clearing figures, the dollar participates in more than 88 percent of all global foreign exchange trades, generating an estimated daily volume of roughly $6.6 trillion.
The greenback assumed global reserve dominance from the British Pound following the Second World War. Throughout much of its institutional history, dollar issuance remained anchored by gold reserves until the dissolution of the Bretton Woods framework in 1971 dismantled the gold standard. In the modern era, central bank interest rate settings represent the single most consequential determinant of exchange rate behavior. Operating under a dual mandate of price stability and maximum employment, the Federal Reserve adjusts borrowing costs to regulate macroeconomic liquidity.
When domestic inflation accelerates past the official 2 percent objective, the Federal Reserve responds by increasing benchmark rates, which traditionally bolsters currency valuations. Conversely, rising joblessness or disinflationary pressures prompt borrowing cost reductions that weigh on the dollar. Under emergency conditions, central bankers utilize quantitative easing by purchasing government bonds from institutions to unblock interbank credit flows, typically debasing currency strength. In contrast, balance sheet reduction through quantitative tightening tends to support currency pricing over extended cycles.
Foreign Exchange Crosses and Related Asset Classes
The hesitation in the dollar index generated diverse trading conditions across correlated currency and asset markets. In Asian dealing, the AUD/USD pair pushed toward the 0.7000 threshold as market sentiment recovered, aided directly by the temporary pause in the dollar's upward path, though geopolitical unrest and pending corporate earnings in the tech sector prevented larger breakouts.
The USD/JPY cross found stability around 158.50 in Asian trade, as market participants maintained neutral positioning ahead of Japan's National Consumer Price Index release scheduled for Friday. Elevated United States sovereign bond yields offered steady baseline support for the greenback against the yen. In precious metals, spot gold drifted down toward $4,120 per ounce in European trade, weighed down by rising yields on United States paper and firmer energy markets. The 10-year US Treasury yield stood at 5.13 percent, consolidating after a 1.2 percent advance on Monday. Within digital assets, NEAR Protocol fell approximately 2 percent on Tuesday, even as institutional interest showed resilience through more than $5 million in inflows into the Bitwise NEAR exchange traded fund.