


















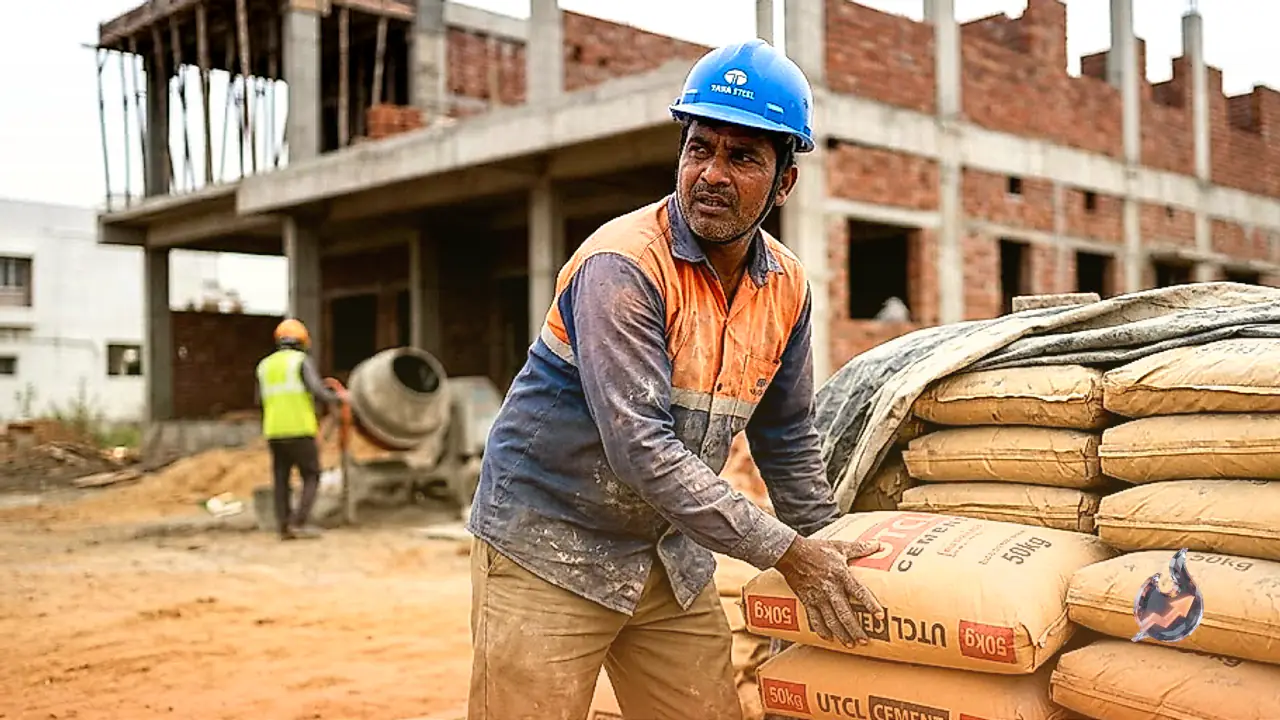

People planning to build a house or carry out structural renovations are likely to encounter higher construction expenses in the coming weeks. Cement manufacturing companies are lining up another round of price hikes across several key markets starting next month. Projections indicate that cement prices could climb by ₹5 to ₹20 per bag during October. However, the long-term sustainability of these revised rates will largely hinge on dealer acceptance and the real pace of consumer demand across regional centers.
September Saw Average Trade Rates Reach ₹356 per Bag
Looking at the market trends over the past month, the average trade price of cement across the country witnessed a month-on-month increase of ₹7 per bag in September, bringing the prevailing level to approximately ₹356 per bag. This movement followed a relatively flat period during July and August, when prices stayed broadly stable. Price increases during September occurred across both trade and non-trade categories, with the non-trade sector registering comparatively sharper gains. Even so, the entire price increase implemented at the company billing level was not immediately passed down to end consumers. In multiple trading hubs, dealers absorbed part of the increase or sold inventory at previous price levels to meet their quarterly volume targets.
Southern and Western Markets Led Regional Price Spikes
A geographical breakdown of the price movement reveals that southern India experienced the sharpest surge during September, where cement rates escalated by ₹11 per bag. Western India followed closely with an average increase of ₹9 per bag. In contrast, markets across central, eastern, and northern India recorded relatively modest price rises, with cement moving up by around ₹5 per bag in those zones.
Fuel Cost Inflation and Post-Monsoon Demand Drive Pricing Pressure
Cement producers are now positioning themselves for another price hike in October, but its durability depends heavily on the recovery of on-ground building activity. Demand remained muted in several markets through July and August, although September registered a gradual pickup in select pockets. Rainfall distribution also created stark regional contrasts: territories receiving heavy monsoon showers saw construction sites slow down, whereas areas with lighter rains maintained steady operational progress. Compounding these factors is the sharp increase in fuel expenses over recent weeks, which has inflated manufacturing overheads and logistical costs for producers. Going forward, the primary drivers shaping market rates will be whether local distributors absorb the revised figures and how strongly residential and commercial construction demand rebounds.