


















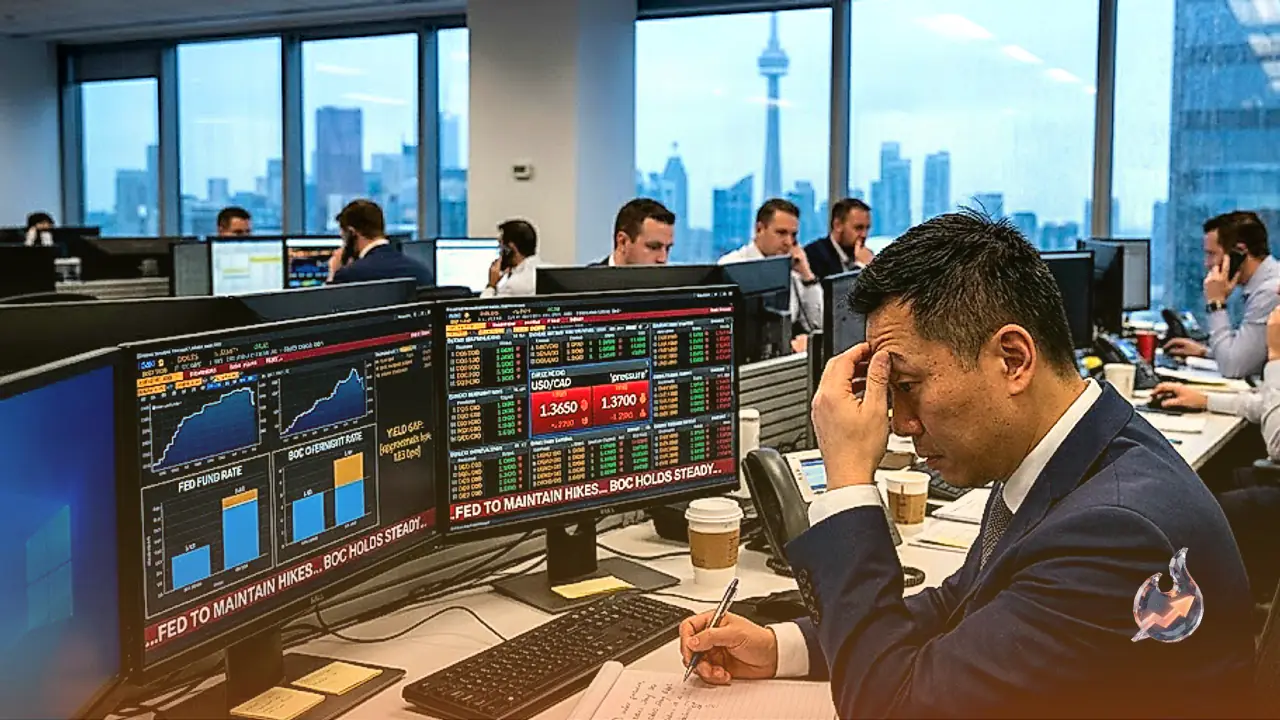

Interest rate differentials between the United States and Canada continue to serve as the primary engine steering the USD/CAD foreign exchange cross. For international investors and currency desks, the yield spread reflects the additional return generated simply by allocating capital into US Dollars rather than Canadian Dollars, commonly referred to as the Loonie. Market participants routinely reposition portfolios in advance of anticipated adjustments to these monetary gaps. On September 16, the Federal Reserve raised its policy benchmark to a range of 3.75% to 4.00%, marking its first policy tightening since 2023 and placing the midpoint at 3.875%. In contrast, the Bank of Canada (BoC) maintained its target overnight rate at 2.25% across seven consecutive policy deliberations. Consequently, US benchmark borrowing costs stand precisely 1.625 percentage points above their Canadian counterparts.
Yield Disparities and September 2027 Projections
The principal catalyst behind the upward momentum in USD/CAD has been the expected policy rate spread projected for September 2027. In mid-August, futures markets reflected an anticipated differential of approximately 1.0 percentage point. By September 29, that expected gap had widened substantially to roughly 1.4 percentage points. The bulk of this divergence materialized across the two-week span surrounding the Federal Reserve's September 16 policy move. During that identical period, USD/CAD advanced from beneath 1.3800 to levels above 1.4050. This price dynamic meant that the Canadian currency weakened steadily over three weeks, even while derivatives markets were pricing nearly five rate hikes from Canada's own central bank.
Fluctuations in near-term meeting probabilities have done little to disrupt the one-year-ahead rate gap. New York Federal Reserve President John Williams moderated expectations regarding an immediate follow-up hike during public appearances, followed closely by cooler US inflation figures. Together, these developments shaved approximately 28 percentage points off the probability of an October Federal Reserve hike. However, they adjusted the market's expected September 2027 Fed policy rate by a modest four-hundredths of a percentage point. For traders navigating USD/CAD, near-term probabilities primarily dictate the timing of spread adjustments rather than the overall magnitude of the monetary divide.
Comparative Policy Paths Through 2027
Mapping the market-implied trajectories of both central banks shows expectations for each institution to deliver approximately two quarter-point rate hikes through late January. Such symmetric tightening will preserve the interest rate gap within a tight corridor of 1.5 to 1.6 percentage points throughout the upcoming winter months. Past that horizon, current pricing suggests the Federal Reserve will moderate its tightening pace and conclude its rate-hiking cycle near 4.75% by the middle of 2027. Conversely, the Bank of Canada is priced to continue raising rates incrementally, reaching roughly 3.45% by September 2027.
Under this anticipated trajectory, the transatlantic policy gap would contract to around 1.35 to 1.4 percentage points by late 2027. A spread contraction of this size is equivalent to approximately one additional Bank of Canada rate increase relative to the Fed. Crucially, the entire premise of this narrowing depends on Canadian policymakers pressing ahead with hikes after their US counterparts have already concluded their cycle. Until that divergence materializes, carrying US Dollar exposure continues to generate an annualized interest advantage of roughly one and a half percentage points over Canadian Dollars.
Federal Reserve Outlook and Persistent Core Inflation
Official projections published alongside the Federal Reserve's September 16 policy action provide a contrasting perspective to financial market pricing. The Fed's median dot-plot forecast placed its policy rate at 4.1% at the close of 2026 and held it flat at 4.1% through the conclusion of 2027. This path implies merely one additional 25-basis-point tightening followed by an extended policy pause. Meanwhile, derivatives pricing has factored in nearly three quarter-point increases beyond that baseline through September 2027. Data from CME Group's FedWatch tool indicates that a target range of 4.75% to 5.00% is viewed as the single most probable terminal band by that date.
The Federal Reserve possesses tangible macroeconomic justification for maintaining a restrictive posture. The central bank's preferred inflation gauge, which strips out volatile food and energy expenditures, accelerated by 3% in the twelve months through August. This underlying inflation rate remains a full percentage point above the Fed's formal 2% target, cementing its case for monetary vigilance.
Bank of Canada Vulnerabilities and Macro Uncertainty
The policy rationale for prospective tightening by the Bank of Canada stands on comparatively fragile ground. Rather than responding to entrenched underlying pressures, the Canadian central bank's stance is rooted in the perceived risk that price accelerations could become self-sustaining over time. Canada's headline Consumer Price Index (CPI) climbed 3% year-over-year in August, but that figure moderated to 2.4% once gasoline costs were excluded. Furthermore, the central bank's two primary core measures, designed to filter out transient monthly price extremes, registered at 1.9% and 2.0%, precisely in line with official targets.
Underlying economic performance in Canada further complicates the central bank's mandate. The Canadian labor market contracted by 41.7 thousand positions in August. In terms of national output, real Gross Domestic Product (GDP) showed zero growth in July, alongside an initial estimate showing an expansion of merely 0.2% for August. In spite of these signs of domestic stagnation, traders continued to add Bank of Canada rate hikes to their pricing models. This makes the Canadian tightening leg the far more speculative half of the bilateral trajectory. While the Fed operates with core inflation visibly above target, the Bank of Canada possesses neither persistent core pressure nor domestic momentum, leaving its policy trajectory heavily reliant on global crude oil pricing. A downturn in energy markets would likely dismantle Bank of Canada rate expectations much faster than those of the Fed, reinforcing upward momentum in USD/CAD.
October Policy Decisions and the Debut of Prima
The initial stress test for this monetary path arrives on October 28, when both central banks are scheduled to release interest rate decisions, with Canadian policymakers announcing first. The Bank of Canada's accompanying Monetary Policy Report (MPR) will introduce 'Prima', the institution's newly constructed analytical framework designed specifically to differentiate temporary price spikes from enduring inflationary trends. Consequently, the model's operational debut coincides directly with the meeting that could deliver the BoC's first rate increase.
Financial markets currently price the first Canadian rate hike to occur by December at the latest, matching the anticipated timeline for the Federal Reserve's subsequent hike. In the run-up to the October 28 decisions, crucial economic data will guide market expectations: Canadian employment and inflation figures are slated for release on October 9 and October 19, respectively, while US consumer inflation data will be published on October 14.
Beyond individual policy meetings, three primary developments across the winter months will dictate the Canadian Dollar's trajectory. First, whether the Bank of Canada initiates tightening as currently modeled and explicitly signals ongoing rate increases. Second, whether Canada's underlying core inflation metrics break higher toward headline numbers to supply the evidentiary support currently lacking. Third, whether US core inflation resumes a steady deceleration toward the Fed's 2% objective, an outcome that would shorten the Fed's hiking timeline and deliver currency relief to the Loonie substantially sooner than 2027.
Technical Indicators and Resistance Barriers
From a technical charting standpoint, USD/CAD has fluctuated within a defined band between 1.3500 and 1.4250 since October 2025. The sharp appreciation observed throughout September propelled the exchange rate from the lower third of that structural boundary directly to its ceiling, retracing nearly 90% of the decline between the late-June peak and the August trough. This rapid ascent pushed the daily Stochastic Relative Strength Index (Stoch RSI) to the absolute ceiling of its scale, mirroring the extreme overbought conditions recorded when the June advance stalled at identical levels.
USD/CAD has reclaimed ground above its 200-day exponential moving average (EMA), positioned near 1.3900, a key trend gauge that the currency pair has traversed in both directions over the course of 2026. The defining structural hurdle on the daily timeframe remains the range ceiling at 1.4250. A decisive daily close above 1.4250 would thrust USD/CAD to exchange rates unseen since early April 2025. However, nothing in the currently priced interest rate differential widens the yield gap sufficiently to justify an immediate breakout of that magnitude.
According to live market data, USD/CAD (CAD=X) is trading at 1.42, recording a 0.32% gain over the previous close of 1.42. The 52-week trading corridor spans from 1.35 to 1.42, with trading volume running at 1.00 times the 20-day moving average. Technical gauges reflect a market testing upper bounds: the 14-day Relative Strength Index (RSI) stands at 78, entering overbought territory. The Moving Average Convergence Divergence (MACD) indicator sits at 0.01 against a signal line of 0.00, yielding a neutral-to-bullish histogram of 0.00. Moving averages demonstrate broad structural strength, with the 20-day EMA at 1.40, the 50-day EMA at 1.40, and the 200-day EMA at 1.39, while the 50-day SMA is 1.40 and the 200-day SMA stands at 1.38. The position of the 50-day EMA above the 200-day EMA confirms a sustained golden cross within a long-term uptrend. The 20-period Bollinger Bands bracket the market between 1.37 and 1.42, with a middle band at 1.40, keeping current prices inside band limits. The Average Directional Index (ADX) at 36 indicates robust trend strength, while the Stochastic oscillator displays a fast line of 100 and a signal line of 96. The 14-day Average True Range (ATR) of 0.01 provides a baseline buffer for stop-loss management. Support over the past 20 sessions sits near 1.38, with resistance at 1.42. Key trading inflection points place the pivot at 1.42, first resistance (R1) at 1.42, second resistance (R2) at 1.43, first support (S1) at 1.42, and second support (S2) at 1.41.
Trading Outlook and Cross-Asset Signals
As long as the current rate differential remains anchored between 1.5 and 1.6 percentage points over the winter, market incentives favor holding US Dollars over Canadian Dollars. The operational bias for USD/CAD remains skewed toward the upper half of its trading channel, between 1.3900 and 1.4250. A Bank of Canada tightening campaign delivered on schedule should keep the exchange rate contained within this defined zone. A structural breakout above 1.4250 would require the Canadian tightening thesis to disintegrate, potentially triggered by a drop in crude oil prices or core Canadian inflation lingering at 2.0%, forcing the BoC to hold or halt after a solitary hike. A confirmed daily close above 1.4250 would expose the 1.4300 resistance barrier.
Conversely, the prevailing bullish stance would be invalidated on a daily close beneath the 200-day EMA near 1.3900. Reaching that threshold would necessitate a faster-than-expected conclusion to the Federal Reserve's cycle fueled by cooling US inflation, paired with resolute BoC rate increases that compress the yield gap ahead of schedule. Nevertheless, even in that eventuality, US sovereign yields would maintain a distinct yield premium over Canadian yields through the conclusion of 2027.