














The Australian Dollar struggled to preserve its early momentum at the start of the trading week, falling back beneath the 0.7000 psychological threshold during Asian trading hours. Despite touching a nearly two-week high earlier on Monday, the AUD/USD pair could not capitalize on the move. While a slight retreat in US Treasury bond yields from multi-year peaks initially weakened the Greenback, broader macroeconomic concerns and safe-haven dynamics swiftly checked the currency's decline, capping the Australian Dollar's upside potential.
Geopolitical Escalation and Safe-Haven Demand Support the Greenback
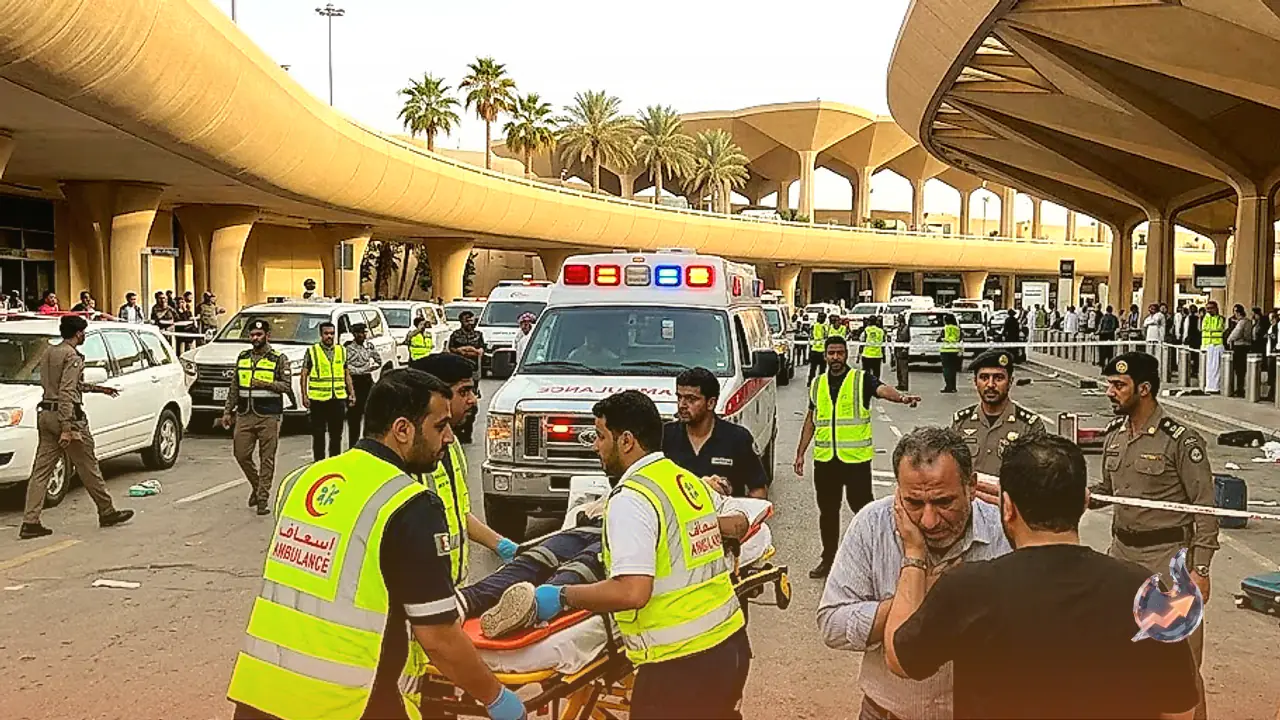
Early optimism that an energy peace agreement between Russia and Ukraine might ease international fuel shortages and curb inflationary pressures initially weighed on the US Dollar. However, an abrupt resurgence of geopolitical tensions across the Middle East quickly altered market sentiment. Over the weekend, the Iran-backed Houthi movement in Yemen intensified its strikes against Saudi Arabia, deploying a combination of ballistic missiles, cruise missiles, and drones aimed at King Khalid International Airport in Riyadh. Further amplifying regional tensions, US President Donald Trump raised the prospect of resuming military strikes against Iran. These developments revitalized geopolitical risk premiums, prompting market participants to purchase the US Dollar on dips.
Upcoming US Inflation Gauges and Federal Reserve Commentary in Focus
Foreign exchange participants showed clear caution, avoiding large directional positions ahead of critical macroeconomic releases scheduled for later in the week. Market attention is centered on the latest inflation metrics from the United States, with the Producer Price Index (PPI) due on Wednesday followed by the Consumer Price Index (CPI) on Thursday. The market will subsequently focus on an address by Federal Reserve Chair Kevin Warsh at the joint annual meetings of the International Monetary Fund and the World Bank in Bangkok on Friday. Comments on the central bank's policy path are expected to provide meaningful momentum for currency pairs. Domestically, the Australian currency faced headwind from fading expectations regarding another interest rate hike by the Reserve Bank of Australia (RBA) in November.
The Structural Dominance of the US Dollar and Federal Reserve Tools
Beyond daily market fluctuations, the US Dollar functions as the legal tender of the United States and serves as a de facto circulating currency across numerous international economies. According to data from 2022, the currency accounts for more than 88% of all global foreign exchange transactions, representing roughly $6.6 trillion in daily turnover. Following the conclusion of the Second World War, the US Dollar displaced the British Pound as the world's primary reserve asset. Until the termination of the Gold Standard under the Bretton Woods framework in 1971, its valuation was directly anchored to gold.
Monetary policy directed by the Federal Reserve remains the paramount determinant of the currency's valuation. Guided by a dual mandate to ensure price stability and sustain maximum employment, the central bank relies primarily on benchmark interest rate adjustments. When price pressures accelerate beyond the 2% target, rate hikes bolster the Dollar's appeal. Conversely, falling inflation or elevated unemployment prompt rate cuts, which soften the currency. In periods of extreme market freezing, such as the 2008 Great Financial Crisis, the Fed employs quantitative easing (QE) by printing currency to purchase government securities from financial institutions, which typically dampens currency strength. By contrast, quantitative tightening (QT), where the balance sheet contracts without reinvestment, generally provides upward support for the currency.
Developments Across Yen, Rupee, Gold, and Digital Assets
Across the broader financial landscape, cross-currency pairs and commodities reflected varied responses to shifting macro cues. The USD/JPY pair hovered above 158.00 in a narrow trading corridor, as market participants watched for potential intervention from Japanese authorities to stabilize the Yen amid holiday-thinned liquidity across both Japan and the United States. In India, the Rupee (INR) recorded notable gains as fresh measures implemented by the Reserve Bank of India (RBI) to curb foreign exchange demand prompted a 1% decline in USD/INR toward 95.80. Meanwhile, Gold continued its recovery from a two-month trough of $4,067, holding above the $4,200 mark. In digital asset markets, Cardano (ADA) stabilized above key support levels following last week's 2.85% retreat, supported by a shift in CoinGlass derivatives sentiment where the long-to-short ratio improved to 1.01.