














The Canadian Dollar (CAD) is holding steady against the US Dollar (USD), exhibiting muted movement in response to the latest provincial election outcome in Quebec. Even with the subdued immediate market reaction, political uncertainties are shaping up to be persistent medium-term headwinds for the currency. Heightened concerns surrounding secession referendums in Quebec and Alberta continue to weigh on investor sentiment. From a technical chart perspective, the recent advance in USD/CAD appears increasingly stretched, flashing bearish reversal warnings while offering scarce chart support between prevailing price levels and the 1.40 threshold.
Domestic Political Developments and the Canadian Dollar Outlook
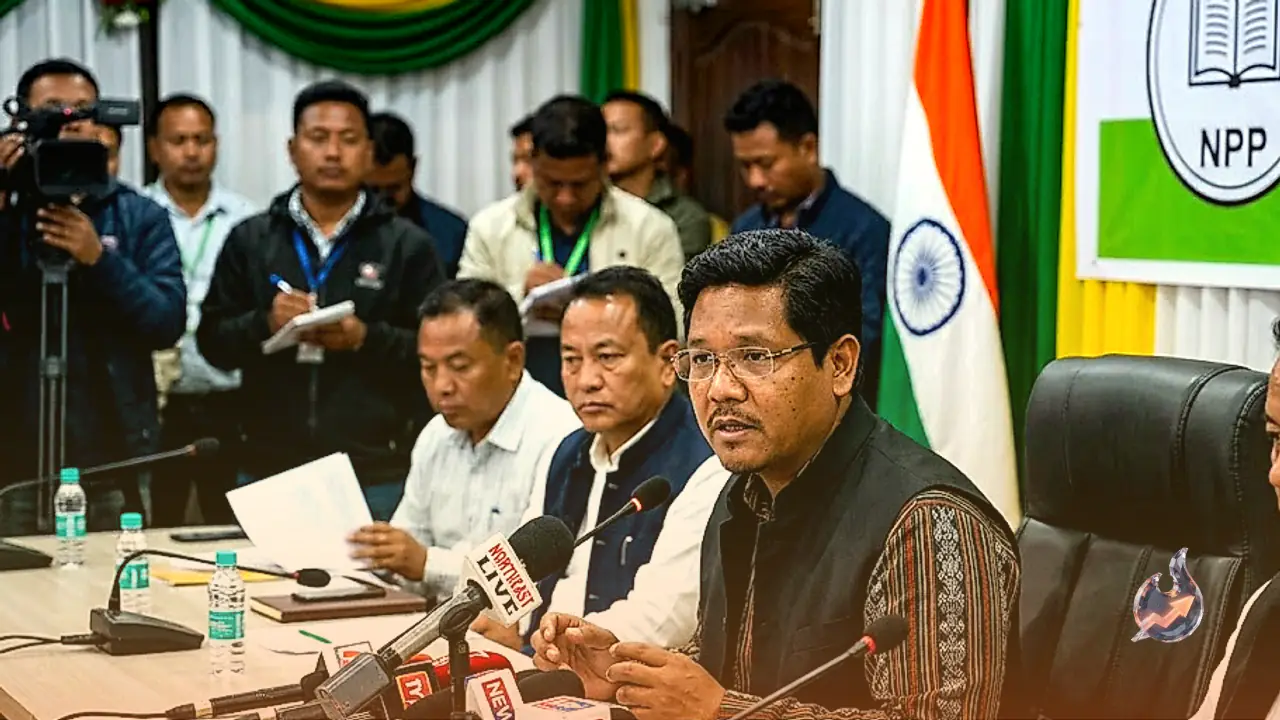
Foreign exchange strategists Shaun Osborne and Eric Theoret note that the Canadian Dollar continues to trade flat against the greenback, with market participants offering no material reaction to domestic political developments and Quebec's provincial election result. The strategists observe that risks for the Canadian currency are balanced on both sides. A minority victory for the Parti Québécois (PQ) has arrived alongside the possibility of forming a governing majority with the Conservatives. However, medium-term stability remains fragile given the PQ leader's commitment to conduct another secession referendum during his initial four-year mandate, strategically timed after the current US administration concludes in order to prevent external interference.
Osborne and Theoret emphasize that this outcome heightens the importance and tightens market focus on the upcoming October 19 Alberta referendum, which presents a significant sentiment-driven risk for the currency. For now, foreign exchange risk reversals remain relatively subdued, suggesting that market participants are maintaining a cautious stance rather than establishing aggressive directional bets.
Global Currency Dynamics Across Asian and European Sessions
Beyond North American cross-currents, other major currencies are feeling the weight of elevated fixed income yields. AUD/USD drifted lower during Tuesday's Asian trading session, halting a two-day rebound from the two-month trough recorded in the preceding week. A persistent sell-off across global fixed income markets has kept US Treasury yields anchored near multi-year peaks. These firm yields, compounded by ongoing geopolitical friction, have helped the US Dollar maintain an underlying bid despite fading wagers on an October interest rate hike from the Federal Reserve. Nevertheless, expectations that the Reserve Bank of Australia (RBA) could deliver another rate increase this month might offer modest support to the Australian Dollar.
In the European morning on Tuesday, USD/JPY pushed back above the 158.00 mark. The currency pair advanced as the Japanese Yen failed to draw upward momentum from expectations of a hawkish Bank of Japan (BoJ) or the looming possibility of currency market intervention by authorities. At the same time, geopolitical ambiguity and high US sovereign yields keep the US Dollar trading near its yearly high water mark despite waning October Fed hike probabilities. The Yen is hovering near 158.00 against the greenback ahead of a packed slate of domestic Japanese economic indicators and an uncertain BoJ policy timeline.
Gold Battles Resistance While Crypto Consolidates
In the commodities space, gold extended its slight Monday recovery but faced difficulty retaking the pivotal $4,200 per troy ounce threshold on Tuesday. The precious metal's upward attempt was supported by emerging downside momentum in the US Dollar alongside easing US Treasury yields across the entire curve.
Digital assets maintained an overall bullish structure, with Bitcoin trading at $85,837 on Tuesday as selling pressure worked to regain grip on the prevailing trajectory. The broader altcoin sector mirrored Bitcoin's consolidation pattern, as Ethereum moved sideways above the $2,700 benchmark and Ripple traded around the pivotal $1.50 line.
The European Central Bank's Policy Dilemma
In Europe, the European Central Bank (ECB) would typically implement a direct and conventional response when inflation runs at nearly twice its official target: raising benchmark interest rates. However, current macro circumstances are far from standard. Sovereign bond markets have already carried out a portion of the monetary tightening on their own through higher borrowing yields, leaving the ECB confronting a progressively complex policy conundrum.