














The Dow Jones Industrial Average registered modest gains on Monday, climbing toward the 51,900 threshold as market participants digested diplomatic overtures regarding the Middle East and prepared for high-stakes bilateral talks with China. Investor focus centered on comments from Donald Trump floating the possibility of a direct meeting with Iran, an outcome that could exert downward pressure on international crude oil benchmarks. Live market data shows the Dow trading at $51,993, advancing 0.60% from the prior session close of $51,683. Lower energy prices are seen as an immediate benefit to multiple components of the index, easing transportation and operating expenditures across industrial and consumer sectors.
For the non-energy corporate constituents of the 30-stock gauge, a retreating crude oil price translates into reduced input costs for gasoline, diesel, and aviation fuel. Lower fuel expenses eventually filter through to broader consumer price indices, which the Federal Reserve closely monitors when determining its monetary policy path. While optimism surrounding a diplomatic breakthrough that could bring an end to hostilities gained attention, historical market reactions suggest caution: crude oil similarly dipped beneath the $100 per barrel mark when Trump announced a ceasefire in April, as well as during May when negotiations were described as nearing completion, only for volatility to resurface later.
Austan Goolsbee Identifies Four Drivers Fueling US Inflation
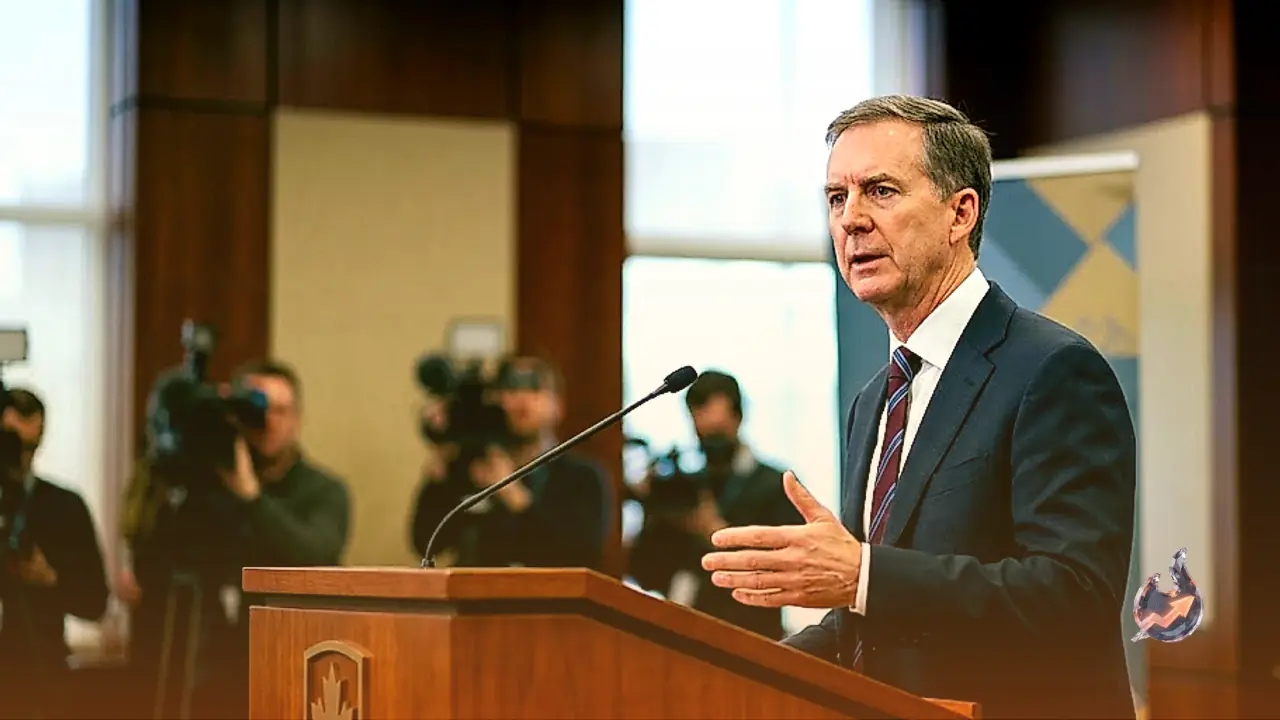
Federal Reserve policy expectations received renewed clarity following remarks by Chicago Fed President Austan Goolsbee during an address in London on Monday. Goolsbee outlined four primary factors responsible for sustaining upward pressure on consumer prices: robust consumer demand, newly imposed tariffs, volatile energy prices, and persistent disruptions across supply chains. The most recent inflation estimates placed the headline figure at 3.7% for July, running significantly above the central bank's stated 2% medium-term target.
Addressing the economic landscape, Goolsbee emphasized that the Federal Reserve's commitment to containing overheating aggregate demand remains unequivocal. The standard monetary remedy to demand-driven price spikes is tighter policy through higher benchmark interest rates designed to moderate consumer and corporate expenditure. This policy dynamic directly impacts index heavyweights such as Visa (V) and American Express (AXP), whose financial models depend fundamentally on charging processing fees on aggregate card transaction volumes. Restrictive monetary measures that curtail discretionary spending inevitably cloud the revenue outlook for payment processors.
Xi Jinping's White House Visit and Boeing's Pivotal Commercial Exposure
Geopolitical diplomacy moves to Washington on Thursday as Chinese President Xi Jinping conducts a formal state visit to the White House, notably bypassing the United Nations General Assembly in New York. Among all 30 members of the Dow Jones Industrial Average, aerospace manufacturer Boeing (BA) holds the most direct commercial exposure to the outcome of the bilateral summit. Beijing committed in May to purchase 200 Boeing commercial jetliners, representing the nation's first major commercial aircraft commitment from the manufacturer since 2017. However, the transaction was ratified without providing public details regarding specific aircraft variants or firm delivery schedules.
In preliminary high-level discussions, US Treasury Secretary Bessent conferred with Chinese Vice Premier He Lifeng to establish the summit agenda. Bessent noted that Washington intends to observe whether Chinese negotiators follow through with additional commercial commitments for Boeing aircraft upon Xi's arrival. Trump previously indicated that the procurement agreement could potentially scale up to 750 aircraft if the initial allocation of deliveries proceeds smoothly. This contingency effectively places China on a probationary footing regarding its commercial aerospace procurement.
Critical Minerals Agreement and Technology Supply Chains
Beyond aviation contracts, both delegations are scheduled to address the critical minerals arrangement finalized in October 2025. That understanding preserved the continuous export flow of Chinese rare earth elements to American manufacturers and is slated to expire approximately five weeks following the bilateral summit. Chinese negotiators have advocated for extending the agreement across the remainder of Trump's presidential tenure, whereas the administration in Washington has favored an incremental extension spanning only several months.
The duration of this trade mechanism carries immense practical significance for multiple corporate leaders within the index. Specialized rare earth elements serve as essential inputs for the permanent magnets integrated into Boeing's jet aircraft flight systems and defense hardware. Concurrently, these critical materials are indispensable for the components and specialized circuitry in devices manufactured by Apple (AAPL). Consequently, any protracted disruption or heightened tariff regime on rare earth minerals would alter manufacturing schedules and margins for both industrial and consumer electronics titans.
Upcoming Macro Data: Flash PMIs and Durable Goods Orders
Economic indicators due later in the week will provide critical evidence regarding domestic business activity. S&P Global is scheduled to release its preliminary Purchasing Managers Index (PMI) data for September on Wednesday at 13:45 GMT. Economists project the manufacturing PMI to moderate to 53.5 compared to the previous reading of 53.9, while the services index is forecast to register 56 following a prior figure of 56.5. Because any reading above the 50.0 baseline represents an expansion in operational output, both sectors are expected to remain in growth territory, albeit at a slightly decelerated pace. For payment networks like Visa and American Express, an expansive services reading near 56 confirms resilient retail spending, yet simultaneously bolsters the macroeconomic justification for tighter Fed policy.
Subsequent data arriving Friday at 12:30 GMT will feature August durable goods orders, with consensus forecasts projecting a contraction of 0.3% following the prior month's 1.1% increase. Stripping out the volatile transportation component, core durable goods orders are expected to increase by 0.6% after a previous gain of 0.4%. The differential between these two figures reflects the transportation category, which fluctuates primarily based on large-scale commercial aircraft bookings, serving as a direct reflection of Boeing's monthly order intake.
Technical Structure: Critical Resistance Barriers and Support Floors
From a technical charting perspective, Monday's peak matched the previous high established on September 17 just above the 52,100 barrier, marking the second occasion across three trading sessions where upward momentum stalled at that exact overhead level. Further above lies the descending 50-day Exponential Moving Average (EMA) positioned near 52,600, a threshold that the index has failed to reach in any trading session since the Federal Reserve initiated its latest rate adjustment. Current live moving average data confirms the 50-day EMA at $52,553 and the 20-day EMA at $52,509, positioned above the 200-day EMA at $50,288, reflecting an intact longer-term golden cross formation.
On the downside, Monday's low just above 51,750 provided initial intraday price support where the retracement halted. Below that mark, downside levels are anchored by the September 18 low situated marginally under 51,500, followed by the September 16 low near 51,200, which stands as the index's lowest trading level since June. Live technical indicators place the daily pivot at $51,924, with immediate resistance levels at R1 $52,100 and R2 $52,207, alongside support markers at S1 $51,817 and S2 $51,641. The 52-week trading corridor spans between $45,057 and $54,744.
Momentum gauges highlight a cautious landscape. The daily Stochastic Relative Strength Index (Stoch RSI) is tracking near 23 and has remained largely dormant since September 18, indicating depressed momentum that has yet to produce an upward reversal signal. Standard daily technical indicators reflect an RSI(14) of 43 and a bearish MACD reading of -356.54 against its signal line of -218.08. As long as prices remain capped beneath the twin highs just above 52,100, the technical outlook carries a bearish bias targeting 51,500 and 51,200. A daily settlement above 52,200 would invalidate this downward configuration.
The Structure of the Dow and Principles of Dow Theory
Established by Charles Dow, who also co-founded The Wall Street Journal, the Dow Jones Industrial Average represents one of the world's most enduring equity benchmarks, tracking 30 blue-chip companies across the United States. Unlike broader capitalization-weighted indices, the DJIA uses a price-weighting calculation methodology, derived by summing the share prices of all 30 constituent stocks and dividing by a mathematical divisor, currently set at 0.152. While historically prominent, the index has faced persistent scrutiny from institutional portfolio managers who argue that a 30-stock basket fails to capture the breadth of the domestic economy when compared to benchmarks like the S&P 500.
Charles Dow also formulated Dow Theory, a foundational technical methodology used to discern primary market trends. The theory mandates comparing the directional trajectory of the Dow Jones Industrial Average alongside the Dow Jones Transportation Average (DJTA), dictating that a confirmed primary trend requires congruent directional movement across both gauges, verified by trading volume. Dow Theory categorizes market developments into three distinct phases: the accumulation phase, where institutional participants systematically establish positions; the public participation phase, where widespread retail activity joins the prevailing trend; and the distribution phase, where institutional capital unloads holdings to broad market buyers.
Cross-Asset Movements in Currencies, Sovereign Debt, and Gold
Cross-asset dynamics across international markets highlight late-third-quarter volatility. In Asian currency trading, the Australian Dollar (AUD/USD) held firm above 0.7100 as the US Dollar index interrupted its recent rally, supported by market expectations of potential rate hikes by the Reserve Bank of Australia, despite the People's Bank of China leaving its Loan Prime Rates unaltered. Concurrently, USD/JPY retreated below 157.00 following rate-check operations by the Bank of Japan, which raised its policy rate target to 1.25% from 1.00% via a 7-2 vote. Spot gold prices adjusted lower toward $4,350 per troy ounce under pressure from the US Dollar, even as sovereign Treasury yields softened across the curve.