














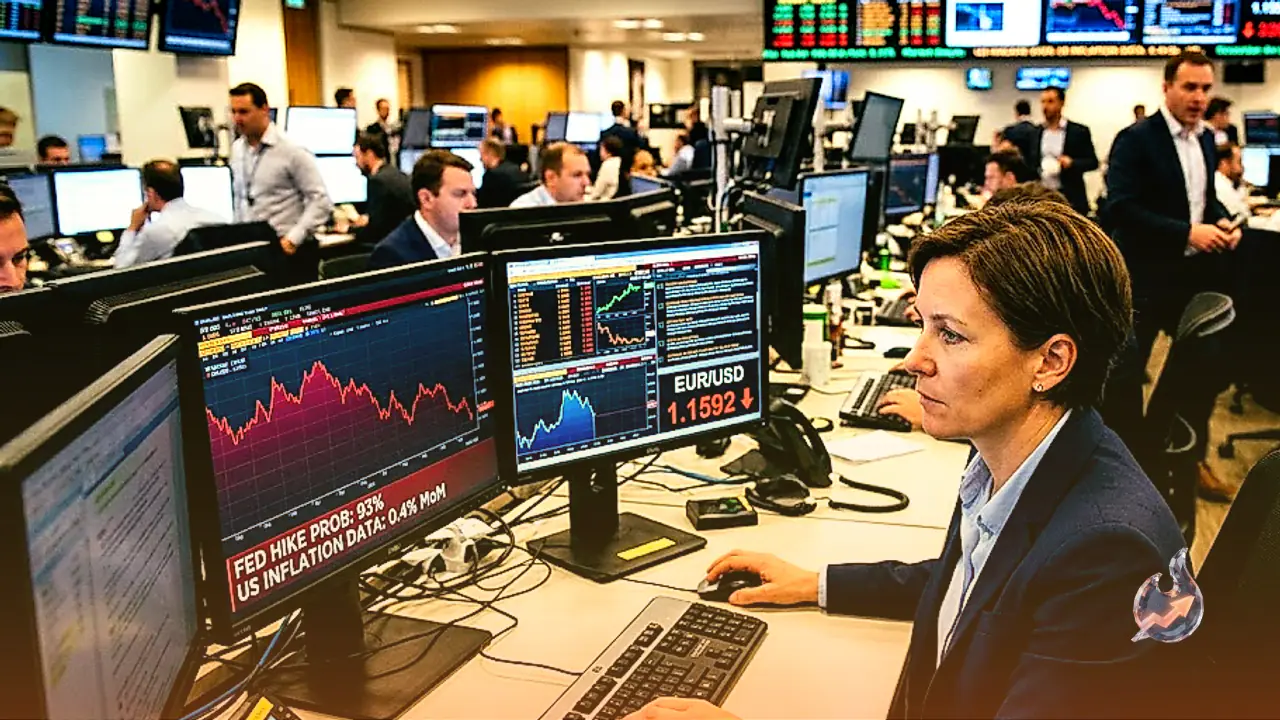

Selling pressure surrounded the European common currency as global markets kicked off the trading week, pushing the exchange rate toward 1.1585 in Monday's early Asian session. The pullback was primarily fueled by expanding market expectations that the Federal Reserve will implement a quarter percentage point interest rate increase at its upcoming Wednesday policy meeting. Concurrently, hawkish signals from the European Central Bank have kept expectations alive for further policy tightening in Europe, creating an active tug-of-war across the foreign exchange landscape.
Accelerating US Price Pressures Reshape Rate Expectations
Price data from the United States indicated fresh momentum in living costs during August, solidifying arguments that monetary policy will remain restrictive. Figures released on Friday by the Bureau of Labor Statistics revealed that headline consumer inflation climbed 0.4% month-over-month, maintaining the 12-month advance at 3.4%. These headline measurements landed squarely in line with consensus projections.
A closer examination of core metrics, which strip away the volatile swings in food and energy components, showed an increase of 0.3% on a monthly basis. This exceeded the 0.2% pace recorded in the prior month as well as economists' median expectations of 0.2%. Following the stronger core print, market pricing tracked by the CME FedWatch tool indicated that the probability of a quarter-point rate hike at the Fed's September gathering surged to nearly 91%, up substantially from 72% prior to the producer price release.
European Central Bank Maintains Tightening Posture
On the other side of the Atlantic, the European Central Bank lifted its deposit facility rate to 2.50% at its policy conclave last week, aligning with market projections. That move represented Frankfurt's second rate hike of the calendar year, following an initial borrowing cost increase in June that marked the first upward move since 2023.
Economists at Barclays highlighted that further monetary tightening remains probable. The hawkish decision delivered by policymakers underscored persistent worries that price growth across the single-currency bloc could remain stubborn for an extended period, prompting officials to maintain higher rates for longer.
Chart Dynamics and Critical Price Boundaries
From a chartist perspective, daily technical formations show EUR/USD trading above its 100-day simple moving average (SMA) and the lower Bollinger Band. While this positioning hints at lingering underlying interest from buyers, the pair has struggled to climb above the central Bollinger line, keeping upside momentum constrained. The 14-period Relative Strength Index stands around 48.8, reflecting neutral conditions where buyers and sellers are evenly balanced within a defined range.
Technical overhead begins around 1.1628 at the middle Bollinger Band SMA, with secondary resistance seen at the upper band near 1.1695, where sellers could step in aggressively. To the downside, primary cushion is anchored by the lower Bollinger boundary at 1.1560 alongside the 100-day SMA at 1.1555. This tight cluster serves as vital support; a decisive daily close below it could invite deeper retracements, whereas holding firm maintains prospects for another challenge toward 1.1628.
Recent live data points show the currency pair hovering near 1.15, matching its previous closing print of 1.15 (+0.11%). Complementary technical indicators place the 14-day RSI around 37 with a bearish MACD configuration. Moving averages reflect overhead resistance, with the 50-day and 200-day exponential moving averages converging near 1.16 amid a broader downward structure.
The Euro's Systemic Footprint in Global Trade
The euro serves as the legal tender for the 20 European Union member nations comprising the Eurozone, standing as the second most widely traded currency globally after the greenback. Transaction metrics from 2022 demonstrate that the euro captured 31% of worldwide currency turnover, representing a daily trading volume exceeding $2.2 trillion. The EUR/USD cross alone dominates international foreign exchange trading, accounting for an estimated 30% of all deals. Other major pairs include EUR/JPY at 4%, EUR/GBP at 3%, and EUR/AUD at 2%.
Headquartered in Frankfurt, Germany, the European Central Bank operates as the reserve authority managing Eurozone monetary conditions. Mandated with safeguarding price stability, the institution balances controlling inflation against supporting broader economic health, utilizing interest rates as its primary operational lever. Higher borrowing yields relative to other regions typically bolster the euro by drawing international investment capital into European sovereign and corporate instruments.
Policy decisions are determined by the ECB Governing Council through eight scheduled gatherings each year. Voting participants include the governors of the Eurozone's national central banks alongside six permanent executive members, led by ECB President Christine Lagarde.
Economic Metrics and Cross-Border Trade Flows
Inflation figures captured by the Harmonized Index of Consumer Prices serve as a critical compass for monetary direction. Should consumer price increases consistently exceed the official 2% target, the ECB is compelled to hike borrowing benchmarks to cool demand. Such relative rate differentials frequently enhance the single currency's appeal to international fund managers seeking higher yields.
Broader economic barometers including Gross Domestic Product growth, manufacturing and service sector purchasing managers' indexes, employment figures, and sentiment surveys also dictate exchange rates. Solid macroeconomic health fosters foreign direct investment while empowering policymakers to maintain elevated rates. The performance of the bloc's four economic powerhouses, namely Germany, France, Italy, and Spain, carries exceptional weight, as they collectively generate 75% of total Eurozone output.
Trade balance statistics provide another critical input by measuring the surplus or deficit between export revenues and import costs. When regional enterprises produce globally sought-after manufactured goods and services, foreign purchasers must acquire euros to settle contracts, generating sustained structural demand that reinforces the currency's valuation.
Movements Across Precious Metals and Other Majors
The greenback's resilience left ripples across other major assets. The Australian dollar experienced a subdued start to the week, trading around mid-0.7100 near Friday's lows as Fed hike expectations favored the dollar. Regional instability in the Middle East and clashes in the Strait of Hormuz provided additional safe-haven demand for the US currency, though hawkish positioning from the Reserve Bank of Australia helped stave off deeper losses in the Aussie.
Meanwhile, USD/JPY consolidated around seven-month lows logged earlier in the month, as investors adopted cautious stances ahead of the FOMC verdict on Wednesday and the Bank of Japan's rate review on Friday. Gold prices also struggled to build on Friday's rebound from below $4,300, remaining pressured by rising yields and safe-haven flows toward the US dollar driven by escalating tensions between Washington and Tehran.