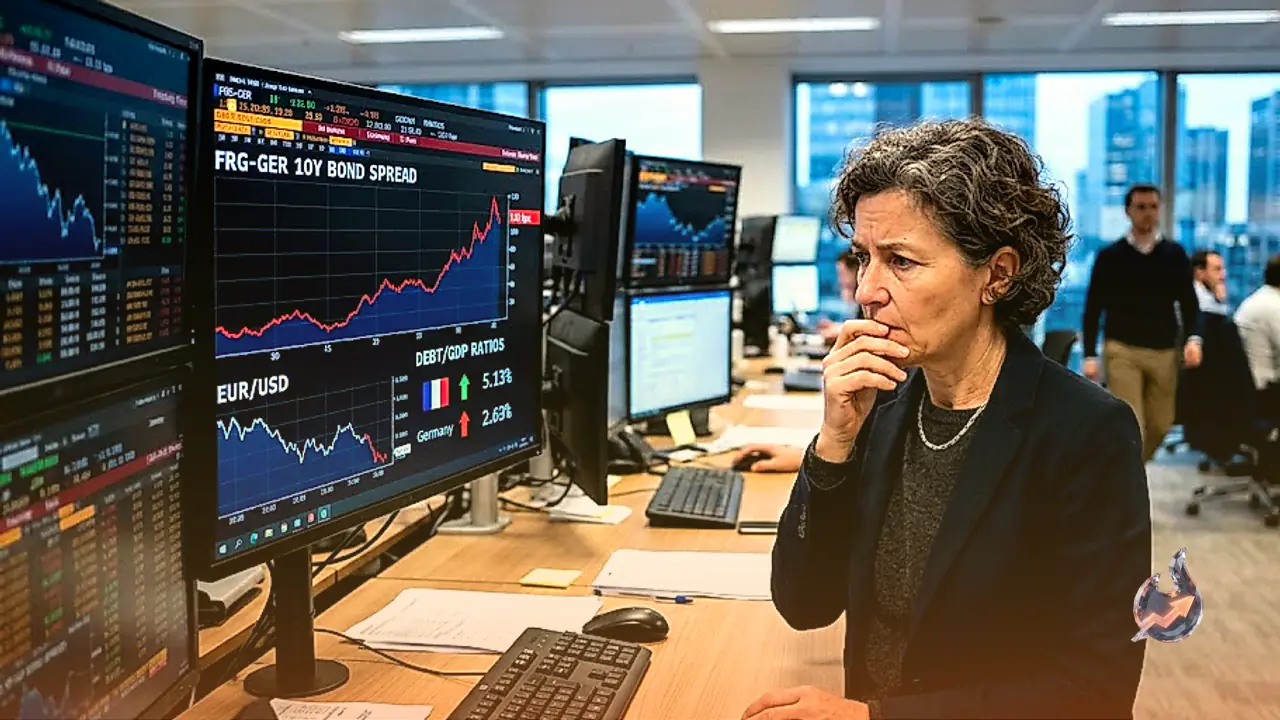

















Trading sentiment across global currency markets reflects sustained headwinds for the shared European currency against the US Dollar. Despite hawkish forward guidance from the European Central Bank, the Euro has struggled to turn that rhetoric into durable upside momentum. Analysts point to persistent complications in the global landscape, emphasizing that upward momentum for the Euro will remain constrained throughout the ongoing conflict involving Iran. Reflecting these developments, near-term projections for the currency over a one-month horizon have been scaled back from 1.16 down to 1.14. The policy landscape has shifted noticeably, with market participants now pricing in approximately a 70% probability of an October rate increase following the 25-basis-point hike implemented earlier in the month.
Conflict Headwinds and Pressure Points for the Euro
A combination of geopolitical conflict and transatlantic divergence continues to challenge the Euro. While the European Central Bank has sought to project policy firmness, market conditions have limited the transmission of that stance into currency strength. Prolonged hostilities involving Iran have fostered persistent caution among international investors, diverting capital flows toward safe-haven assets and supporting the greenback. Backed by elevated US bond yields and expectations of enduring tightness from the Federal Reserve, the Dollar has maintained its upper hand, limiting the scope for any meaningful European currency recovery as long as regional conflict persists.
Asia-Pacific Currency Movements: Australian Dollar and Japanese Yen
Thursday's Asian trading session saw dynamic moves across Pacific currencies. The Australian Dollar surrendered ground, moving toward the 0.7000 threshold against the greenback after the release of domestic labor data for August. The Australian unemployment rate crept upward to 4.6%, slightly exceeding the consensus projection of 4.5%. Despite the tick in joblessness, employment change outperformed forecasts, expanding by 39.5 thousand positions. Even so, broader risk aversion ahead of international political meetings restrained currency bulls.
Concurrently, the Japanese Yen exhibited resilience against the greenback. The USD/JPY currency pair pulled back from three-week highs, stabilizing near 158.00 during the Asian session. An advance in domestic Japanese government bond yields, paired with lingering caution over potential currency intervention by authorities, provided the Yen with supportive traction. Nevertheless, the US Dollar preserved overnight gains near two-month highs, underpinned by resilient yields and steady expectations of tight monetary policy in Washington.
Bank of Japan Delivers Rate Increase While Swiss National Bank Pauses
Monetary policy actions diverged noticeably between Asian and European central banks. The Bank of Japan raised its short-term interest rate target from 1.00% to 1.25% in a decisive 7-2 vote. The adjustment marks a continuation of the central bank's gradual exit from extraordinary easing and the ongoing normalization of domestic policy, aligning neatly with the baseline expectations investors had maintained for several weeks prior to the announcement.
In Switzerland, the Swiss National Bank chose to hold its benchmark policy rate steady at 0%, fulfilling unanimous market forecasts. Within its updated assessment, the Swiss monetary authority specified that sight deposits placed by commercial banks at the central bank will receive interest at the policy rate up to a designated ceiling. Looking further ahead, the Swiss National Bank revised its 2026 inflation expectation slightly higher, projecting a rate of 0.7% compared with its prior 0.6% estimate. Swiss officials cautioned that the primary threat to domestic economic performance continues to originate from headwinds in the wider global economy.
Gold Slips as Markets Eye High-Stakes Trump-Xi Dialogue
Precious metals mirrored the cautious tone seen across asset classes, with gold trading with a negative bias for the second consecutive session. Bullion dropped beneath the $4,300 benchmark during early European trading, marking a one-week trough. Market participants adopted a defensive posture as they awaited discussions between US President Donald Trump and Chinese President Xi Jinping.
While investors hold subdued expectations for breakthrough pacts, market interest is firmly centered on potential developments surrounding critical technologies, rare earth supplies, and the prospective extension of the existing trade truce between the two economic giants. Until clarity emerges from these bilateral talks and central bank paths settle, global foreign exchange and commodity markets are poised to remain in a state of elevated vigilance.