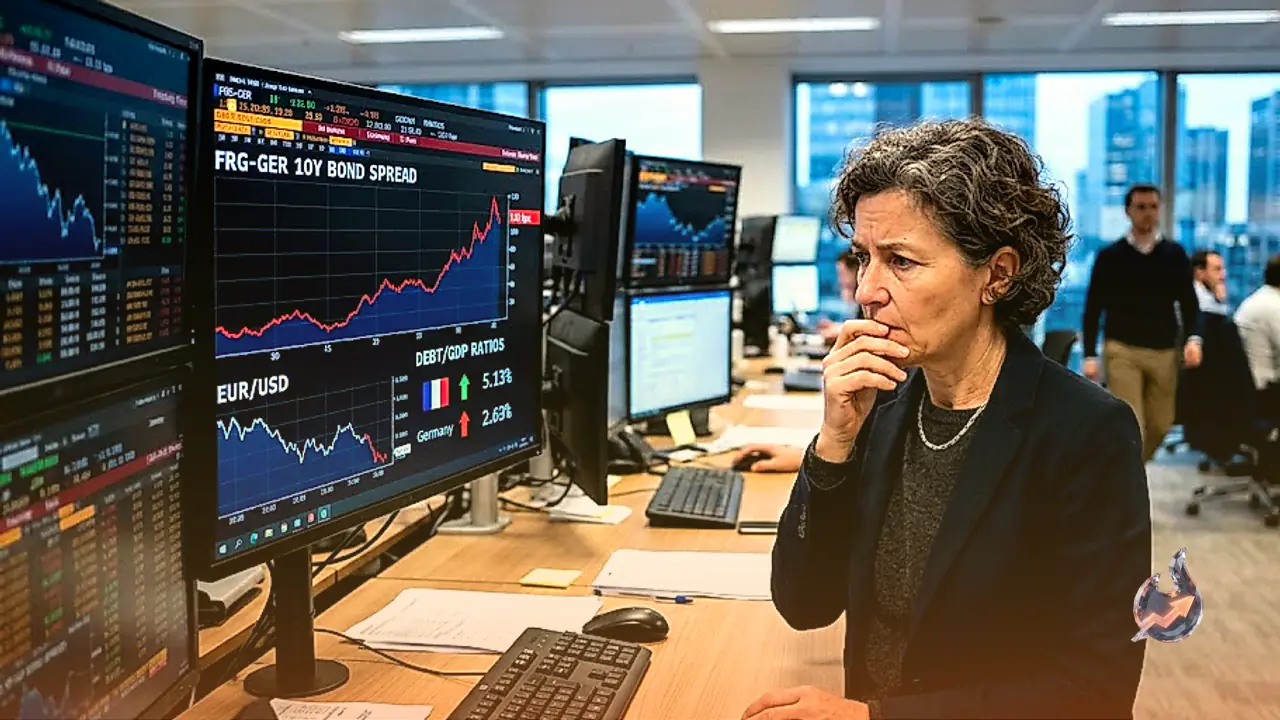
















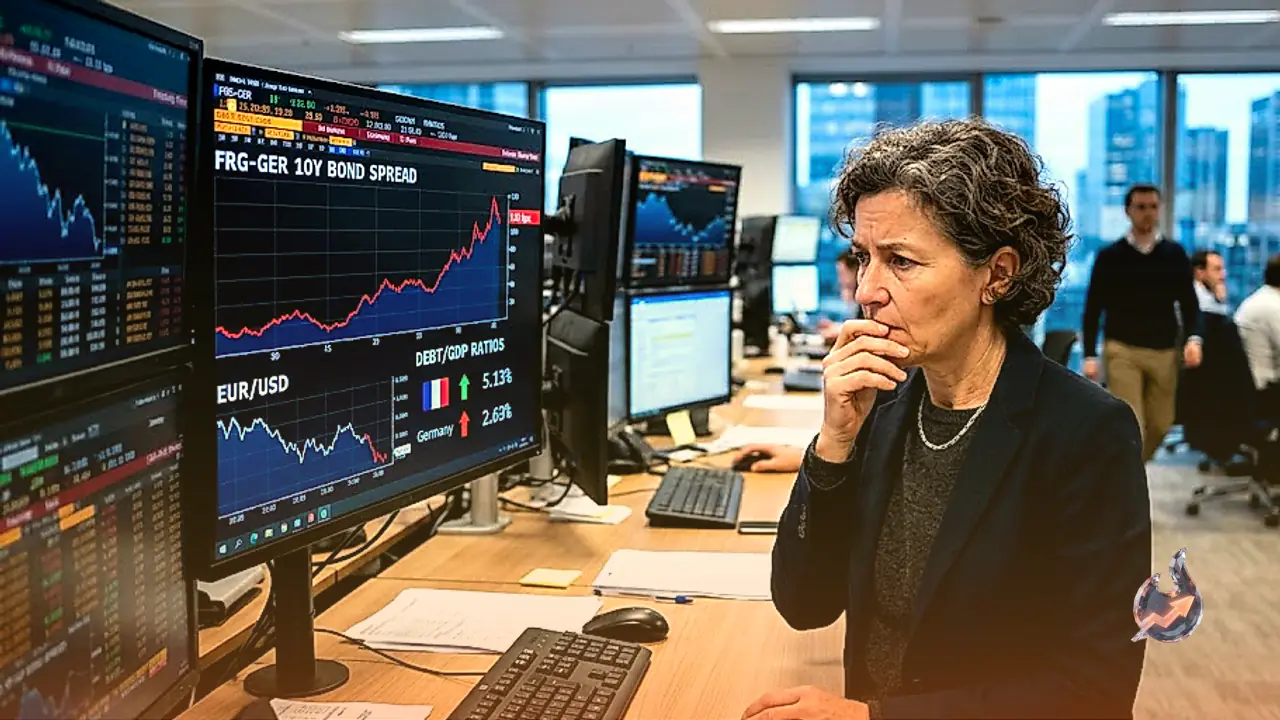

The Euro is experiencing persistent downward pressure in international currency trading, weighed down by escalating political friction and budget uncertainties in France alongside a broader selloff in worldwide debt markets. The yield spread between French OAT sovereign bonds and benchmark German Bunds has expanded outward to 110 basis points, reaching its widest differential since the sovereign debt crisis of 2012. With international asset managers trimming duration across global fixed-income portfolios, debt instruments perceived to carry higher fiscal vulnerabilities are witnessing the steepest declines. Even stronger than expected preliminary purchasing managers index readings across the common currency area have failed to arrest the slide in the European single currency.
Fiscal Pressures in France and Widening Yield Differentials
Market volatility remains closely tied to budgetary developments in Paris, where ambitious fiscal consolidation targets and political crosscurrents have unsettled bondholders. Derek Halpenny at MUFG observed that the yield premium demanded by investors to hold French sovereign debt rather than German paper touched 110 basis points. The widening spread does not stem from an isolated domestic shock within France alone, but rather reflects global portfolio managers shedding duration risk across international bond markets. In an environment characterized by elevated risk aversion, sovereign debt with higher underlying deficits is penalized more aggressively, generating direct negative momentum for the Euro across foreign exchange trading venues.
Credit Assessments and Key Currency Technical Thresholds
The sovereign debt landscape also absorbed a recent sovereign rating adjustment from smaller agency Scope over the weekend. That reduction lowered France's credit rating to A+, effectively matching the existing stances of major rating agencies S&P and Fitch. Both S&P and Fitch had previously reaffirmed a stable outlook for the country earlier in the year, in May and August respectively. In currency markets, currency analysts at MUFG highlight the 1.1340 level in EUR/USD as a crucial baseline support mark. A decisive break beneath this floor risks opening a pathway toward deeper depreciation into a 1.10 to 1.12 band. The underlying vulnerability was underscored during trading when the currency continued to weaken despite advance PMI prints coming in ahead of analyst projections.
Currency Movements Across the Asian Trading Session
Cross-asset dynamics exhibited notable swings across Asian dealing on Thursday as economic data and geopolitical expectations guided trading sentiment. AUD/USD softened toward the 0.7000 threshold following the release of the Australian labor report for August. The headline unemployment rate edged up to 4.6% against a consensus estimate of 4.5%, even as overall employment change comfortably exceeded expectations by registering an addition of 39.5K jobs. Market participants also adopted a cautious posture ahead of high-level diplomatic engagements between US President Donald Trump and Chinese President Xi Jinping.
Yen Intervention Watch, Dollar Resilience, and Gold Consolidation
Meanwhile, USD/JPY pulled back from recent three-week highs to hold losses around 158.00 during Thursday's Asian session. A rally in domestic government bond yields provided a tailwind to the Japanese Yen amid ongoing speculation regarding potential market intervention by authorities. Concurrently, the US Dollar preserved broad-based gains near a two-month peak, bolstered by resilient Treasury yields and market expectations of sustained monetary policy restraint from the Federal Reserve. Spot gold held in a tight consolidation range near a one-week low as investors refrained from aggressive positioning prior to the Trump-Xi summit, where observers will monitor potential discussions concerning rare earth exports, technological trade barriers, and the continuation of the bilateral truce.
Policy Stances from the Swiss National Bank and Bank of Japan
Central banking decisions added further clarity to sovereign rate trajectories in Europe and Asia. The Swiss National Bank held its headline policy interest rate steady at 0%, fulfilling broad market consensus. In its monetary policy assessment, the SNB noted that sight deposits held by commercial banks at the central bank will earn interest at the official policy rate up to a prescribed cap. Swiss monetary officials raised their 2026 inflation projection slightly to 0.7% from the previous estimate of 0.6%, pointing to global macroeconomic developments as the primary risk factor for the domestic outlook. Simultaneously, the Bank of Japan advanced its policy normalization path by increasing its short-term interest rate target from 1.00% to 1.25% through a 7-2 majority vote, bringing policy settings in line with multi-week market projections.