













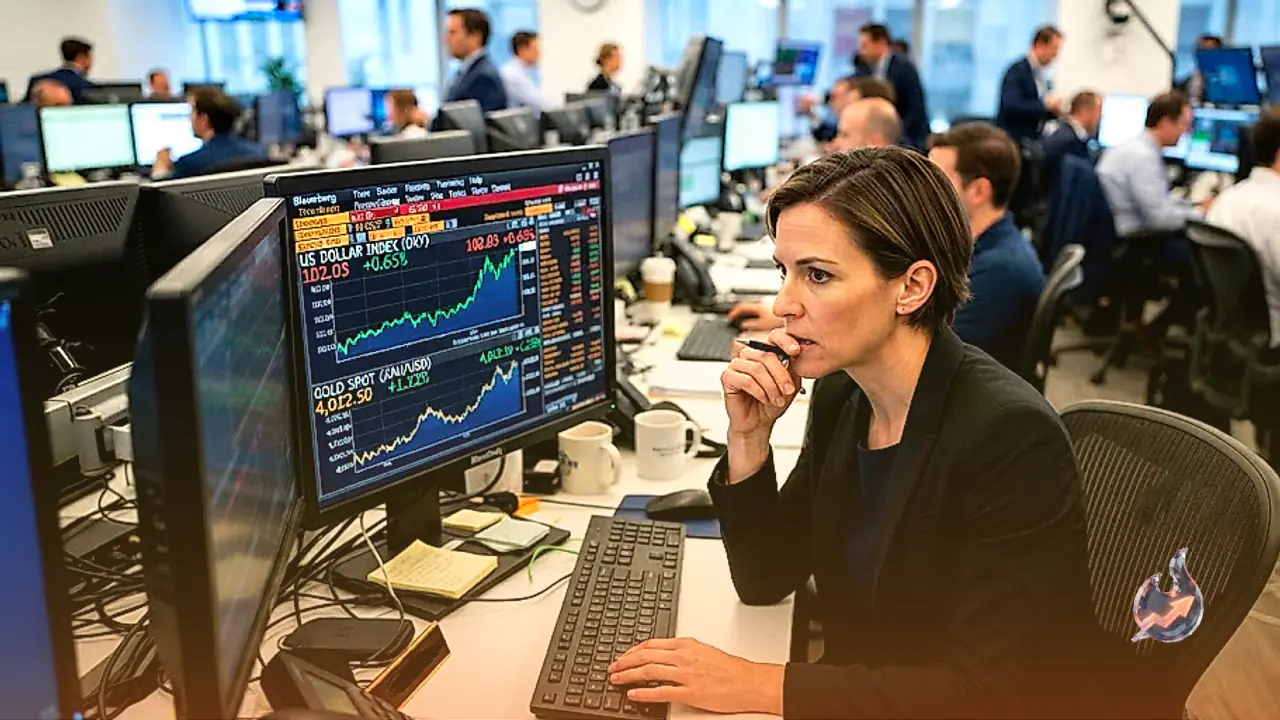

Global financial markets opened the week under a cloud of caution as investors braced for a crucial series of central bank decisions and high-impact economic releases. The widespread risk-averse sentiment provided a boost to safe-haven demand, allowing the Greenback to extend its recent rebound toward multi-day highs. Despite a mixed performance in US Treasury yields, foreign exchange markets saw sustained strength in the US Dollar, which placed notable downward pressure on several rival currencies across Europe and Asia.
US Dollar Index Surpasses 102.00 Barrier Amid Dense Data Calendar
The US Dollar Index (DXY), which tracks the currency against a basket of six major peers, briefly moved above the 102.00 mark, building momentum after Friday's gains. Market participants are positioning themselves ahead of a busy week for US economic indicators. The initial focus centers on the ADP Employment Change weekly figures, providing an updated snapshot of labor market conditions.
Subsequent releases include final Building Permits data, Durable Goods Orders, New Home Sales, and the FHFA House Price Index. Investors will also monitor the Conference Board Consumer Confidence index and the API weekly inventory report on US crude oil stocks. Together, these reports are expected to provide key insights into economic activity and inflation dynamics ahead of upcoming policy decisions by the Federal Reserve.
Sterling Weakens to Four-Day Lows Ahead of UK Retail Inflation Data
Amid the broader slide in risk assets, Cable (GBP/USD) experienced renewed selling pressure, dropping to four-day lows within the 1.3330-1.3320 price band. The British currency remains sensitive to ongoing inflation pressures in the United Kingdom. Traders are now awaiting the upcoming BRC Shop Price Inflation report to gauge whether retail price pressures are continuing to ease or reaccelerate across British retail outlets.
Crude Oil Drops on Middle East Peace Hopes Near $100 Level
Energy markets saw further declines as front-month West Texas Intermediate (WTI) crude futures for December delivery extended Friday's losses. WTI prices briefly slipped toward the psychological $100.00 per barrel mark before stabilizing slightly. The downward momentum in oil prices stemmed from reports of renewed optimism regarding potential US-Iran discussions aimed at resolving conflict in the Middle East, which eased concerns over potential regional supply disruptions.
Gold Reclaims $4,000 Threshold Despite Stronger Dollar
In precious metals trading, spot gold (XAU/USD) snapped a two-day losing streak to reclaim territory above the $4,000 per troy ounce benchmark. The metal demonstrated resilience by bouncing higher even as the US Dollar posted gains and US Treasury yields showed mixed movements. Market observers noted that the drop in crude oil prices helped underpin gold demand by relieving immediate energy-driven inflation anxieties.
Aussie Holds Near Monthly Highs while Yen Gains on Hawkish BoJ
Across Asia, AUD/USD maintained its position above 0.7000 throughout the Asian trading session, remaining near one-month highs established early Monday. A pullback in US bond yields and softer crude prices helped limit the US Dollar's recovery. Furthermore, market expectations of a potential November rate hike by the Reserve Bank of Australia supported the Aussie Dollar, though further gains were restrained ahead of the two-day FOMC meeting beginning Tuesday.
Meanwhile, USD/JPY faced fresh selling interest during Asian hours, stalling a rebound from its lowest level since September 18 recorded on Friday. Declining US bond yields sapped demand for the Greenback, while hawkish signaling from the Bank of Japan bolstered the Japanese Yen. However, downside movement remained contained as market participants hesitated to take aggressive positions before policy announcements from both the Federal Reserve and the Bank of Japan later this week.
Bitcoin Holds Near $80,500 amid Geopolitical Inflation Concerns
In cryptocurrency markets, Bitcoin (BTC) consolidated around the $80,500 level on Monday following three consecutive weeks of downward corrections. Ongoing geopolitical friction in the Middle East has kept volatility elevated in energy markets, nourishing broader inflationary fears and weighing on overall risk appetite across digital asset markets.
Five Major Central Banks Prepare Rate Decisions as US Midterms Approach
This week marks a major turning point for global monetary policy as five of the world's major central banks prepare to announce interest rate decisions. With energy-driven supply shocks keeping global inflation above central bank targets, investors are pricing in potential rate hikes. Concurrently, political attention in the United States is shifting toward the November 3 midterm elections. While markets expect an additional Fed rate hike in December, the battle for control of Congress could alter fiscal policy expectations, reshaping the trajectory of US monetary policy through 2027.