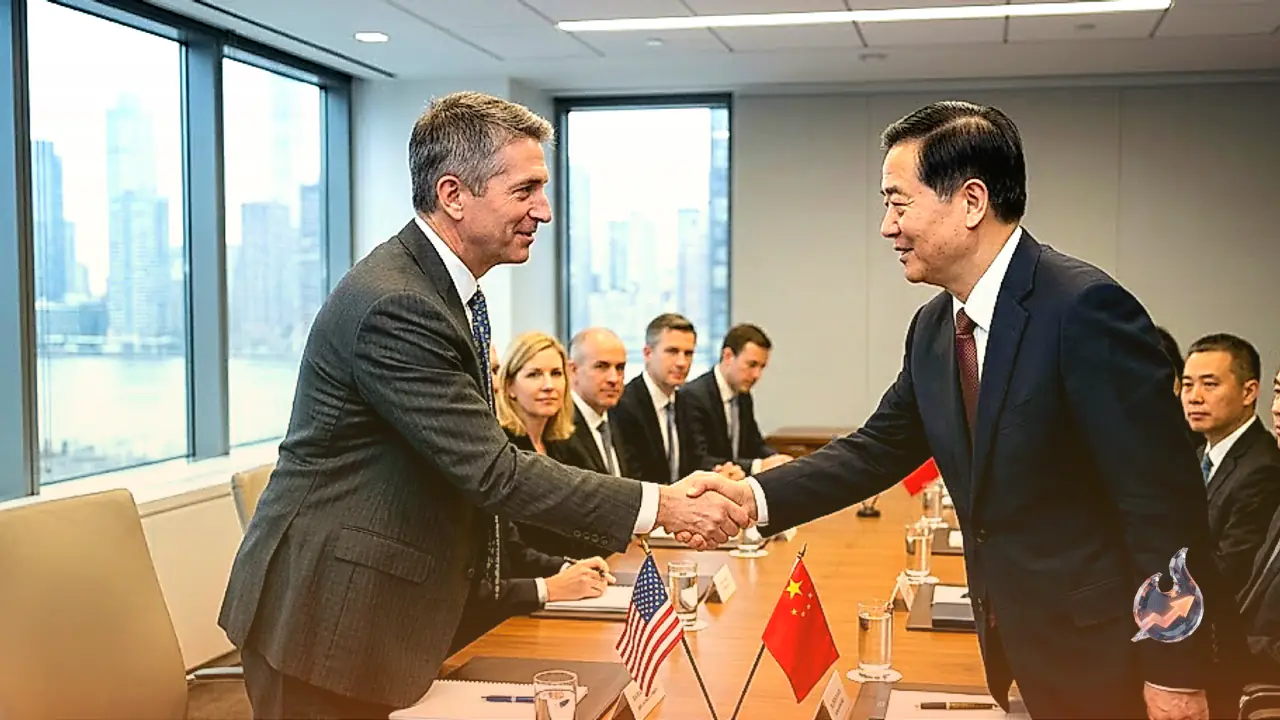














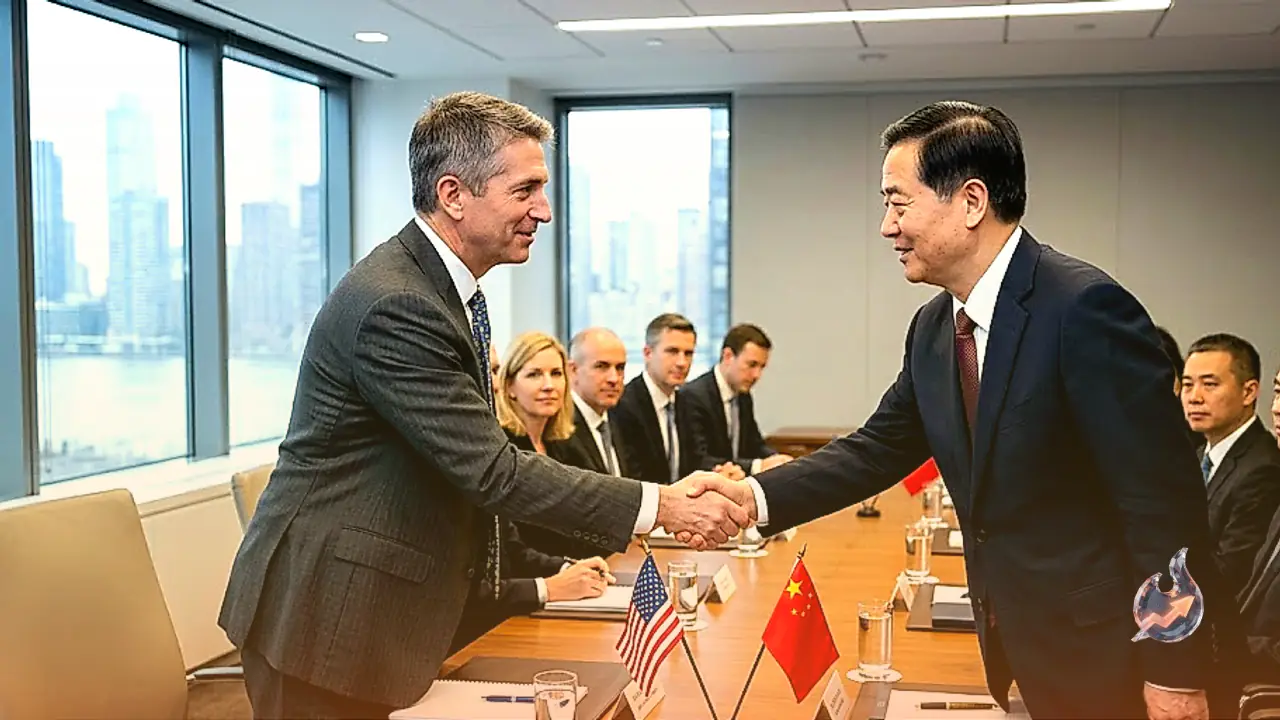

Senior representatives from the United States and China have initiated high-stakes discussions in New York aimed at laying the groundwork for potential accords spanning international commerce, Artificial Intelligence (AI), and critical mineral supply chains. The bilateral consultations are unfolding in advance of an upcoming summit between US President Donald Trump and Chinese President Xi Jinping scheduled for later on Thursday. Negotiations formally began on Sunday at the Manhattan headquarters of JPMorgan Chase, bringing together US Treasury Secretary Scott Bessent and Chinese Vice Premier He Lifeng, alongside active participation from US Trade Representative Jamieson Greer.
Global Market Transmission and the Australian Dollar
The geopolitical exchanges in Manhattan coincided with subtle adjustments across foreign currency desks, where the AUD/USD pair registered a modest decline of 0.04% on the day to trade at 0.7120. Valuations for the Australian Dollar (AUD) remain closely intertwined with multiple domestic macroeconomic indicators and international market drivers. A primary domestic pillar is the interest rate trajectory established by the Reserve Bank of Australia (RBA).
As Australia possesses an extensive natural endowment of commodities, the pricing dynamics of its principal export commodity, iron ore, act as a decisive pricing influence. Concurrently, broader performance within the Chinese economy, Australia's primary commercial customer, exercises structural influence on currency valuations alongside Australia's domestic inflation figures, economic expansion pace, and trade balance metrics. Prevailing market sentiment also exerts direct directional pressure; risk-seeking environments (risk-on) generally offer tailwinds to the AUD, whereas broad-based asset flight toward safety havens (risk-off) tends to dampen demand for the currency.
The Reserve Bank of Australia's Policy Toolkit
The Reserve Bank of Australia (RBA) determines the benchmark cost of borrowing at which commercial banking institutions exchange short-term capital within the Australian financial framework. This cash rate baseline cascades directly across commercial borrowing costs and yields in the national economy. The core monetary mandate pursued by the RBA focuses on anchoring annualized inflation securely inside a targeted corridor of 2% to 3% through systematic adjustments to policy borrowing rates.
When Australian benchmark yields remain elevated relative to comparable rates published by other prominent monetary authorities, the differential typically bolsters demand for the AUD. Conversely, a discount in local policy rates compared with international peers tends to exert downward pressure on the currency. The RBA also maintains capacity to influence systemic credit availability through non-standard balance-sheet actions, notably quantitative easing and quantitative tightening. Structural liquidity additions via quantitative easing historically represent an AUD-negative catalyst, whereas liquidity contractions through quantitative tightening generate AUD-positive momentum.
Chinese Demand Cycles and Australian Trade Balance Drivers
Because China stands as Australia's largest international trade partner, cyclical shifts in Chinese economic health reverberate directly through the valuation of the Australian currency. Robust growth and expanding industrial production across China generate heightened import requirements for Australian raw commodities, finished products, and commercial services. Such expanded purchasing patterns amplify demand for the Australian currency in foreign exchange markets, lifting its overall value. If Chinese economic momentum decelerates or fails to meet consensus estimates, the contraction in material absorption leads to softer currency support, ensuring that Chinese economic indicators consistently generate meaningful volatility across AUD currency pairs.
Iron ore stands as the cornerstone of this bilateral economic relationship, ranking as Australia's most lucrative export product and generating $118 billion in annualized revenue based on 2021 records, with China serving as its primary destination. Consequently, movements in global iron ore benchmark spot prices regularly guide directional shifts for the Australian Dollar. Rising iron ore prices typically stimulate greater cumulative demand for the currency, while downward price corrections tend to soften exchange rates. Furthermore, higher iron ore export realizations directly elevate the likelihood of Australia securing an expanded national trade surplus, another baseline support for the AUD.
The trade balance measures the net capital variance between revenues received from outward national exports and capital expended on incoming foreign imports. If international buyers exhibit robust demand for a nation's export basket, foreign purchasers must acquire domestic currency to settle trade obligations, generating structural appreciation. A positive net trade balance reinforces the value profile of the Australian Dollar, whereas a net trade deficit creates corresponding downward pressure.
FX Session Dynamics and Bank of Japan Policy Normalization
Across regional sessions on Friday, the AUD/USD pair preserved a positive tone for a second consecutive trading day, holding firm above 0.7100 during Asian trading hours as softer yields on US Treasury paper pressured Dollar buyers. Concurrently, hawkish remarks delivered by RBA Governor Bullock heightened market expectations for additional policy rate increases, providing underlying support to the Australian unit. However, persistent policy firmness signaled by the US Federal Reserve, alongside wider geopolitical uncertainties, restrained broader Dollar declines and capped the pair's upward momentum.
In the European trading window, USD/JPY rekindled its upward trajectory, touching two-week peaks near 158.00. The Japanese Yen experienced fresh losses despite a widely anticipated interest rate hike by the Bank of Japan (BoJ) to 1.25% and accompanying hawkish rhetoric from Governor Kazuo Ueda. The BoJ opted to raise its short-term interest rate target to 1.25% from 1.00% via a 7-2 voting outcome, representing another milestone in its ongoing normalization of domestic monetary parameters, entirely in line with market consensus. Governor Ueda affirmed that the monetary policy phase had shifted. Nevertheless, the emergence of two surprise dissenting votes against the rate hike created selling pressure on the Yen.
Precious Metals Strength and Crude Dynamics
Meanwhile, the commodities complex saw gold build upon gains established throughout the latter half of the trading week. Spot gold prices traded with firm positive momentum on Friday, hovering just beneath the $4,400 per troy ounce threshold. The precious metal gathered support from softer international crude oil benchmarks and renewed selling interest surrounding the US Dollar.