


















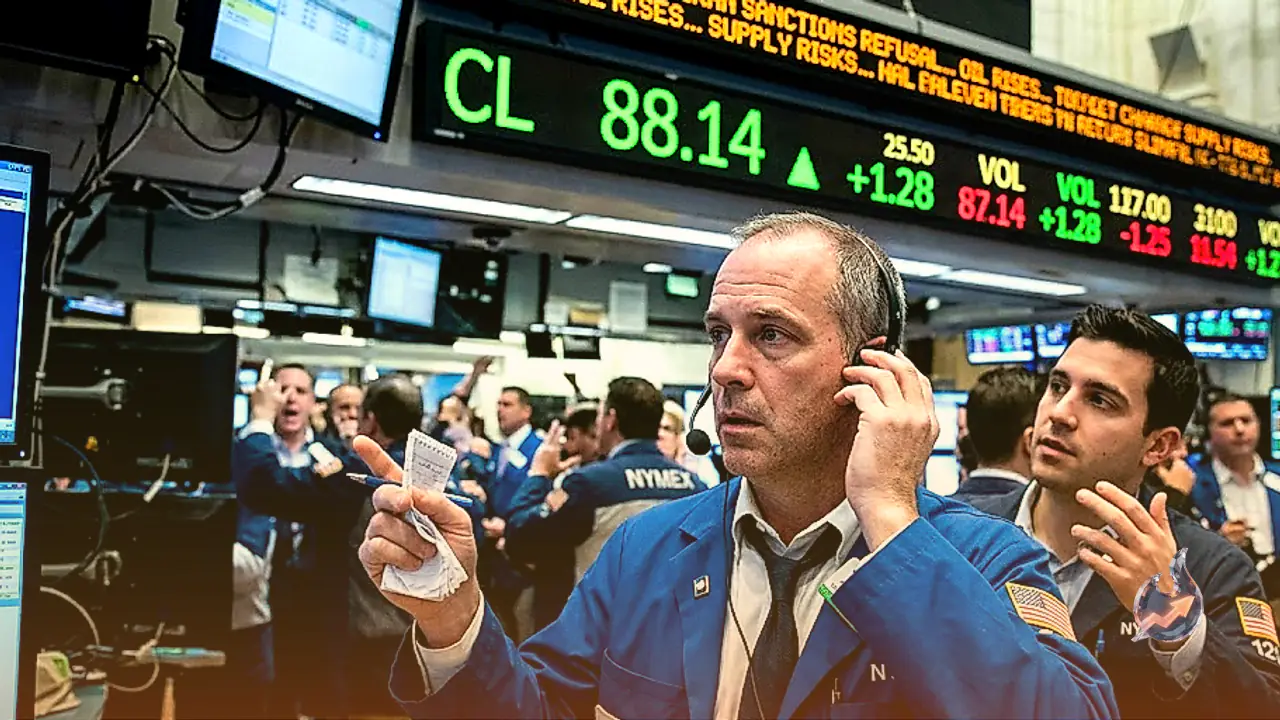

Geopolitical turbulence returned to the center stage of commodity markets as West Texas Intermediate crude advanced toward $88.30 per barrel during Wednesday's early European trading session. The rebound in the primary US oil benchmark gained traction immediately after US President Donald Trump firmly rejected suggestions that Washington would relax sanctions targeting Iran. Market participants are simultaneously positioning themselves ahead of the official petroleum inventory statistics scheduled for publication by the Energy Information Administration.
Stalemate in Diplomacy and Trump's Stance on Tehran
The upward price movement reflects heightened unease following an Axios report indicating that mediation efforts conducted by Qatar between American and Iranian envoys failed to achieve any breakthrough. With negotiators from both nations maintaining rigid postures, the diplomatic impasse has rekindled fears that regional hostility could worsen. Adding to market sensitivity, Trump explicitly refuted reports suggesting he had offered sanction relief and unblocked frozen Iranian assets in exchange for verifiable concessions regarding Tehran's nuclear program.
Market observers note that the persistent lack of diplomatic clarity prevents energy markets from discounting political hazard. Sugandha Sachdeva, founder of New Delhi-based research firm SS WealthStreet, stated that ongoing uncertainty surrounding sanctions relief and negotiations continues to embed a geopolitical risk premium within crude valuations. She pointed out that while improving output could place a ceiling on gains, renewed disruption or escalation would spark another substantial advance.
Weekly Stockpile Builds and Global Supply Dynamics
Counterbalancing the geopolitical tailwinds are domestic inventory dynamics in the United States. Fresh data from the American Petroleum Institute revealed that nationwide crude inventories expanded by 1.019 million barrels during the week ending September 25. While this accumulation reflects continued supply availability, it represents a moderation compared to the previous week's inventory climb of 1.786 million barrels.
The current stabilization follows a steep pullback across benchmark contracts. Analysts at ING observed that crude prices fell sharply earlier in the week, with Brent dipping under $99 per barrel and WTI descending near $89 per barrel. This downward correction was driven by expectations of expanding Saudi shipments, perceived progress in US-Iran dialogue, and an unexpectedly large build in US inventories. The retreat marked Brent's sixth consecutive losing session, representing its longest sustained decline since August 2025 and generating cumulative losses topping 9.5 percent.
Pipeline Resumption and Broader Market Context
On the physical logistics front, significant relief is developing along Middle Eastern shipping arteries. ING highlighted that Saudi Arabia has brought its East-West pipeline back into service and may soon restart loadings from the Yanbu export terminal. Boasting an operational throughput capacity of approximately 7 million barrels per day, this pipeline bypasses the vulnerable Strait of Hormuz, providing an alternative route capable of restoring crude outflows to global consumers over the coming weeks.
Geopolitical narratives, however, remain conflicted. While Trump had previously characterized recent diplomatic communications with Iranian counterparts as very productive, his outright denial of financial concessions quickly counteracted sentiment that Middle Eastern supplies were entirely secure. ING emphasized that despite the recent wave of selling, crude benchmarks remain more than 60 percent higher since the beginning of the year, showing that the market is navigating an elevated price baseline.
Technical Indicators and Live Pricing Structure
From a chartist perspective, WTI continues to defend a constructive foundation on the daily timeframe by holding ground above its 100-day simple moving average and lower Bollinger Band. While this positioning signals persistent dip-buying appetite, upside momentum shows signs of exhaustion as the middle and upper Bollinger bands loom overhead. The Relative Strength Index hovering at 45.9 confirms a neutral regime, indicating momentum loss rather than aggressive distribution.
In terms of specific price thresholds, initial overhead resistance stands at the Bollinger middle band of $93.45, with a higher barrier positioned at the upper band near $101.05. Conversely, immediate support rests at the lower band of $85.80, followed closely by the 100-day moving average at $84.75, where institutional buyers previously stepped in to safeguard the broader structural uptrend.
Live market observations show crude oil trading at $90.94, marking a 1.75 percent increase from its prior settlement at $89.38. The contract maintains a wide 52-week trading span between $54.98 and $119.48. Current technical indicators reveal a 14-period RSI of 47 and an ADX of 24. Key trading parameters identify a central pivot at $90.49, with upside targets marked at resistance levels R1 of $92.41 and R2 of $93.87, while downward cushions are mapped at support tiers S1 of $89.03 and S2 of $87.11.
Fundamental Drivers of the Global Oil Benchmark
West Texas Intermediate represents one of three international crude oil pricing pillars alongside Brent and Dubai. Originating within oilfields across the United States, it is distributed primarily through the Cushing, Oklahoma storage and blending network, a junction widely known as the pipeline crossroads of the world. Because of its light density and minimal sulfur content, refiners prize WTI as a high-grade product that yields premium transportation fuels with low processing complexity.
The valuation of crude oil reflects shifting macroeconomic equilibrium. Accelerating worldwide GDP expansion fuels aggregate consumption, whereas periods of economic stagnation suppress fuel usage. Beyond broad macroeconomic trends, pricing is heavily dictated by decisions made by the 12-nation Organization of the Petroleum Exporting Countries, along with ten allied producers led by Russia, collectively known as OPEC+. When this coalition curbs production quotas, supplies tighten and prices rise. Currency movements also influence demand, as an appreciating US dollar increases purchasing costs for international buyers using foreign currencies.
Cross-Asset Movements in Currencies and Commodities
Financial markets experienced notable volatility across related asset classes during Wednesday's trading. The Australian dollar slumped to a two-month low near 0.6950 against the greenback after softer-than-anticipated core inflation data tempered expectations for rate hikes by the Reserve Bank of Australia. Concurrently, the US dollar remained subdued against the Japanese yen below 157.00, supported by Bank of Japan rate speculation that offset weak factory output data from Tokyo.
Precious metals saw gold consolidate below $4,200 per ounce in Asian dealing after touching an eight-week trough of $4,110, with bullion traders awaiting US private payrolls and consumption expenditure figures. Meanwhile, in decentralized finance, the lending protocol token Aave retreated below $161 following a double-digit percentage surge, as market participants engaged in profit-taking even as founder Stani Kulechov explored potential supply-reduction mechanisms under proposed protocol updates.