














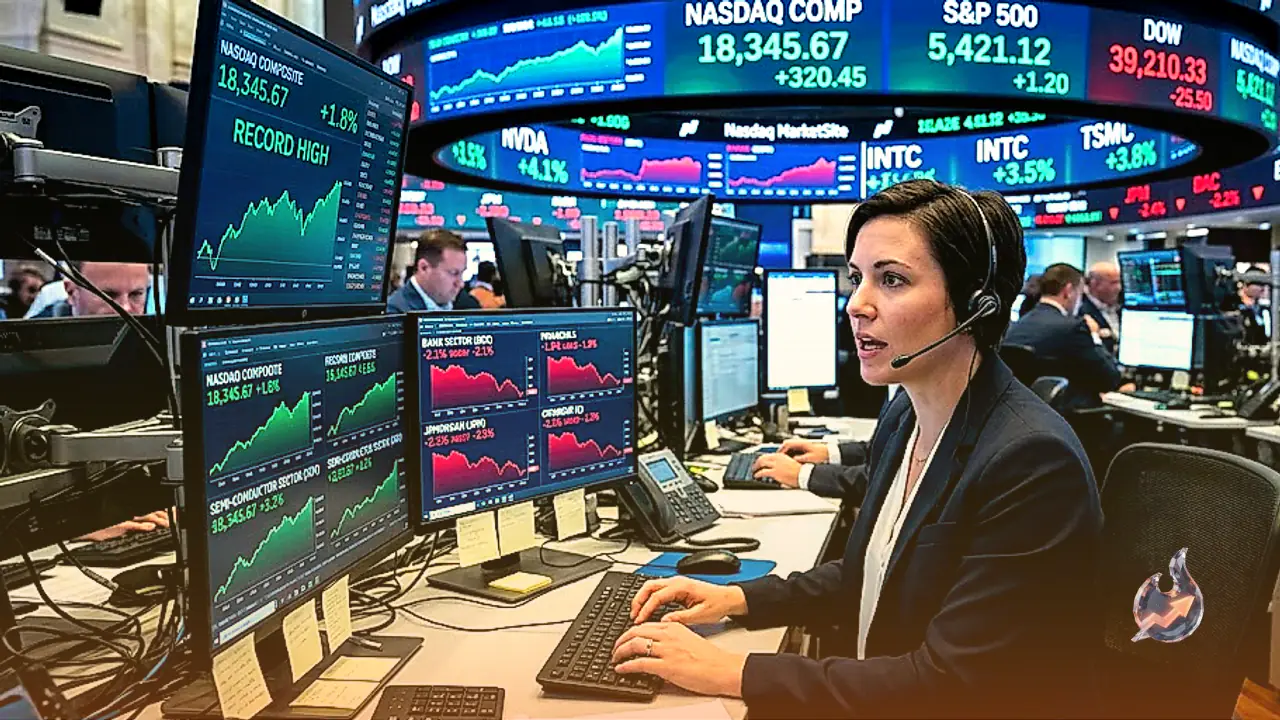

Global equity markets witnessed a pronounced sector rotation that left major United States benchmarks virtually unchanged at the close of trading. Substantial strength across technology and semiconductor shares managed to counterbalance steep declines throughout the banking and financial services sectors. The rotation propelled the Nasdaq Composite to a fresh record peak, while broader indices finished little changed amid swirling macroeconomic and policy developments.
Wall Street Sector Divergence: Tech Surges as Financials Slump
The benchmark S&P 500 closed the trading session effectively flat, shedding a negligible -0.001%. In stark contrast to the broader gauge's muted finish, the technology-dense Nasdaq advanced 0.45%, reaching a fresh all-time high. Investors actively reassessed valuations and earnings prospects across industries, shifting capital heavily toward hardware and software innovators. Equity futures in the United States mirrored this quiet close, holding near flat levels in subsequent trade.
Semiconductors Extend Winning Streak Following Trump's UN Remarks
Chip manufacturers spearheaded the equity advance, with the Philadelphia Semiconductor Index jumping 2.06% to register its sixth consecutive session of gains. This momentum in the semiconductor supply chain coincided with notable commentary from Donald Trump during his address at the United Nations. Trump designated artificial intelligence as "super intelligence" and explicitly pushed back against regulatory measures aimed at controlling or curtailing its technological evolution, reinforcing risk appetite across tech hardware names.
Margin Erosion Worries Spark Sell-Off in Financial Stocks
The optimism surrounding advanced computing stood in sharp contrast to the downturn in financial institutions. Financial shares sank -1.98%, emerging as the primary drag within the S&P 500. Market participants grew increasingly uneasy over the potential for artificial intelligence disruption to compress traditional banking margins and erode transactional fee pools, triggering an exodus from large lending and brokerage institutions.
European Bourses Advance Modestly While UK Equities Pull Back
Across the Atlantic, European stock markets finished mostly in positive territory. The pan-European Stoxx 600 index edged up 0.13%, France's CAC 40 added 0.20%, and Germany's DAX closed up 0.02%. Defying the regional trend, the United Kingdom's FTSE 100 retreated -0.29%. Asian equity trading displayed a fractured performance overnight, reflecting regional divergence and cautious positioning ahead of international political meetings.
Foreign Exchange: Resilient Dollar Pressures Australian Dollar and Japanese Yen
In foreign exchange trading, the United States Dollar extended its broader uptrend, touching a fresh peak since July 30 bolstered by the Federal Reserve's hawkish policy stance. This dollar momentum exerted heavy pressure on the AUD/USD pair during Wednesday's Asian session, pushing it down to test key support near 0.7100. The decline was accelerated by Australia's flash PMI surveys, which revealed manufacturing falling into contraction while service sector growth remained sluggish for a second consecutive month. Markets largely disregarded the conclusion of indirect talks between the United States and Iran, focusing instead on broader trade diplomacy.
Concurrently, the USD/JPY pair hovered around the mid-157.00s in Wednesday's Asian trade, holding close to two-week highs recorded last Friday. Although the Bank of Japan enacted an interest rate hike, its accompanying dovish tone undermined the Japanese Yen. The persistent dollar bid supported the currency cross, even as lingering concerns over potential official currency intervention by Japanese authorities capped further upside momentum.
Bank of Japan Delivers Widely Expected Rate Increase
On the central banking front, the Bank of Japan moved forward with monetary policy normalization by lifting its short-term interest-rate target from 1.00% to 1.25%. The decision passed by a 7-2 vote, matching market expectations that had been priced in over preceding weeks. Despite the benchmark hike, the central bank's tempered communication kept the Yen vulnerable across foreign exchange pairs.
Gold Softens Under Dollar Pressure While Cardano Rallies Over 14%
Commodity trading saw spot gold struggle to maintain momentum following its recent rebound from sub-$4,300 levels, running into renewed selling during Wednesday's Asian session. The dollar's ascent, underpinned by expectations of prolonged higher rates from the Federal Reserve, reduced demand for non-yielding bullion.
Conversely, digital asset markets witnessed robust demand for Cardano (ADA), which climbed above $0.262 following a gain of more than 14% over the course of the week. Bullish sentiment in ADA was reinforced by an uptick in Open Interest, positive derivatives funding rates, and indications of whale accumulation, suggesting that continued buying pressure could pave the way for a test of higher resistance levels.
High-Stakes Trump-Xi Summit Approaches in Washington
Market attention remains tightly fixed on Washington, where United States President Donald Trump is scheduled to meet Chinese President Xi Jinping on Thursday. Following several months of easing bilateral trade tensions between Washington and Beijing, the high-profile summit will provide critical signals on whether the world's two largest economic powers will prolong their commercial truce or enter a renewed phase of volatility.