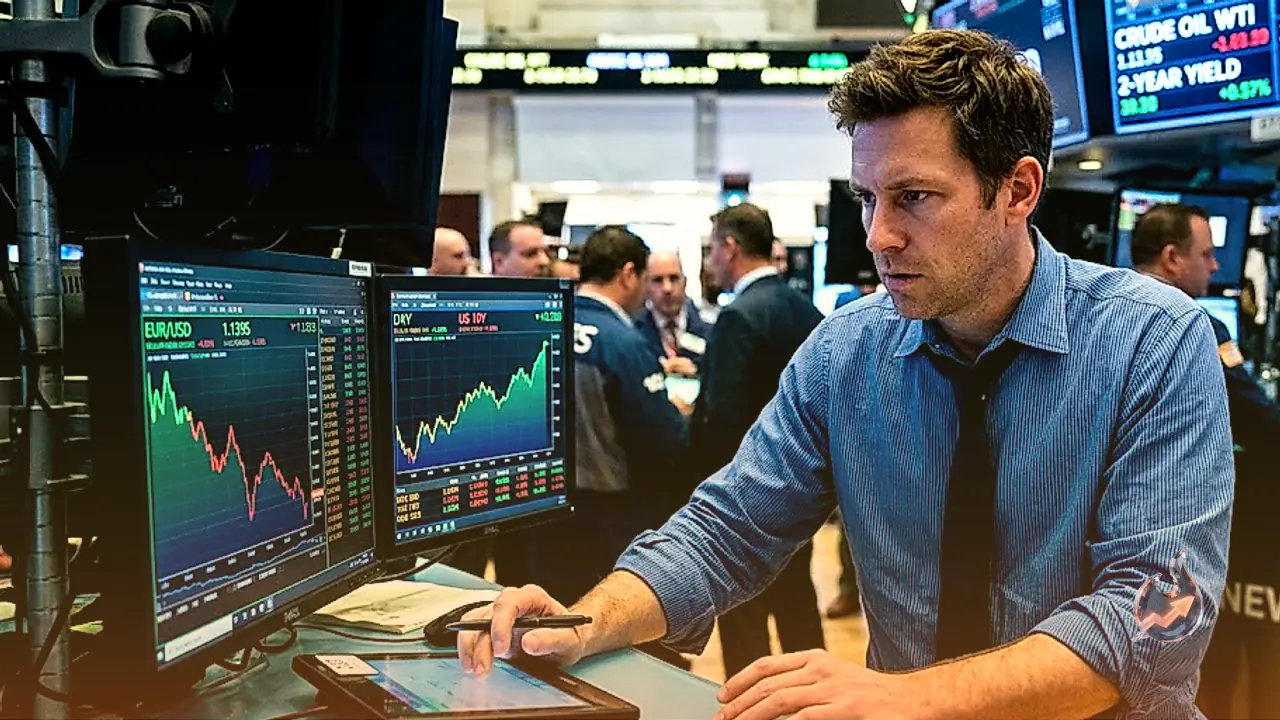















The euro managed a modest uptick as the US Dollar paused its recent advance, yet the single European currency remains firmly on track to register its third consecutive weekly decline. Persistent expectations of a hawkish Federal Reserve alongside elevated US Treasury yields continue to provide strong underlying support for the Greenback. Currency market participants are now turning their attention toward key economic data releases scheduled for next week, including the US PCE inflation report, Nonfarm Payrolls, and the Eurozone HICP inflation numbers, to glean further clues regarding central bank policy directions.
The US Dollar Index (DXY), which gauges the currency's value against a basket of six major international peers, hovered around the 101 mark after climbing to 101.40 on Thursday, marking its strongest performance in nearly two months. Concurrently, the benchmark 10-year US Treasury yield traded close to 5.22%, holding around territory not observed since 2007. According to live market data, the EUR/USD spot rate trades near 1.14, up 0.16% from its prior close of 1.14. Technical indicators show a 14-day RSI of 29 in oversold territory, with the 50-day EMA at 1.15 and the 200-day EMA at 1.16 confirming a long-term downtrend and a prevailing death cross formation.
Mixed Signals from US Consumer Sentiment Data
Friday's batch of economic indicators presented an ambivalent picture of conditions within the United States. The University of Michigan Consumer Sentiment Index rose to 48.1 in September from a previous reading of 47.8, topping consensus market forecasts that had projected 47.6. Complementing this move, the Consumer Expectations Index climbed to 46.3 from 45.8. Nonetheless, inflation expectations remained thoroughly anchored. One-year inflation projections held firm at 4.6%, while the five-year inflation outlook was unchanged at 3.4%.
With consumer readings offering a mixed backdrop, market participants are directing their focus toward forthcoming high-impact releases. These include the Personal Consumption Expenditures (PCE) price index, the ISM Manufacturing Purchasing Managers' Index (PMI), and the Nonfarm Payrolls (NFP) employment report. These metrics will serve as crucial inputs ahead of the Federal Reserve's October policy gathering. According to readings from the CME FedWatch Tool, traders are currently pricing in an estimated 66% probability of another interest rate hike by the central bank.
The Mechanics of Inflation and Currency Valuation
Inflation tracks the broad increase in the cost of a representative basket of goods and services over time. Headline inflation figures are standardly reported as percentage changes on both a month-on-month and year-on-year basis. In contrast, core inflation strips away volatile expenditure categories such as food and energy, which are frequently distorted by seasonal patterns and geopolitical shocks. Core figures represent the primary gauge monitored by economists and targeted by monetary authorities, whose statutory mandates generally aim to stabilize annual inflation around a 2% target.
The Consumer Price Index (CPI) serves as the primary benchmark measuring these temporal changes in consumer costs. When Core CPI accelerates above the 2% objective, central banks typically respond by tightening monetary policy and raising benchmark borrowing costs; conversely, readings below 2% prompt rate reductions. Higher yields generally bolster a domestic currency, as increased interest rates attract foreign capital seeking superior returns. Therefore, persistent price pressures often paradoxically translate into currency appreciation through the mechanism of anticipated policy tightening.
Gold Dynamics in an Era of Elevated Rates
While bullion historically served as a prime hedge against eroding purchasing power during inflationary environments, market behavior in modern cycles reveals a different relationship. Although extreme financial crises still trigger safe-haven flows toward gold, routine inflationary surges prompt central banks to raise lending rates. Higher policy rates create a notable disadvantage for non-yielding bullion by increasing the opportunity cost of holding the metal instead of cash deposits or interest-bearing government debt.
Conversely, declining inflation tends to support gold valuations because subsequent interest rate cuts diminish the yield advantage of cash instruments. Toward the end of the week, gold witnessed modest buying interest, recouping a fraction of its recent losses as the dollar eased slightly and Treasury yields dipped. Nevertheless, bullion continued to trade beneath the critical threshold of $4,300 per troy ounce.
Cross-Asset Movements in Forex and Digital Assets
Across the broader currency sphere, the Australian Dollar (AUD/USD) weakened toward fresh multi-week lows, threatening the 0.7000 handle after sliding beneath its 200-day Simple Moving Average. A rebound in global crude oil prices over two consecutive sessions rekindled inflation anxieties, boosting US yields and strengthening the Greenback enough to overshadow domestic rate hike expectations from the Reserve Bank of Australia. Meanwhile, the Japanese Yen saw USD/JPY retreat slightly from a three-week peak of 159.00 as market participants turned cautious regarding possible currency intervention, even after the Bank of Japan and the Fed each delivered 25-basis-point rate increases in their previous meetings.
In the digital asset space, major cryptocurrencies entered a consolidation phase at the close of the week. Bitcoin managed to steady itself slightly above the $84,000 threshold after trimming prior losses, with Ethereum tracking comparable trajectories. Ripple (XRP) exhibited divergence from the broader pack. Across global financial markets, elevated yields and monetary policy expectations continue to set the tone for asset pricing.