













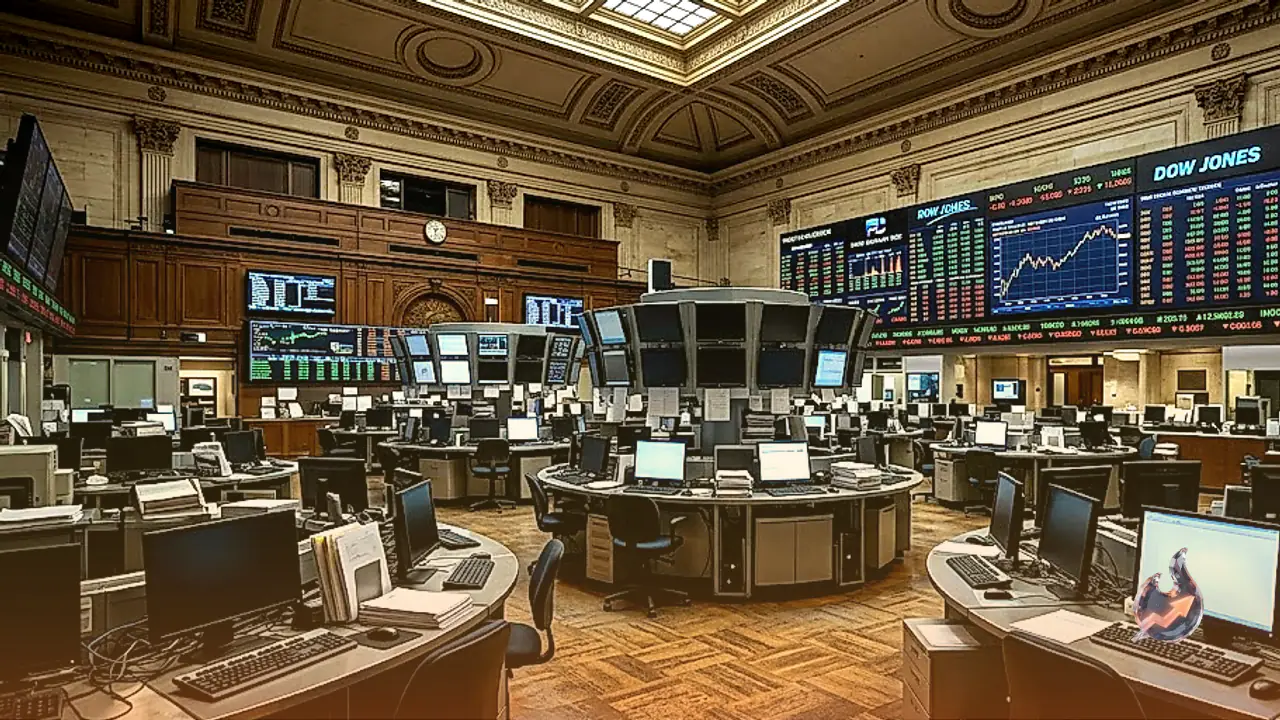

Global equity markets witnessed a constructive tone on Tuesday, with United States equity index futures making upward progress during European trading hours. Market participants are increasingly leaning into expectations that the Federal Reserve will leave its benchmark interest rates untouched during its October policy gathering. That macroeconomic expectation, paired with a solid turnaround across semiconductor and mega-cap technology shares, has provided crucial support after steep portfolio liquidations weighed on Wall Street during the previous week. Dow Jones futures gained 0.38 percent to trade in the vicinity of 52,380, while S&P 500 futures moved up 0.13 percent to linger near 7,740. In contrast, tech-heavy Nasdaq 100 futures slipped by 0.12 percent to hold around 29,690.
Monday Wall Street Recap and Equity Benchmark Performance
The bounce in futures follows an uneven opening session to the trading week in New York. On Monday, the Dow Jones Industrial Average finished fractionally lower by 0.07 percent during regular hours. However, broader risk appetite remained resilient, enabling the S&P 500 to climb 0.41 percent and the Nasdaq Composite to advance by 1.11 percent. That performance marked a decisive rebound from the prior week's heavy drawdown, which was sparked by escalating market anxieties regarding the massive capital commitments and funding structures required for artificial intelligence buildouts.
The recovery on Monday was spearheaded by the semiconductor sector alongside several mega-cap titans. Chip designers and hardware specialists, including Micron, Nvidia, and SanDisk, posted visible gains alongside consumer and technology leaders such as Amazon and Tesla. This rebound illustrates how swiftly buyers stepped in to accumulate core growth names following short-term price consolidations.
Earnings Season Intensifies: Key Tuesday Corporate Reports
Market attention is now pivoting squarely toward an exceptionally active corporate reporting calendar. Institutional desks are bracing for third-quarter financial releases on Tuesday from major corporations operating across streaming entertainment, aerospace, transportation, and industrial manufacturing. Companies scheduled to disclose their numbers include Netflix, General Motors, United Airlines, General Electric, and Raytheon Technologies.
These balance sheets will provide indispensable insight into consumer spending resilience, travel activity, industrial demand, and the impact of financing costs on corporate operating margins. Forward guidance from these corporate leaders is expected to establish trading ranges across several primary economic sectors over the coming weeks.
The Scientific Framework and Technical Scope of Artificial Intelligence
The secular foundation underpinning this market cycle remains artificial intelligence, an academic discipline designed to reproduce human cognitive abilities, logical analysis, perception, and complex pattern recognition within computational machines. Often designated by the shorthand AI, the discipline is an umbrella structure encompassing several distinct scientific sub-domains. These include artificial neural networks, predictive analytics or machine learning, symbolic reasoning, deep learning architectures, natural language processing, speech recognition mechanisms, visual image processing, and rule-based expert systems.
The ultimate milestone envisioned across this scientific landscape is the realization of artificial general intelligence, commonly designated as AGI. The concept represents a machine architecture capable of resolving arbitrary, novel problems across diverse disciplines without requiring prior, specialized algorithmic training for each discrete challenge.
Current Commercial Use Cases: Generative Models to Predictive Enterprise Platforms
In contemporary commercial practice, artificial intelligence is deployed across a vast array of consumer and enterprise workflows. The most widely visible segment comprises generative AI solutions that leverage extensive training on large language models (LLMs) to process and answer complex text-based user queries. Well-known examples include the ChatGPT system and the Google Bard platform. In graphic design and visual creative fields, Midjourney functions as a dedicated application capable of generating entirely original artistic imagery based on user-supplied text descriptions.
Beyond generative text and imagery, AI systems frequently harness probabilistic analytics to evaluate risks and profile behavioral attributes. In credit underwriting, Upstart operates an AI-enhanced credit scoring framework that gauges applicant creditworthiness by evaluating broad online footprints covering occupational history, wealth markers, and associated relationship patterns. In biotechnology, researchers apply AI engines across immense academic databases to identify prospective pharmaceutical compounds before laboratory synthesis. Furthermore, major consumer platforms such as YouTube, Spotify, and Facebook rely continuously on automated machine learning pipelines to curate and recommend personalized audio, video, and social feeds derived from user consumption habits.
Infrastructure Enablers: Nvidia, Palantir, and Microsoft
Within financial markets, semiconductor designer Nvidia (NVDA) is widely categorized as the quintessential pick-and-shovel provider of the ongoing technological transition. The enterprise engineers the specialized graphics processing units and compute platforms that software developers depend upon to train and operate modern AI models. Because no major computational model can function without specialized hardware, Nvidia holds an indispensable commercial position.
In enterprise software, Palantir Technologies (PLTR) maintains a prominent position in big data analytics. The company holds extensive operational agreements with the United States intelligence establishment, which deploys the proprietary Gotham platform to process complex intelligence data, extract investigation leads, and detect behavioral patterns. Palantir's Foundry platform is simultaneously utilized by private corporate clients to monitor internal employee trends, structure customer interactions, execute predictive modeling, and identify systemic operational anomalies. Meanwhile, technology giant Microsoft (MSFT) has secured a significant equity interest in private ChatGPT developer OpenAI, directly infusing that machine intelligence technology into its Bing search architecture.
Valuation Metrics and Historical Bubble Parallels
Following the public launch of ChatGPT in the closing months of 2022, equity valuations across AI-exposed businesses surged rapidly. Nvidia, for example, gained more than 200 percent within just six months of the platform's public debut. That meteoric rise prompted widespread questions across Wall Street regarding whether the technology sector was inflating an unsupportable speculative bubble.
Prominent investor Stanley Druckenmiller, who had amassed significant investment stakes in both Nvidia and Palantir, offered historical perspective on market exuberance by pointing out that structural asset bubbles do not conclude after a mere six-month period. Druckenmiller observed that if public excitement surrounding AI were indeed developing into a genuine speculative bubble, elevated valuations would likely persist for at least two and a half years or longer, closely mirroring the duration of the Dot-Com bubble witnessed during the late 1990s.
By mid-2023, empirical valuation metrics indicated that markets had not reached late-stage bubble conditions. Although Nvidia traded at 27 times its forward sales estimates during that timeframe, Wall Street analysts were factoring in unprecedented, compounding revenue expansion trajectories. Furthermore, while the Nasdaq 100 traded at roughly 60 times earnings at the absolute apex of the late-1990s Dot-Com bubble, the same technology index stood at a far more restrained 25 times earnings in mid-2023.
Currency Markets: Australian Dollar and Yen Adjustments
In foreign exchange markets, insights provided by New Delhi-based forex analyst Akhtar Faruqui highlight notable currency movements across Asian trading. The Australian Dollar gained traction against the US Dollar, with AUD/USD firming toward the 0.7000 threshold on Tuesday. That advance was encouraged by improving risk appetite and a temporary halt in the greenback's upward momentum, although prevailing geopolitical tensions and investor caution before major tech earnings reports may cap further upside.
Concurrently, the USD/JPY cross exhibited steady behavior around 158.50 during Asian trading hours. Currency traders opted for a defensive posture ahead of Japan's upcoming National Consumer Price Index inflation figures scheduled for release on Friday. The pair continues to draw underlying support from relatively elevated United States debt yields, which sustain demand for the dollar against the Japanese Yen.
Debt Yields, Gold Pressure, and NEAR Protocol Crypto Movements
Fixed income and precious metals markets also reflected shifting macroeconomic expectations. Gold declined to approximately $4,120 during European hours, experiencing renewed selling pressure from stabilizing sovereign debt yields and climbing crude oil benchmarks. US Treasury yields showed signs of recovery as hyperscaler technology enterprises prepared to disclose their quarterly numbers. The benchmark 10-year US Treasury yield stood down 0.35 percent near 5.13 percent, having notched a 1.2 percent advance during the preceding Monday session.
In the digital currency ecosystem, NEAR Protocol registered a price decline of approximately 2 percent on Tuesday, extending an identical 2 percent decrease seen the prior day. Despite this near-term price softening, institutional participation has remained strong. The Bitwise NEAR-focused Exchange Traded Fund recorded more than $5 million in fresh net capital inflows on Monday, demonstrating sustained institutional accumulation even amid broader market consolidation.