













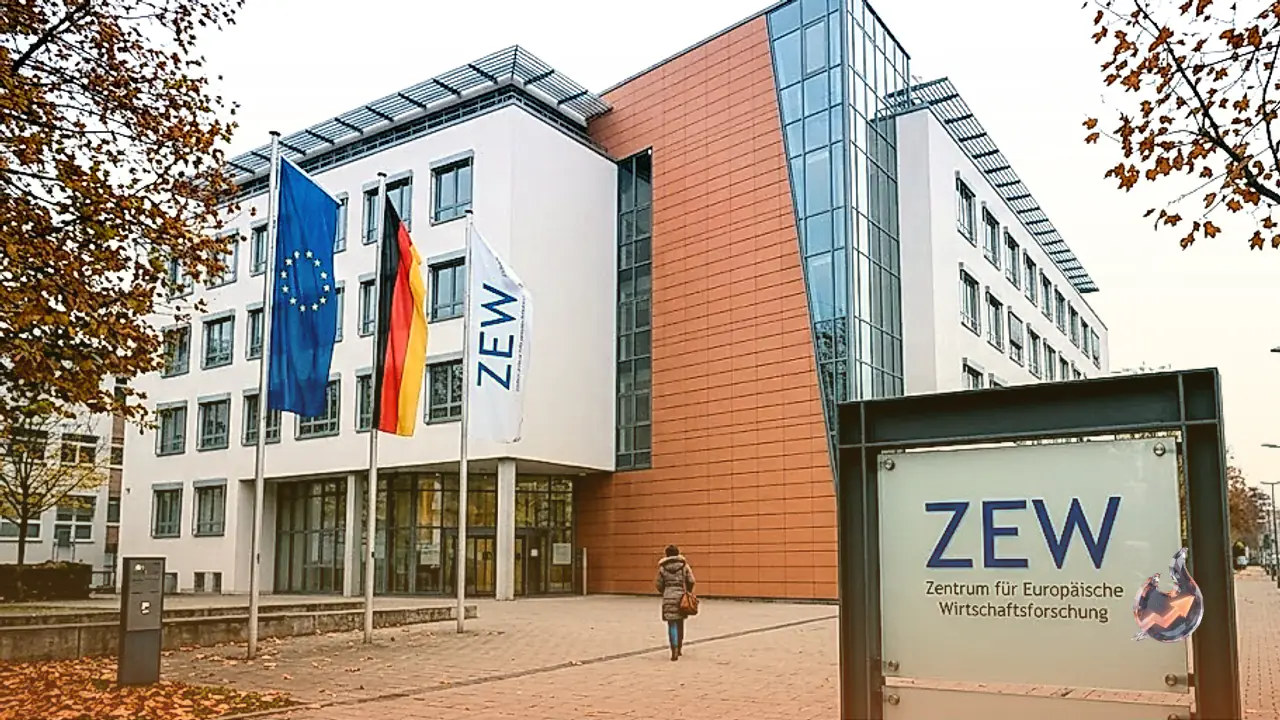

Confidence regarding Germany's broader financial trajectory weakened noticeably as the latest economic survey pointed to growing caution among market specialists. According to fresh data released by the ZEW Leibniz Centre for European Economic Research, the Economic Sentiment index for Germany fell sharply to 28.1 in October. The print missed the consensus estimate of 32.0 by a wide margin and reflected a steep retreat from the 34.7 recorded in September. The marked decline underlines lingering anxieties over whether Europe's cornerstone industrial economy can regain meaningful upward momentum in the medium term.
Current Business Conditions Show Surprising Recovery
In contrast to the deteriorating future expectations, respondents reported a perceptible improvement in their assessment of prevailing business reality. The ZEW Current Situation sub-index advanced to -35.9 in October, rising from -47.1 recorded in the prior release. Market projections had looked for a more modest recovery toward -45.0, meaning the realized figure topped expectations significantly. While the indicator remains in deeply negative territory, signifying that current commercial conditions are still viewed as broadly unfavorable, the notable bounce suggests that the pace of immediate deterioration has at least decelerated.
Foreign Exchange Dynamics Across Asia and Europe
Currency desks witnessed mixed action across major crosses as participants digested macroeconomic updates from Europe and shifting risk sentiment globally. The Australian Dollar gathered upside traction against the US Dollar, advancing toward the 0.7000 threshold during Tuesday trading in Asia. Support for the pair stemmed from a mild improvement in market tone alongside a temporary pause in the greenback's broader rebound. However, persistent geopolitical risks and general wariness ahead of critical corporate earnings from artificial intelligence tech leaders appear likely to cap further advances.
US Treasury Yields Influence the Japanese Yen
Trading in the US Dollar versus the Japanese Yen remained comparatively subdued, holding near 158.50 through Tuesday's Asian hours. Currency investors largely opted to stay sidelined ahead of Japan's upcoming National Consumer Price Index inflation figures scheduled for publication later this week on Friday. Sustained strength in United States government debt yields continued to supply underlying support to the greenback against its Japanese counterpart. The benchmark 10-year US Treasury yield pulled back roughly 0.35 percent to stand near 5.13 percent, following an advance of 1.2 percent posted during Monday's trading session.
Gold Faces Selling Pressure Amid Elevated Yields
The precious metals sector encountered noticeable headwinds during European trading, with gold retreating toward 4,120 dollars. Increased selling pressure coincided with firming United States sovereign bond yields and firmer crude oil prices. Debt markets have experienced volatility as major American hyperscalers prepare to release third-quarter earnings reports in the near term. With yields on benchmark sovereign paper holding around elevated territory, non-yielding bullion has struggled to retain strong speculative bids, triggering defensive positioning among commodities traders.
NEAR Protocol Softens Despite Sustained ETF Inflows
Within the cryptocurrency sector, NEAR Protocol traded lower by nearly 2 percent on Tuesday, extending an identical 2 percent loss suffered during the previous session. Despite the subdued token valuation, underlying institutional participation displayed resilience. Bitwise's NEAR-focused exchange-traded fund recorded fresh net inflows exceeding 5 million dollars on Monday. The divergence between spot price softness and continuous institutional allocations highlights persistent long-term capital interest in the layer-one blockchain ecosystem despite broader digital asset consolidation.