














Canada's broader economy stands at a critical juncture where an apparent resurgence in headline inflation is colliding with deep underlying economic fragility. The release of September's consumer price data, showing the headline Consumer Price Index climbing to an annual rate of 3.1%, immediately triggered speculation across financial circles that monetary tightening would resume. However, peeling back the surface layers of the report reveals an economic dynamic defined far more by global commodity gyrations than by domestic consumer overheating, complicating the policy path for the nation's central bank.
Policymakers currently confront an uncomfortable combination: rising energy costs, a deteriorating domestic employment picture, and an uneven, fragile economic recovery. While bond traders and money markets rapidly repositioned portfolios for tighter borrowing conditions, a comprehensive examination of the fundamental indicators demonstrates why central bank officials have substantial justification to proceed with caution. Hiking policy rates to combat external supply-side price spikes risks damaging already beleaguered domestic activity without altering international supply dynamics.
The Gasoline Wedge Behind Headline Inflation Accelerations
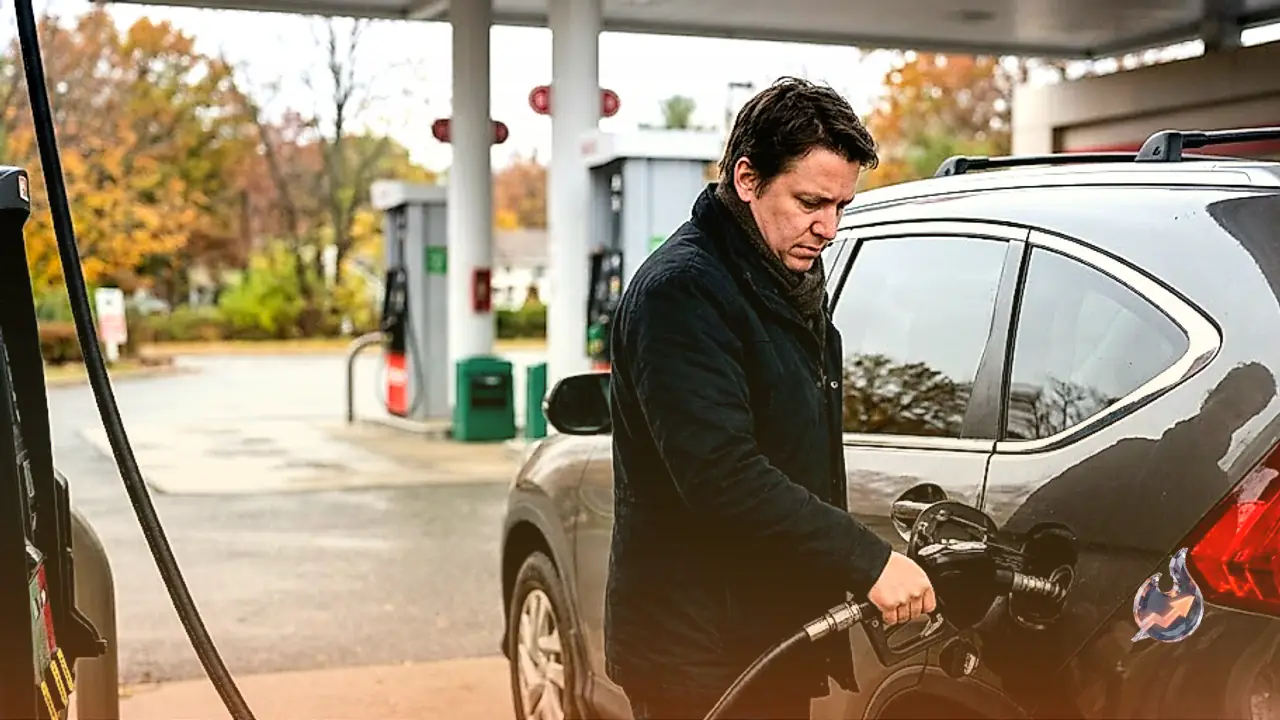
A granular breakdown of the September price index demonstrates that headline acceleration was overwhelmingly driven by automotive fuels. Gasoline prices surged by 27.8% on a year-over-year basis, reflecting the direct transmission of elevated global crude oil valuations to local service stations. Because personal transportation represents an unavoidable expenditure for millions of Canadian households, this rapid spike instantly elevated the aggregate inflation reading, masking relative stability across the wider consumption basket.
When fuel and energy products are stripped out of the calculation, inflation trends paint a strikingly different reality. The inflation rate excluding energy stood at approximately 2.2% year-over-year, settling comfortably close to the Bank of Canada's 2% operational target. Furthermore, essential retail grocery prices advanced at a modest annual pace of just 1.7%, offering concrete proof that price pressures have not contaminated core everyday household budgets in an across-the-board fashion.
The central bank's preferred core inflation gauges strongly validate this contained view of underlying price changes. The CPI-median indicator settled at 1.9% year-over-year, while the CPI-trim gauge registered at 1.8% year-over-year. Both measures remain entirely below the central bank's 2% midpoint objective. These core readings dismantle claims of an entrenched, demand-driven inflationary cycle, indicating instead that domestic pricing pressure remains well within historical bounds.
The Limits of Monetary Policy Against Global Commodity Pressures
Understanding the fundamental driver of price acceleration is paramount when formulating interest rate policy. Traditional monetary tightening acts by suppressing aggregate domestic demand. Higher interest rates elevate debt servicing expenses, curtail residential construction, squeeze business balance sheets, and dampen discretionary retail expenditures. However, an increase in domestic borrowing benchmarks has zero direct ability to modulate global crude supply, geopolitical shipping constraints, or international cartel quotas.
In spite of subdued core readings, financial markets experienced a dramatic shift in rate expectations following the data release. Pricing in overnight index swaps and short-term debt markets caused the implied probability of a 25-basis-point rate increase at the Bank of Canada's upcoming October 28 policy meeting to skyrocket to approximately 80%, up sharply from roughly 30% prior to the release of the September data. Such an adjustment would move the overnight policy rate from its current standing of 2.25% to 2.50%.
This pricing recalibration stems from market anxiety that prolonged increases in transportation overhead will gradually permeate other sectors. Even when price shocks initiate strictly at the fuel pump, elevated freight expenses can eventually ripple through manufacturing supply chains, commercial trucking networks, retail wholesale distributions, and general consumer expectations, creating broader secondary price adjustments over time.
Conflicting Economic Views and the Dilemma for Rate Setters
Central bank leadership has publicly recognized the potential dangers posed by persistent oil market imbalances. Speaking to reporters on Saturday in Bangkok, Bank of Canada Governor Tiff Macklem observed: "If Oil prices stay around $100, we expect inflation to gradually drift up from where it is today: three per cent." Macklem's observation highlights the governing council's concern that persistent energy price pressures could eventually migrate into broader business pricing strategies and wage negotiations, embedding higher structural costs across the country.
Market strategists have articulated the justification for taking preemptive tightening measures. Royce Mendes, Managing Director and Head of Macro Strategy at Desjardins, noted that central bankers can no longer look through the inflationary impact of high energy prices. Mendes explained that businesses have endured elevated input costs for a prolonged duration, making broad-based consumer price increases an imminent threat. This perspective frames an immediate interest rate increase as an essential preventive maneuver designed to snuff out secondary inflation before it infects general business behavior.
Yet, while the potential risk of broader spillover remains a valid theoretical concern, empirical confirmation of widespread price increases remains conspicuously absent from current economic metrics. Rather than coping with excessive domestic demand, the broader economy is actively struggling with declining momentum.
Labour Market Contraction and the Burden of Rising Bond Yields
The domestic labour market offers the most compelling evidence against immediate monetary tightening. Statistics showed an abrupt decline of approximately 68,000 jobs during the month of September. A sharp monthly contraction in aggregate employment is wholly inconsistent with an overheated economy driven by excess consumer spending. Imposing additional monetary restrictions on an economy shedding employment risks tipping vulnerable sectors into outright contraction.
Furthermore, financial conditions have already tightened substantially on their own accord. Government bond yields in Canada have pushed steadily higher, tracking shifts in international fixed income sentiment. Because sovereign bond yields serve as the benchmark for real-world borrowing, market yields have pushed up mortgage rates, commercial loans, and institutional debt costs without requiring any formal decree from central bank policymakers.
Claire Fan, Senior Economist at Royal Bank of Canada (RBC), highlighted the necessity of caution under these conditions. Fan noted that the fragile economic recovery remains the primary counterweight to heightened inflation risks, advocating for a cautious stance from the central bank as elevated bond yields already tighten credit access for both households and businesses. If central bankers proceed with a rate hike on top of already rising bond yields, highly indebted households facing mortgage renewals could face severe financial retrenchment.
The October 28 Meeting as a Definitive Policy Crossroads
The scheduled October 28 rate decision represents an acute assessment of how the Bank of Canada navigates an external energy price shock during a domestic economic slowdown. Although money market participants have heavily priced in a 25-basis-point hike, the underlying economic justification remains far less convincing than the 3.1% headline figure suggests.
Opting for a rate hike would demonstrate central bank determination to keep long-term inflation expectations anchored, signaling zero tolerance for energy-driven wage-price spirals. It would also reassure international currency markets of institutional commitment to defending the 2% inflation mandate.
Conversely, holding the policy rate unchanged at 2.25% would not indicate policy complacency. With core metrics like CPI-median at 1.9% and CPI-trim at 1.8%, and the labour market having lost 68,000 positions, policymakers possess overwhelming statistical evidence that domestic demand remains weak. The central bank could easily maintain its current posture while issuing strict forward guidance outlining readiness to act should non-energy prices accelerate.
Ultimately, the critical analytical test rests on separating inflation that is already widespread from inflation that is merely feared. As it stands, Canada's inflationary resurgence is fundamentally a story of volatile gasoline prices. Whether it transforms into an era of tighter monetary policy depends entirely on whether policymakers view global commodity spikes as a legitimate trigger to squeeze an already strained domestic economy.
Broad Financial Market Backdrop: Currencies, Metals, and Crypto
Developments across international financial markets reflect this identical tension between cautious sentiment and macroeconomic data sensitivity. In foreign exchange trade, the AUD/USD pair showed resilience during Asian trading on Tuesday, firming toward the 0.7000 threshold amid a modest reprieve in the US Dollar rally, though upcoming tech earnings reports and geopolitical developments capped aggressive upside.
Concurrently, the USD/JPY currency cross held steady near 158.50 in Asian hours on Tuesday. Currency participants largely paused ahead of the impending release of Japan's National Consumer Price Index later in the week, with elevated US Treasury yields providing baseline support for the US Dollar. In commodities, spot Gold (XAU/USD) softened for a third consecutive trading session on Tuesday, though overall declines remained measured as traders tracked Middle Eastern geopolitical developments and international crude oil movements.
In digital asset markets, Bitcoin maintained valuation levels above $81,000 on Tuesday, echoing subdued conditions across the digital ecosystem. Alternative tokens displayed lock-step pricing behavior, with Ethereum trading under $2,400 and Ripple changing hands below $1.30. Across all asset categories, global trading desks are expressing a unified narrative: risk appetite exists, but it remains exceptionally selective, cautious, and highly vulnerable to shifting macroeconomic policy signals.