














The Japanese Yen struggled to hold early session gains against the US Dollar on Monday as disappointing economic growth metrics from Tokyo fueled uncertainty over the Bank of Japan's monetary policy path. The USD/JPY currency pair recovered from an intra-day trough of 159.36 to trade around 159.56, remaining down 0.15% on a daily basis. A surprise stagnation in third-quarter output has forced market participants to re-evaluate expectations for a potential interest rate hike at the central bank's upcoming December meeting.
Surprise GDP Shrinkage Dampens Bank of Japan Policy Tightening
Preliminary estimates released by Japan’s Cabinet Office showed that real gross domestic product registered zero growth during the July-September quarter. The flat performance missed consensus expectations of a 0.1% quarterly expansion, slowing dramatically from the 0.4% advance recorded in the prior three-month period. On an annualized basis, the economy contracted by 0.1%, sharply defying forecasts for a 0.4% expansion and reversing from a revised 1.4% gain in the second quarter.
The weaker economic pulse casts doubt on whether the Bank of Japan will proceed with further borrowing cost increases before the end of the year. Last week, Bank of Japan official Toichiro Assada cautioned that additional monetary tightening could place unintended friction on economic activity and underlying price pressures. On Monday, board member Hajime Takata emphasized the need for agile and data-dependent actions, providing little clear commitment regarding the December policy rate decision.
US Dollar Strength and Foreign Exchange Dynamics
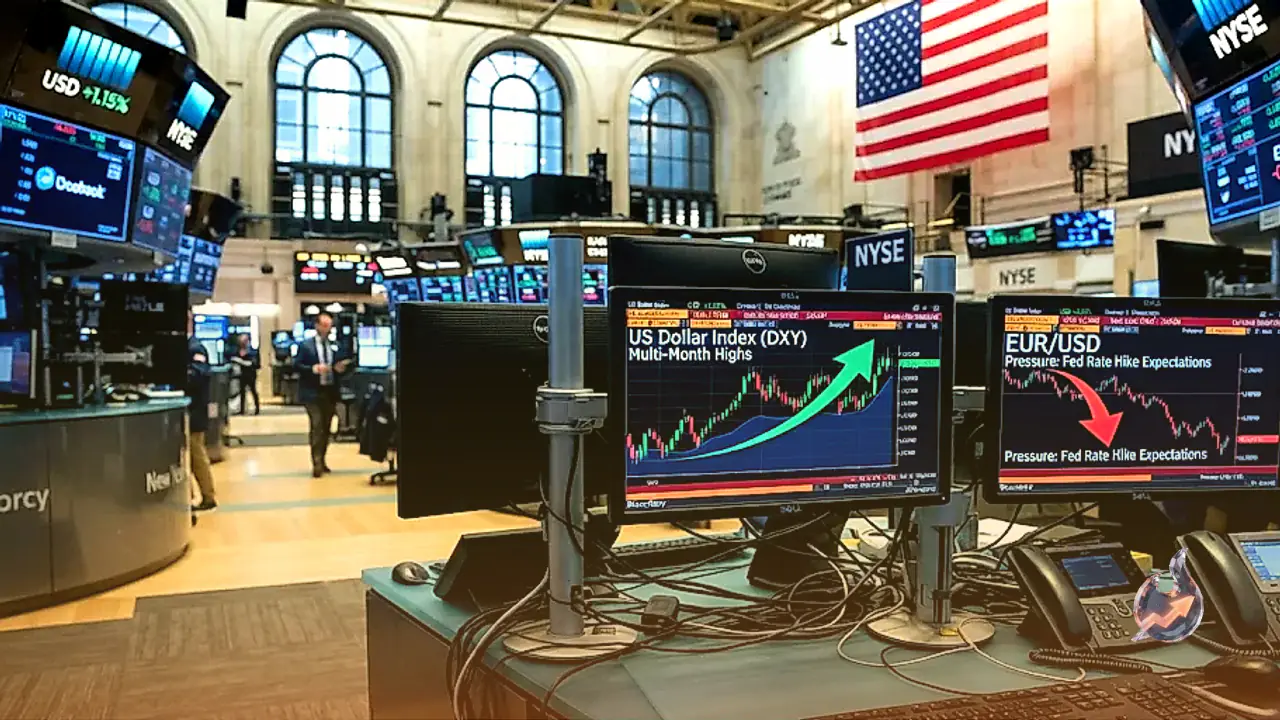
While economic fundamentals in Tokyo falter, the US Dollar continues to draw fundamental support from firm domestic inflation readings and hawkish signals from Federal Reserve officials. Sitting near 19-month highs, the Greenback remains bolstered by firm market expectations of elevated policy rates in the United States. Although potential currency intervention by Japanese authorities has limited steeper declines in the Yen, the broader interest rate differential keeps USD/JPY firmly supported above key threshold levels.
Commodities and Overseas Currency Developments
Spillover effects from Asian economic data were evident across other major currency pairs. The Australian Dollar traded defensibly below the 0.6800 handle after China’s October retail sales and industrial production metrics fell short of market projections. Renewed geopolitical tensions involving the United States and Iran further weighed on risk sentiment, keeping commodity-linked currencies on the backfoot against a surging US Dollar.
In precious metals, spot Gold extended its downside trajectory, slipping below $3,850 per ounce to mark its lowest valuation since early October 2025. Persistent expectations of sustained US Federal Reserve tightening alongside broader geopolitical developments in the Middle East have elevated US Dollar yields, denting non-yielding bullion demand.
Cryptocurrency Outflows and Broader Financial Market Indicators
Digital assets faced heightened selling pressure, with Bitcoin trading below $65,200 on Monday after touching a low of $62,006 last week, a level last witnessed in mid-July. Institutional outflows remained pronounced, as spot Bitcoin exchange traded funds recorded a second consecutive week of capital redemptions exceeding one billion dollars.
Across equities and fixed income markets, broader risk indicators showed underlying stress despite resilient major benchmark indices. US Treasury yields experienced their sharpest single-week surge in more than two years. Concurrently, Nvidia registered its steepest weekly drop since the April 2025 tariff selloff, while gold closed at its lowest level in over twelve months, highlighting growing cross-asset repositioning.