














Infrastructure development firm PNC Infratech has emerged as a top investment pick in the March assessment, with market projections pointing toward an upside potential of as much as 42%. The positive outlook is supported by appealing stock valuations, a robust execution track record, and a sizable order pipeline that provides steady operational visibility over the medium term. Accelerated government capital spending on road networks and tightening procurement standards are expected to directly benefit organized construction contractors.
Order Book Breakdown And Multi-Year Revenue Visibility
As of the end of December 2022, the order book of PNC Infratech stood at a solid Rs 17,842 crore, representing three times its revenue for the financial year 2022. Road infrastructure contracts form the core of this backlog, commanding a 65% share across both Engineering, Procurement, and Construction (EPC) contracts and Hybrid Annuity Model (HAM) projects. The remaining 35% of the total order book consists of water-related infrastructure initiatives.
This backlog structure secures clear revenue visibility for the next two to three years. Operational forecasts estimate a healthy revenue compounded annual growth rate (CAGR) of 18% over the period spanning FY22 to FY25E. On the intake front, the company projects fresh order inflows ranging between Rs 8,000 crore and Rs 10,000 crore in FY23E, with similar annual inflows expected during FY24E as state and central project tendering continues.
Highway Momentum And Tightened NHAI Bidding Guidelines
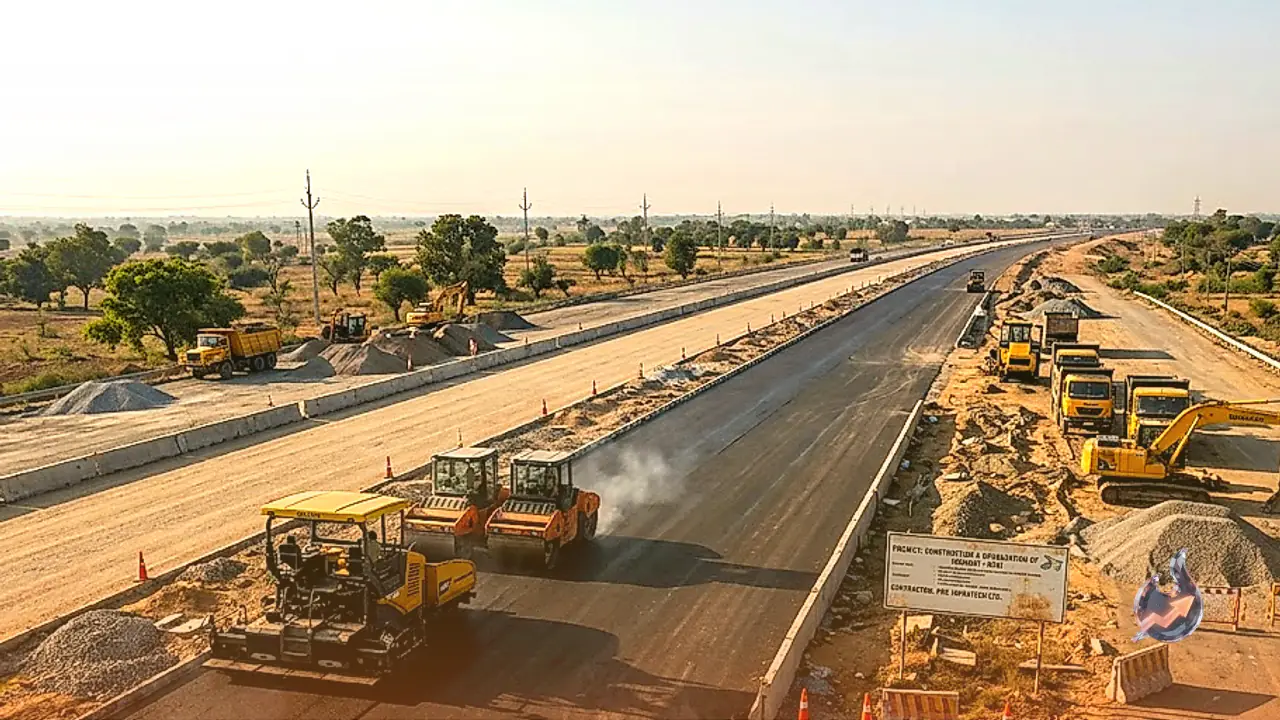
The domestic highway construction ecosystem is experiencing substantial expansion driven by continuous government funding for public infrastructure. Concurrently, the National Highways Authority of India (NHAI) has introduced stricter criteria and tighter regulations for project bidding. These structural changes are proving advantageous for well-established, organized market players such as PNC Infratech, preventing aggressive underbidding by unqualified firms and rewarding companies with proven balance-sheet capacity.
The company maintains a strong competitive position backed by a diversified order backlog, a healthy active bidding pipeline, steady project inflows, and emerging construction prospects. Supported by disciplined project completion schedules and financial credibility, PNC Infratech is projected to deliver an 18% CAGR in revenue, a 22% CAGR in EBITDA, and a 29% CAGR in adjusted profit after tax (APAT) from FY22 to FY25E.
Valuation Metrics, Buy Recommendation And Rs 390 Target
From a valuation perspective, the shares of PNC Infratech are currently trading at 11 times FY24E earnings per share (EPS) and 10 times FY25E EPS. These multiples reflect an attractive entry level given the sustained profit expansion expected across its operational segments.
The equity carries a BUY recommendation based on an assessment that values the standalone business at 11x FY25 EPS while pegging the operational HAM portfolio at 1x its book value. This methodology yields a target price of Rs 390 per share, indicating a potential capital appreciation of up to 42% from prevailing market levels. Timely execution of highway and water works remains central to unlocking this valuation headroom.