














Asian financial markets mounted an energetic comeback on Monday as investors aggressively bought beaten-down shares following last week's sharp downturn across global technology equities. The broader regional recovery was spearheaded by Taiwan's benchmark index, which experienced a remarkable rebound after suffering its most punishing five-day drop in two decades. Across the continent, most major bourses traded in positive territory, restoring confidence after sudden shifts in the United States political landscape and persistent concerns over artificial intelligence capital expenditures had triggered a massive tech sector pullback.
Taiwan's Taiex Rebounds Strongly Following Historic Plunge
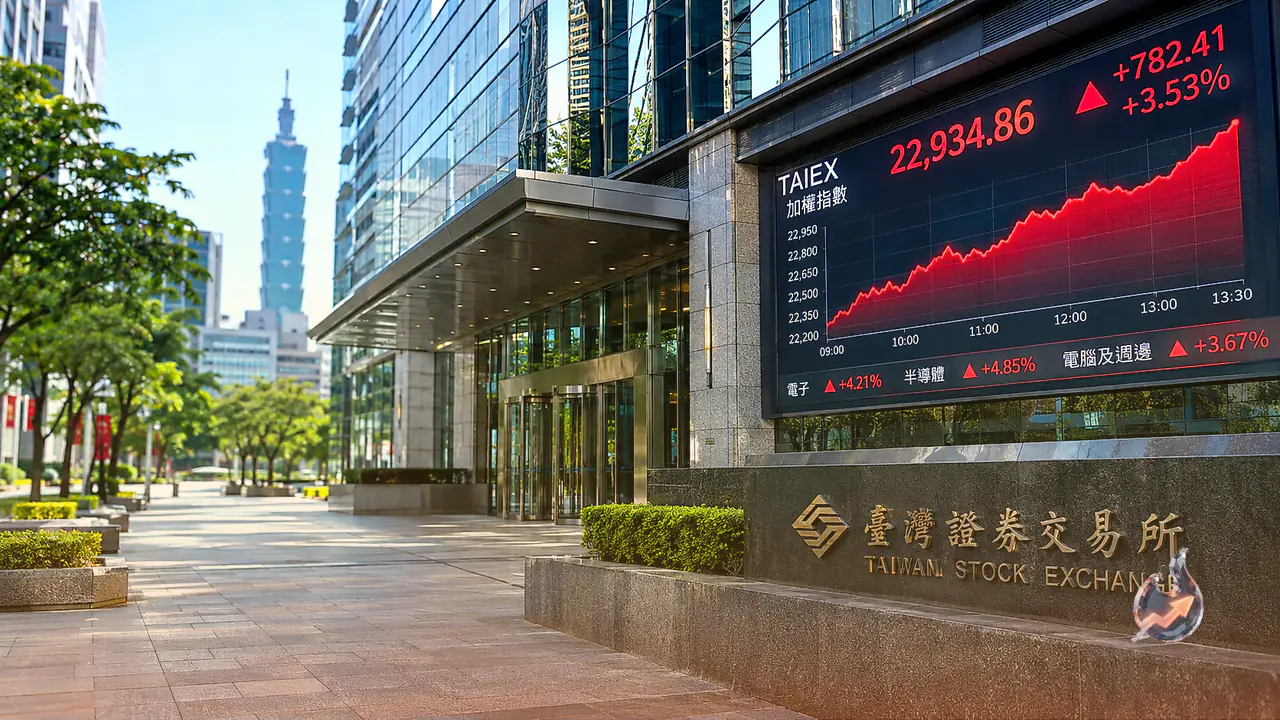
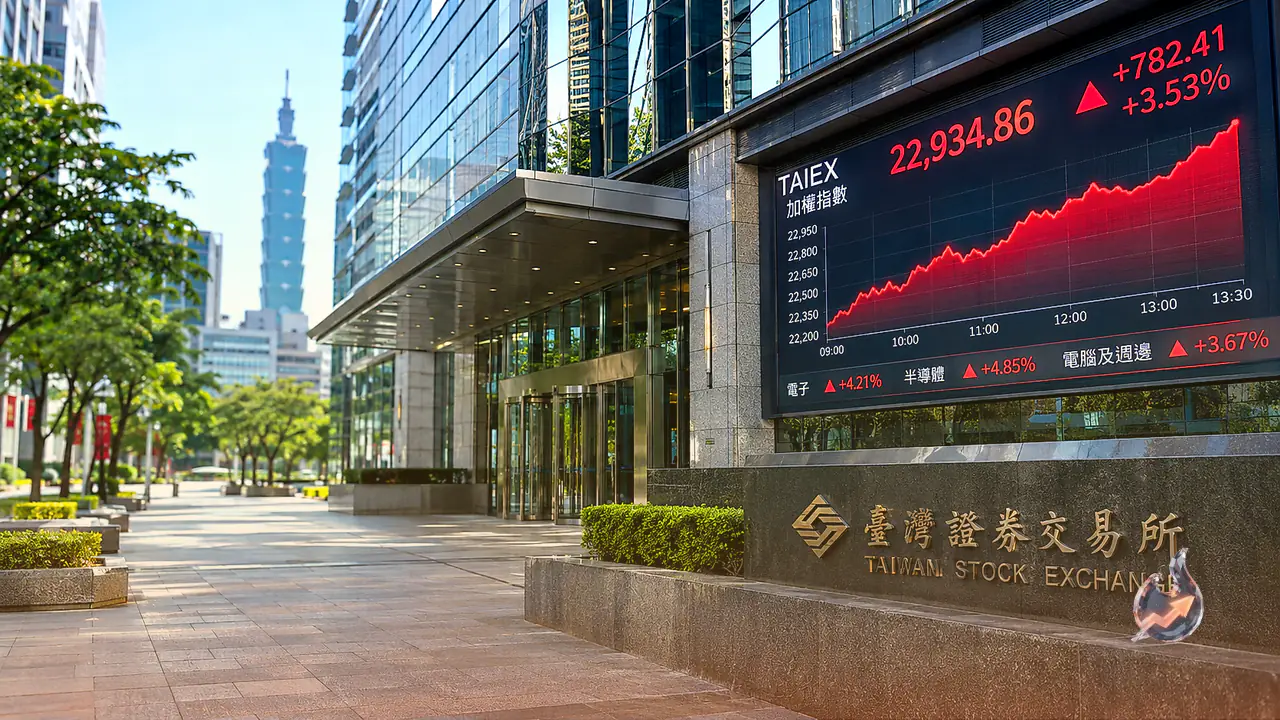
Taiwan's premier equity index, the TAIEX, jumped roughly 5.30% during Monday's trading session to settle near 41,800. This explosive turnaround followed a devastating weekly plunge, the steepest seen in twenty years, which was ignited by fears over whether massive corporate spending on artificial intelligence infrastructure would translate into near-term corporate profitability. The previous rout had gathered momentum after sweeping victories by Democrats in the United States midterm elections raised fresh questions regarding regulatory oversight, corporate taxation, and tech sector demand.
Adding to market sensitivities, industry bellwether Nvidia has initiated an internal corporate investigation to determine whether its Chief Executive Officer Jensen Huang was targeted by an espionage campaign orchestrated by foreign actors. Market analysts noted that corporate governance and national security developments of this magnitude could maintain high levels of price volatility across global chipmakers. Nevertheless, market participants on Monday prioritized attractive valuations, funneling substantial capital back into semiconductor foundries and component suppliers.
Mixed Performance Across Chinese and Hong Kong Exchanges
In mainland China and Hong Kong, equity indices showed steadying tendencies, albeit with far more subdued gains than their Taiwanese peer. The Shanghai Composite Index gained 0.35% to reach 3,660, demonstrating resilience amid persistent macroeconomic headwinds. Similarly, the Hong Kong Stock Exchange saw its primary benchmark rise by 0.13% to trade around 24,520. Bucking the upward regional trajectory, mainland China's Shenzhen Stock Index edged downward by 0.14% to 11,160.
Sentiment across Greater China was underpinned by trade developments rather than domestic data alone. October's inflation figures for China delivered a mixed macroeconomic signal, failing to generate significant optimism on their own. However, Beijing's decision to extend the temporary suspension of its 24% tariffs on American imported goods offered substantial relief to cross-border manufacturers, easing friction between the world's two largest trading partners and encouraging modest risk appetite.
Asia's Central Role in Driving Worldwide Economic Expansion
The Asian continent serves as the primary engine for global commerce, contributing approximately 70% of total worldwide economic growth. The region boasts several foundational financial benchmarks that serve as bellwethers for international asset allocators. Within Asia's developed sphere, Japan's Nikkei 225 index, representing 225 premier corporations listed on the Tokyo Stock Exchange, stands alongside South Korea's Kospi as essential barometers of manufacturing and semiconductor health.
China commands three critical indices that track state-owned giants and dynamic private enterprises: the Hang Seng in Hong Kong, alongside the domestic Shanghai Composite and Shenzhen Composite. Simultaneously, emerging market powerhouses like India have captured unprecedented capital flows from global institutional investors. Companies listed within India's benchmark Sensex and Nifty indices continue to command higher weightings in emerging market portfolios, driven by massive domestic retail demand and expanding middle-class consumption across the subcontinent.
Divergent Sectoral Drivers and Core Market Risks
The structural composition of Asian stock exchanges varies significantly from one jurisdiction to another. Cutting-edge technology firms heavily dominate the equity benchmarks of Taiwan, South Korea, Japan, and parts of mainland China. In contrast, financial centers like Hong Kong and Singapore are led by banking conglomerates, property developers, and asset management institutions that function as regional funding hubs. Industrial heavyweights in Japan and China remain centered on large-scale automotive production and specialized electronics manufacturing.
Corporate profitability, unveiled through quarterly and annual earnings releases, represents the principal engine dictating regional stock valuations over the long term. Beyond corporate balance sheets, national economic fundamentals, monetary decisions enacted by central banks, and government budgetary policies carry immense weight. Market movements across Asia also routinely mirror overnight trading trends from Wall Street. However, international investors face unique regional vulnerabilities, including divergent political systems ranging from democracies to autocratic governance, contrasting corporate reporting standards, territorial disputes, natural disasters, and sharp currency swings that directly impact export-reliant economies.
Currencies, Commodities, and Crypto Markets React to Macro Shifts
In foreign exchange trading, the Australian Dollar maintained a recovery posture near 0.6900 against the US Dollar. Live trading indicators show the AUD/USD pair hovering near 0.6889, supported by signs of de-escalating diplomatic friction between the United States and Iran alongside China's tariff suspensions. Concurrently, the USD/JPY pair slid into negative territory as foreign exchange traders locked in profits following a strong rally spurred by blowout US Nonfarm Payrolls figures, while the broader greenback retreated.
Precious metals saw a noticeable revival, with spot gold climbing back above $4,020 per ounce during morning European trade, bolstered by a softening US Dollar and renewed hopes for diplomatic solutions in the Middle East. Conversely, digital assets remained locked in a pronounced downtrend. Bitcoin struggled beneath its 50-week Simple Moving Average of $75,222, extending its weekly loss streak to five consecutive weeks. Sentiment was battered by heavy liquidations, as spot Bitcoin exchange-traded funds suffered massive net weekly outflows of $1.28 billion, marking the steepest capital withdrawal observed since late June.
Upcoming United States Inflation Data and Policy Trajectory
Financial market attention is now pivoting squarely toward Tuesday's release of the United States Consumer Price Index report. Because of a data collection void created by last October's federal government shutdown, official year-over-year inflation comparisons will not be accessible for this release. Market projections anticipate headline consumer inflation to expand by 0.28% month-over-month, with core consumer prices expected to rise by 0.21% over the same monthly interval.
While a moderation in core inflation would provide welcome relief after September's higher-than-expected inflation reading, analysts widely anticipate that current price pressures will still leave expectations firmly in place for an additional interest rate increase by the Federal Reserve during its December policy gathering.