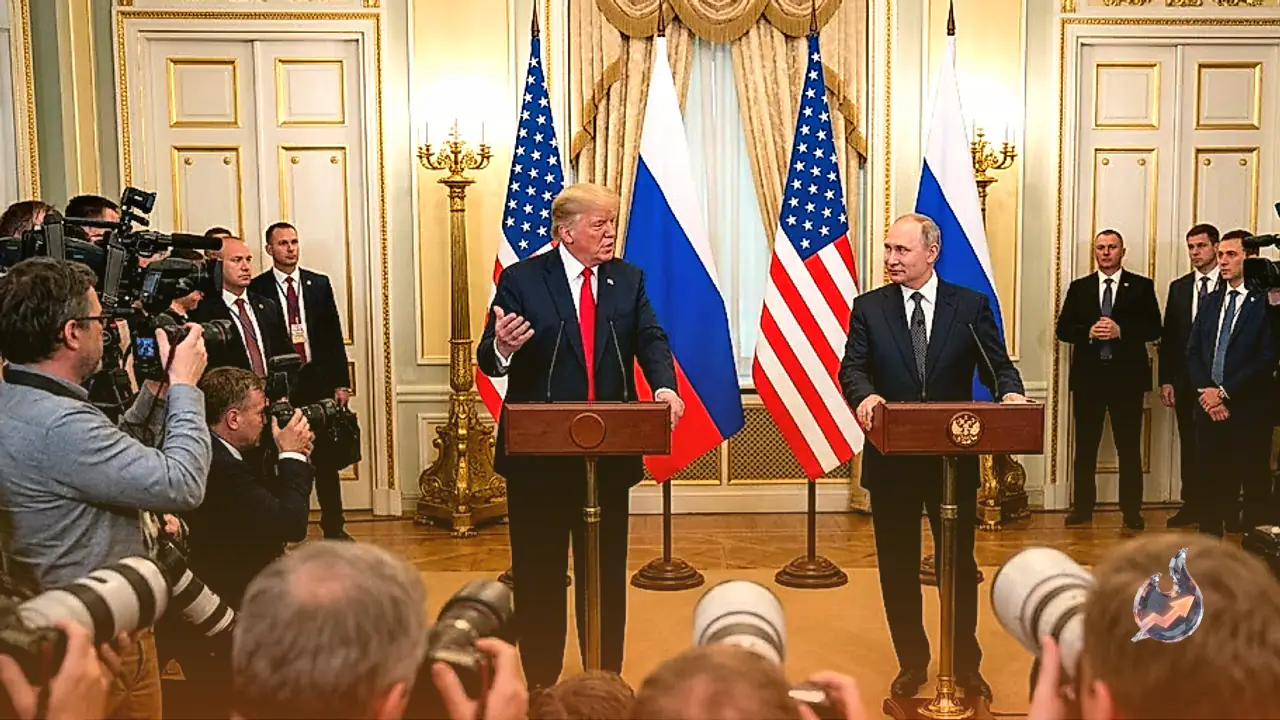















A sharp rally in global energy markets reversed abruptly after a breakthrough policy development introduced substantial Russian fuel shipments back into global supply chains. West Texas Intermediate crude pulled back after testing the $90.00 per barrel milestone, erasing the bulk of its session gains following an official announcement regarding fuel shipments. The shift came directly on the heels of discussions between Russian President Vladimir Putin and President Donald Trump, leading to an immediate plan to route Russian diesel into both the United States and international markets. Backing the move, the Treasury Department's Office of Foreign Assets Control issued General License 135 to permit the trade, compressing domestic refining margins and triggering a swift retreat in crude futures.
Details of the Russian Fuel Flow and Treasury Licensing
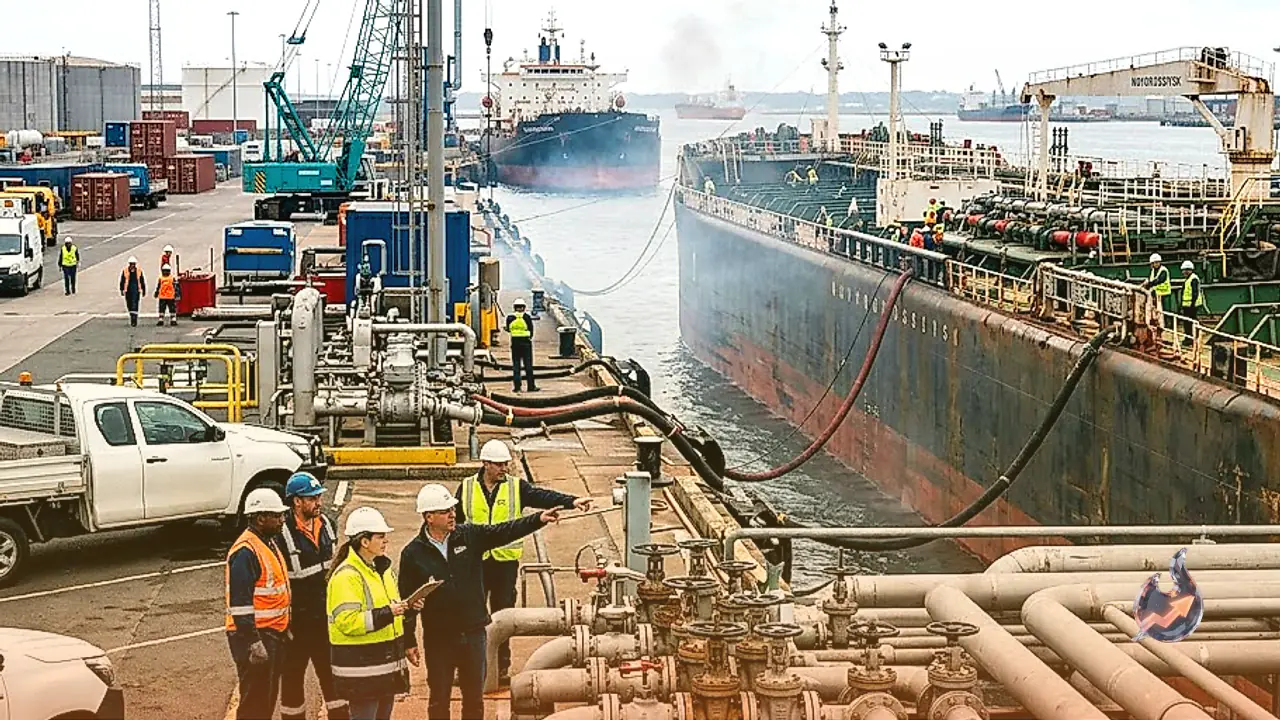
Following a telephone exchange with Russian President Vladimir Putin, President Donald Trump outlined an arrangement under which Russia will begin supplying more than 300K tons of diesel right away to domestic and international buyers. The schedule expands significantly over the coming months, with designated quotas pegged at 500K tons in November and escalating to 1 million tons in subsequent deliveries. The initial allocation of 300K tons translates to roughly 2.2 million barrels of fuel. In the context of American fuel infrastructure, that initial volume satisfies slightly more than half a day of domestic demand for distillate fuels, a product category overwhelmingly made up of diesel.
The administrative mechanism facilitating this sudden fuel influx was formalized by the Treasury Department. Its Office of Foreign Assets Control granted General License 135 on the very same day, providing legal authorization for the purchase and import of Russian diesel, including direct entries into the United States, through April 7, 2027. This represents the second aggressive policy intervention by President Donald Trump targeted at the diesel segment within a single week. Earlier, on October 2, European Union member states endorsed a French proposal to tap and release emergency diesel stockpiles in response to his explicit request.
Refining Margins Squeezed as NY Harbor Futures Plunge
The swift change in product availability exerted immediate downward pressure on refined fuel derivatives. New York diesel futures fell back toward $4.67 per gallon following the announcement, surrendering virtually all the ground gained during Thursday's trading session. Translated to barrel terms, that price point places refined diesel near $196 per barrel. With WTI crude changing hands near $90.50, American refiners were commanding a refining spread exceeding $100 on every barrel of diesel manufactured domestically.
Inbound Russian shipments introduce direct competitive pressure against that high-cost domestic output. As the crack spread narrows, domestic refiners lose the financial incentive to bid aggressively for input feedstocks like WTI. The physical oil market reacted without delay. Spot WTI sank from near $91.00 to just under $90.00 across two five-minute candles immediately following the post, erasing roughly three-quarters of its rebound from the intraday floor just below $89.50. The retreat originated from the second of two distinct session rallies that failed to penetrate above $91.50. While WTI subsequently clawed back ground toward $90.50 to hover near the midpoint of its $89.50 to $91.50 range, intraday momentum collapsed from overbought territory toward oversold readings.
Understanding West Texas Intermediate as a Market Benchmark
West Texas Intermediate represents one of the premier grades of crude oil actively traded across global commodity exchanges. Alongside European benchmark Brent and Middle Eastern benchmark Dubai Crude, WTI serves as a primary international reference price. Within petroleum engineering terminology, WTI is characterized as light and sweet because of its low API gravity and minimal sulfur content. These intrinsic physical properties make it an exceptionally high-grade crude that requires less energy and complexity to refine into consumer fuels such as gasoline and diesel.
Extracted primarily from oilfields across North America, WTI crude is pooled and distributed through the storage infrastructure located in Cushing, Oklahoma. Cushing is widely celebrated in industry circles as The Pipeline Crossroads of the World because of the vast nexus of inbound and outbound transit infrastructure converging there. Because of this strategic logistics role, WTI remains a baseline pricing mechanism across global trading floors, with its movements quoted daily across financial reporting channels.
Core Drivers Influencing Global Crude Valuations
Just like any internationally traded commodity, the absolute price of WTI is governed fundamentally by the equilibrium between supply and demand. Accelerated global economic expansion typically fuels energy consumption across manufacturing, aviation, and logistics, exerting upward pressure on pricing. Conversely, periods of macroeconomic stagnation undermine product demand and suppress price realization. Geopolitical volatility, regional military conflicts, and trade sanctions introduce acute supply bottlenecks that can spark sudden price spikes. In addition, production quotas set by OPEC represent another fundamental lever dictating available supply. Because international petroleum trade is transacted overwhelmingly in US Dollars, currency fluctuations also play a substantial role. A softer dollar renders oil cheaper for buyers holding foreign currencies, whereas a strengthening dollar makes it costlier.
Inventory Tracking via API and EIA Data Releases
Energy traders monitor weekly petroleum storage data to gauge short-term shifts in physical supply balances. The two primary barometers followed by the industry are compiled by the American Petroleum Institute and the Energy Information Administration. Fluctuations in these stockpile readings capture whether real-time consumption is outpacing extraction or falling behind. When official tallies report a net draw in stockpiles, it often indicates robust refinery intake and elevated consumer demand, providing a bullish tailwind for prices. Conversely, swelling inventories suggest surplus supply conditions, which typically depress spot valuations.
The American Petroleum Institute distributes its private survey every Tuesday, followed by the Energy Information Administration releasing its government-compiled statistics the following day. Historical comparisons indicate that both reporting agencies produce closely aligned readings, coming within 1% of each other in 75% of recorded instances. Nonetheless, professional market participants place greater weight on the EIA release due to its status as an official federal agency with access to comprehensive reporting mandates.
The Market Power of OPEC and the OPEC+ Alliance
Coordinated management of worldwide output remains centered around the Organization of the Petroleum Exporting Countries. This coalition consists of 12 petroleum-producing nations that convene biannual ministerial summits to negotiate formal output quotas for each sovereign participant. When member states resolve to lower aggregate output quotas, available global barrels tighten, prompting an upward reassessment of WTI prices. Conversely, when the group votes to inject additional barrels into commercial channels, prices soften under the weight of higher volume. To expand its collective sway, the group formed OPEC+, an extended pact that incorporates ten non-OPEC oil-producing nations. Among these external partners, Russia stands out as the most prominent, possessing the capacity to alter global fuel balances through unilateral export shifts.
Concurrent Shifts Across Foreign Exchange and Bullion
The reassessment of energy valuations coincided with broader rebalancing across foreign exchange and precious metals desks. In currency action, AUD/USD rebounded from its weekly low to target the 0.7000 handle during Friday's Asian trading window. A retreat in US bond yields kept the greenback from reclaiming its 18-month peak, aiding the Australian Dollar alongside hawkish policy expectations surrounding the Reserve Bank of Australia.
Concurrently, USD/JPY held steady near 158.00 after Friday data confirmed that household spending in Japan contracted for the ninth consecutive month, putting ongoing downward pressure on the Yen. In precious metals, Gold relinquished early gains after attempting to challenge weekly peaks, sinking back below $4,200 per troy ounce on Friday as a resilient dollar and climbing Treasury yields across the curve limited upward momentum for the yellow metal.