













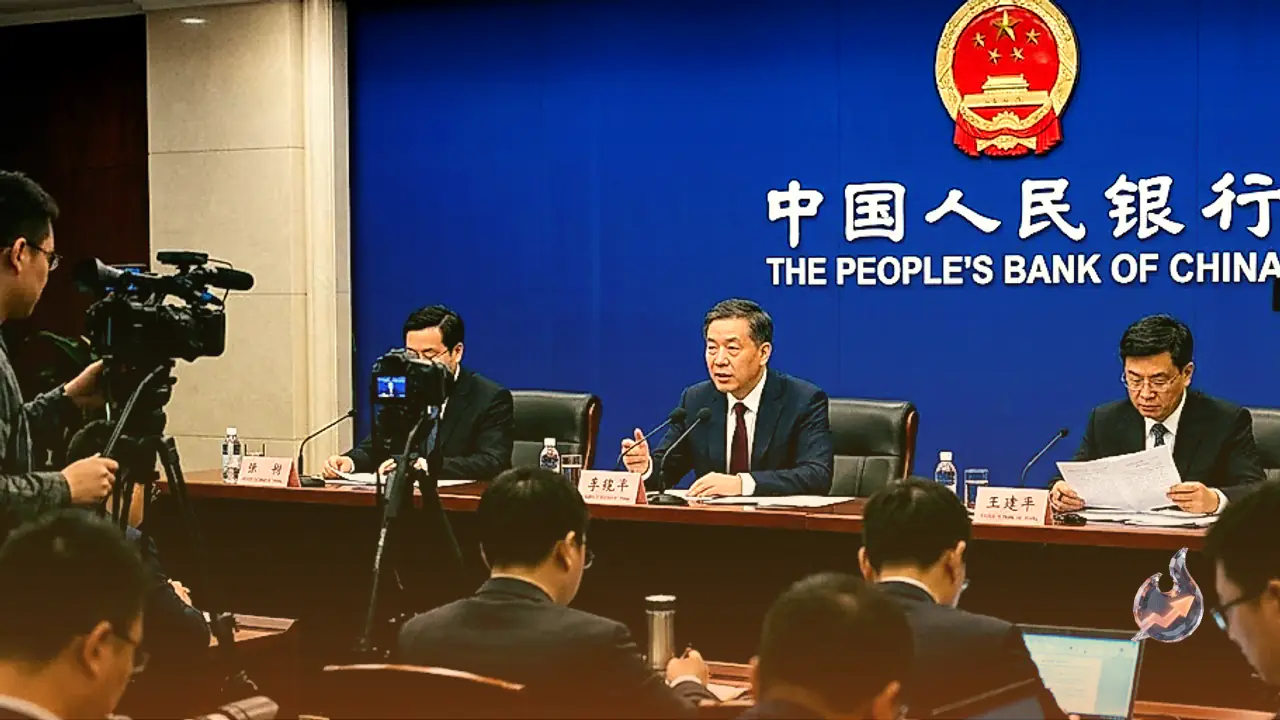

China's central bank, the People's Bank of China, has issued a fresh policy document defending the nation's foreign exchange framework and firmly pushing back against claims that the level of the Chinese Yuan, or CNY, is responsible for the country's massive trade surplus. The monetary authority argued that domestic competitive advantages across China's manufacturing sector remain the primary catalyst behind the expansion in export volumes, rather than any artificial suppression of currency valuations.
High-Level Trade Talks and Policy Stance
The release of this comprehensive document coincided directly with bilateral trade discussions between Trade Commissioner Maros Sefcovic and Chinese Commerce Minister Wang Wentao. Presenting such an explicit defense alongside these negotiations indicates that Beijing has little intention of altering its currency stance under external pressure. The development has revived international debate regarding whether the Chinese currency is artificially undervalued against global peers.
Market analyst Halpenny observed that while the Chinese Yuan does appear to be undervalued, the exact magnitude remains a subject of intense debate among economists. While a weaker exchange rate inherently provides support to exporters, currency valuation offers only a partial explanation for China's persistent commercial strength. Structural manufacturing scale, supply chain integration, and production efficiencies play an equally substantial role in maintaining high export volumes across overseas markets.
BIS Real Effective Exchange Rate and IMF Projections
Historical valuation indicators provide notable context to the ongoing currency debate. According to real effective exchange rate data compiled by the Bank for International Settlements, the RMB advanced by nearly 60 percent between 2005 and the close of 2015. However, following its peak in 2022, the index dropped 20 percent to reach last year's cyclical trough before edging up 6.5 percent toward current readings.
Estimates provided by the International Monetary Fund place the undervaluation of the CNY between 12 percent and 20 percent, aligning broadly with prevailing consensus figures. Rising international scrutiny appears to be steering authorities toward permitting renewed currency strength. Recent PBoC fixing benchmarks in USD/CNY demonstrate an underlying preference to keep the currency on an appreciating trajectory despite broader resilience in the US Dollar. Concurrently, EUR/CNY has fallen 10 percent from its January high, with market observers identifying scope for additional downside over the near term.
Developments Across Key Currency Pairs and Gold
Beyond the developments surrounding the Yuan, cross-market dynamics showed significant movement across key asset classes. In Asian trading on Friday, AUD/USD regained upward traction, building upon a rebound from its weekly trough and advancing toward the 0.7000 threshold. An overnight pullback in US bond yields contained the US Dollar beneath its 18-month high, lending vital support to the Australian pair alongside hawkish expectations surrounding the Reserve Bank of Australia.
Meanwhile, USD/JPY maintained its elevated positioning near 158.00 after Friday figures confirmed that Japanese household expenditure declined for the ninth consecutive month, weighing heavily on the Japanese Yen. While a hawkish Federal Reserve stance and prevailing geopolitical uncertainties provided floor support for the dollar, softer Treasury yields helped cap excessive upward momentum in the pair. In precious metals, gold surrendered early momentum after attempting to reach fresh weekly peaks, retreating below the 4,200 dollar mark per troy ounce on Friday under pressure from sustained dollar strength and firm yields across the US Treasury curve.