














A fresh acceleration in headline consumer prices across the Czech Republic has handed policymakers substantial justification to preserve an aggressive monetary policy posture. Official figures reveal that inflation climbed unexpectedly to 2.5 percent in September, picking up notably from the 1.9 percent pace recorded during August. This upward surprise reinforces an increasingly hawkish policy stance at the Czech National Bank, where rate setters have consistently guided markets toward either holding borrowing costs steady or delivering another rate hike. With policy tightening odds expanding, the Czech Koruna enjoys durable support, significantly elevating the prospects of EUR/CZK maintaining a sustained footing below the 24.50 threshold.
All Eyes on Detailed October 13 Inflation Breakdown
Market participants are now recalibrating their projections ahead of October 13, when detailed sub-component data will be released. This data breakdown will spotlight whether underlying core price pressures and services inflation remain uncomfortably elevated across the domestic economy. If these critical readings confirm persistent heat in pricing trends, the rationale for an official rate hike at the upcoming November meeting will become considerably stronger. Such an outcome would cement the domestic central bank's standing as the most hawkish monetary authority across Central and Eastern Europe.
Investors are monitoring two explicit quantitative benchmarks: whether core inflation pushes above the 3.0 percent registered in August, and whether services inflation advances beyond 4.5 percent. The Czech National Bank has specifically singled out a 4.5 percent reading in the services bracket as fundamentally incompatible with medium-term price stability. Any further acceleration across these underlying components would solidify expectations for higher benchmark rates, maintaining steady tailwinds behind the local currency.
Elevated US Yields and Currency Crosses
Across the broader currency sphere, the US Dollar retains underlying resilience even as investor bets on an October Federal Reserve interest rate increase continue to diminish. A persistent rout across global fixed income markets has kept US Treasury yields anchored near multi-year highs. Combined with lingering geopolitical tensions, elevated yields continue to underpin the greenback across several major currency pairs.
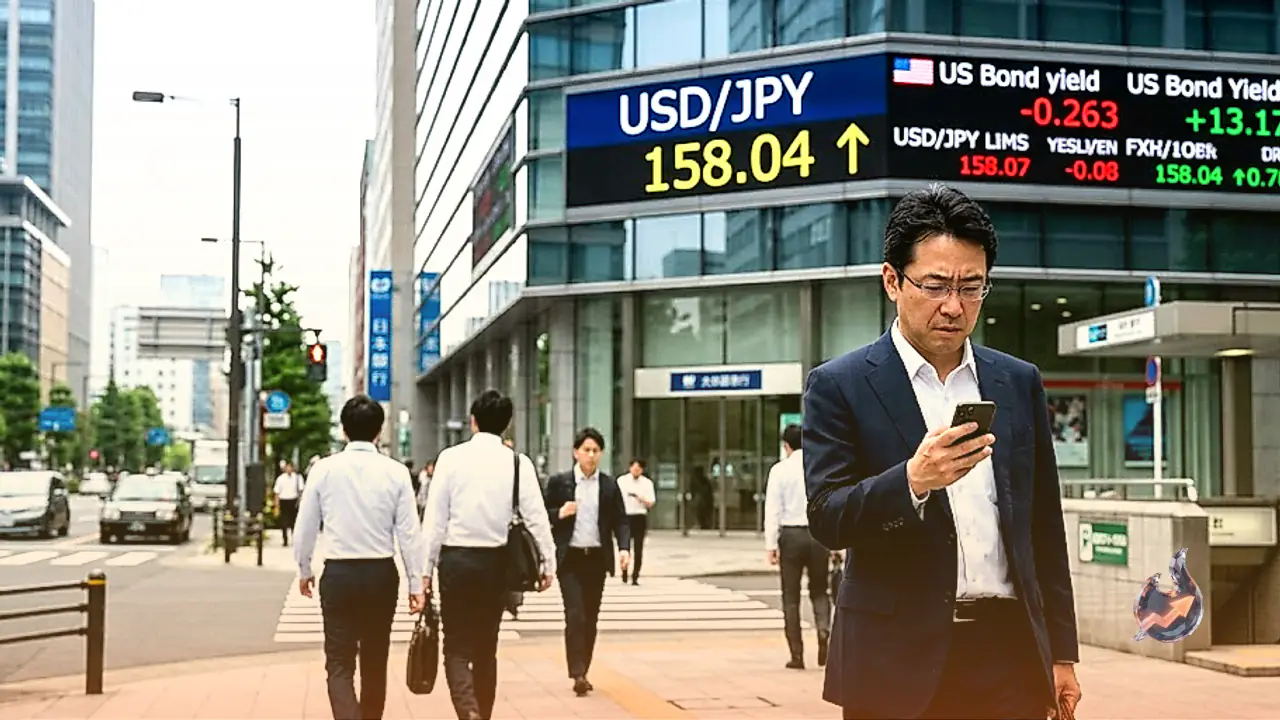
During Tuesday's Asian trading session, AUD/USD softened slightly, halting a two-session recovery off the two-month trough established late last week. Nevertheless, lingering expectations that the Reserve Bank of Australia might implement an interest rate hike later this month offer potential downside protection for the Australian Dollar. Meanwhile, USD/JPY pushed back above the 158.00 handle early in the European morning. The Japanese Yen struggled to derive meaningful momentum from expectations of Bank of Japan policy tightening or potential direct intervention risks, enabling the greenback to stay firm near its yearly peaks.
Gold Finds Support Amid Geopolitical Hesitation
Precious metals experienced a modest relief rally during the early part of Tuesday's European session. Gold rebounded from the $4,100 zone, which marked a two-month low, advancing past $4,150. A temporary pause in the US Dollar's recent ascent from September monthly lows provided breathing room for bullion. The easing of market wagers regarding an immediate October Federal Reserve policy increase has further supported demand for non-yielding assets.
Trading desks face a calendar devoid of tier-1 macroeconomic releases today, shifting investor attention toward political developments in Europe and ongoing tensions across the Middle East. In France, market stability hinges on whether the Socialists alongside Marine Le Pen's National Rally signal an intention to bring down the incumbent government during upcoming budget deliberations.
The European Central Bank's Policy Dilemma
The European Central Bank finds itself navigating an increasingly intricate policy bind. Under standard operating conditions, headline inflation running at virtually double the official target would prompt a straightforward monetary response in the form of interest rate increases. However, current financial conditions diverge from historical norms. A sharp rise in sovereign bond yields indicates that fixed income markets are already engineering substantial monetary tightening independently, confronting the ECB with a delicate balance between containing inflationary pressures and mitigating broader economic contraction risks.