














Financial markets are undergoing a significant reassessment regarding the trajectory of Federal Reserve monetary policy over the coming year. Current market pricing continues to reflect expectations of slightly more than three rate increases across the next 12 months, an outlook that analysts view as excessively aggressive. Recent employment indicators reveal a deceleration in hiring alongside moderating wage expansion, offering clear evidence that price pressures originating from the labour sector are diminishing. Should forthcoming inflation figures validate that core price trends remain restrained, market participants are anticipated to steadily trim their expectations for further monetary tightening.
Shifting Federal Reserve Expectations and the Dollar Outlook
Anticipation of an interest rate increase by the Federal Reserve in October has diminished substantially following guidance from several policymakers. Senior central bank officials have indicated little immediate necessity to tighten monetary conditions further, repeatedly highlighting the importance of evaluating incoming economic releases before committing to additional action. This commentary has guided investors toward anticipating a policy pause during the October gathering, effectively delaying any potential tightening moves toward the latter stages of the calendar year.
Foreign exchange participants remain largely concentrated on movements in the EUR/USD pair. Barring an acute escalation in volatility across European debt markets, the baseline projection anticipates a measured appreciation in the greenback toward year-end rather than a disruptive, aggressive surge.
Performance Across Major Currency Pairs
During Tuesday trading in Asia, the AUD/USD pair registered minor declines, halting a two-day rebound from the two-month trough established last week. Ongoing weakness in fixed income securities has preserved US Treasury yields near multi-year peaks. These elevated yields, paired with prevailing geopolitical unpredictability, have enabled the greenback to preserve a resilient stance despite diminished bets on an October rate hike. Nevertheless, market expectations that the Reserve Bank of Australia could implement another rate hike during the current month could provide vital support for the Australian dollar.
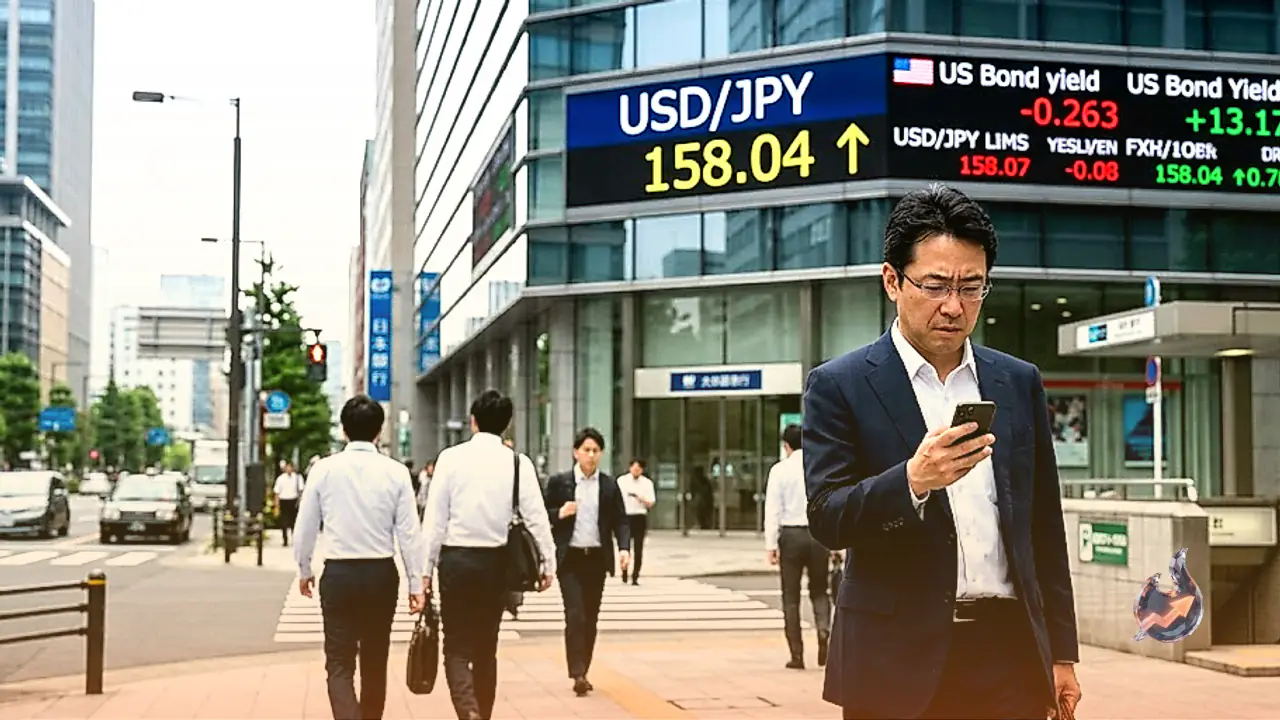
Simultaneously, USD/JPY advanced beyond the 158.00 threshold during the initial hours of the European session on Tuesday. The pair gained ground as the Japanese Yen failed to draw upward momentum from expectations surrounding a hawkish Bank of Japan or heightened warnings of currency intervention. Elevated US yields and geopolitical tensions kept the dollar positioned near its year-to-date highs, offering persistent backing to the cross.
Gold Rebounds as European Political Risks Loom
Precious metals experienced a recovery as gold extended its modest rebound from the $4,100 mark, which represented a two-month low, advancing past $4,150 during the initial half of European trading. The greenback took a temporary pause following a sustained rally from its September swing bottom, providing breathing room for non-yielding bullion. Diminishing expectations regarding an imminent October Federal Reserve rate hike provided additional tailwinds for gold valuations.
With no tier-1 economic reports scheduled for release today, investor attention is expected to stay anchored on developments across European financial markets alongside evolving geopolitical tensions in the Middle East. Political developments in France represent a critical monitoring point over the coming days, specifically whether the Socialists and Marine Le Pen's National Rally signal an intention to bring down the administration over disagreements surrounding the national budget.
Policy Conundrum Confronting the European Central Bank
Under conventional circumstances, the European Central Bank would address inflation running at nearly double its targeted rate through straightforward interest rate increases. Current conditions, however, diverge sharply from standard environments. The regional sovereign bond market is already executing a portion of that financial tightening autonomously through rising yields, confronting the European Central Bank with a progressively intricate policy dilemma as it balances price stability against mounting market pressures.