













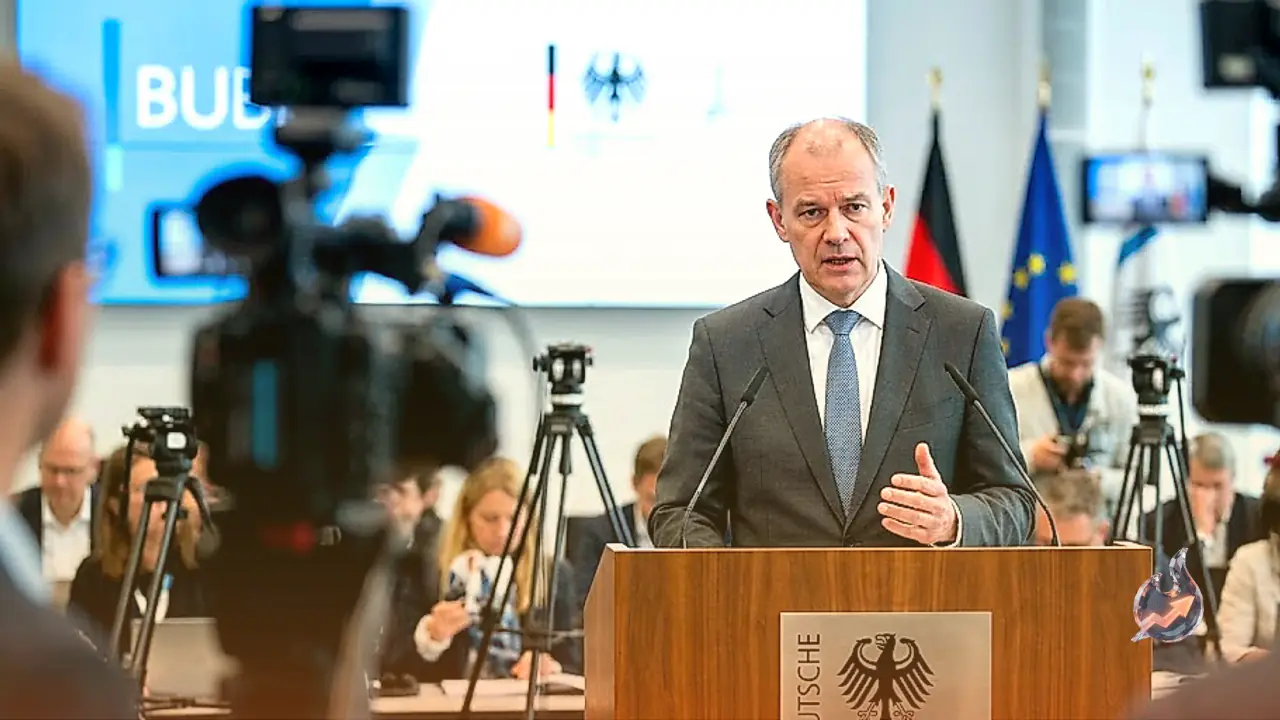

A potential return to tighter monetary policy in the Eurozone has re-entered central banking discussions as energy market pressures disrupt disinflation timelines. Bundesbank President and European Central Bank Governing Council member Joachim Nagel, addressing a financial gathering in London, indicated that policymakers cannot rule out guiding borrowing costs into mildly restrictive territory. The shift in tone comes as elevated energy expenses have derailed consumer price trends away from the institution's projected 2026 inflation objective.
Policy Stance and the Boundary of Neutral Rates
Speaking at the London event, Joachim Nagel outlined that key policy rates across the Eurozone currently sit inside neutral territory. However, he emphasized that policymakers must retain flexibility should persistent price drivers fail to subside. Nagel described the institution's approach as navigating monetary policy directly between constructive ambiguity and forward guidance. He noted that he does not observe excessive uncertainty across financial markets regarding the core drivers behind the central bank's policy choices, signaling that rate-setting mechanisms remain clear to investors.
Regarding employment trends, the Bundesbank chief stated that he is not particularly concerned about current labour market developments. Stable employment conditions across the single-currency bloc give rate setters room to prioritize consumer price stabilization without immediate fear of destabilizing hiring dynamics. As long as energy overheads threaten to linger across consumer baskets, policymakers appear unwilling to dismiss additional rate hardening.
Currency Fluctuations Across Global Exchange Desks
Foreign exchange markets exhibited varied reactions alongside the central bank remarks, with the Euro recording diverse movements against major global peers. In currency market monitoring, the Euro displayed its strongest performance against the Canadian Dollar. Price performance heat maps, which measure percentage fluctuations between base currencies and quote currencies across trading sessions, reflected steady Euro valuations against the US Dollar amidst broader market caution.
Broader currency pairs also experienced noticeable shifts. The Australian Dollar extended Monday's weakness against the Greenback, sliding beneath the critical 0.7100 threshold to touch a three-day low. Persistent demand for the US Dollar maintained downward momentum on the Aussie, while market participants positioned ahead of Thursday's scheduled summit between Donald Trump and Xi Jinping. Concurrently, the US Dollar traded near 157.50 against the Japanese Yen during Tuesday's Asian trading window, logging minor advances as official currency intervention concerns capped steeper Yen depreciation.
Bank of Japan Rate Hike and Gold Movement
Monetary adjustments were equally visible across Asian financial centers. The Bank of Japan raised its short-term interest rate target from 1.00% to 1.25% following a 7-2 vote among its policy board members. The decision pushed benchmark borrowing costs in Japan to a 31-year high, marking a decisive continuation in the normalization of Japanese monetary policy while closely aligning with consensus expectations established over preceding weeks. Nonetheless, a hawkish outlook from the US Federal Reserve alongside heightened tensions in the Middle East sustained underlying strength in the US Dollar, leaving Yen buyers cautious.
Against the backdrop of geopolitical friction, precious metals attracted renewed capital. Gold recovered its footing on Tuesday, advancing toward the pivotal $4,400 per troy ounce threshold. The metal advanced despite higher buying interest in the US Dollar and mixed movements in US Treasury yields, drawing support from investors navigating international macroeconomic uncertainties.
The European Central Bank Mandate and Policy Tools
Headquartered in Frankfurt, Germany, the European Central Bank functions as the reserve bank for the Eurozone, determining benchmark borrowing costs and directing the monetary strategy of the member economies. The primary legal mandate of the institution is maintaining price stability, defined as keeping headline inflation anchored near the 2% target over the medium term. Adjusting interest rates serves as the central bank's primary mechanism: relatively high interest rates typically strengthen the Euro against trading partners, while rate reductions tend to soften currency valuations.
Monetary decisions are made by the ECB Governing Council across eight scheduled policy meetings held each year. The decision-making body includes the governors of the Eurozone national central banks alongside six permanent executive board members, led by ECB President Christine Lagarde. This collective council evaluates macroeconomic indicators to determine whether benchmark borrowing rates should remain neutral, expand, or move into restrictive territory.
Quantitative Easing Compared to Quantitative Tightening
During severe financial dislocations, the European Central Bank has deployed extraordinary balance sheet mechanisms, most notably Quantitative Easing. Under this framework, the central bank generates Euros electronically to purchase assets, primarily sovereign debt and corporate bonds, directly from commercial lenders and financial institutions. This liquidity injection typically results in a softer Euro exchange rate. Asset purchases serve as a measure of last resort when conventional rate cuts prove insufficient for securing price stability, having been utilized during the Great Financial Crisis between 2009 and 2011, during 2015 when inflation hovered persistently low, and throughout the covid pandemic.
Conversely, Quantitative Tightening represents the precise reversal of balance sheet expansion. The central bank initiates this process when economic expansion gathers momentum and inflation pressures resurface. Rather than acquiring bonds to supply liquidity, the European Central Bank ceases net asset purchases and stops reinvesting the principal proceeds from maturing sovereign and corporate debt held on its books. In global foreign exchange trading, balance sheet runoff through Quantitative Tightening is traditionally viewed as supportive and bullish for the Euro.