














The US Dollar extended its upward momentum on Tuesday, touching fresh multi-week highs as financial markets priced in the prospect of further monetary tightening by the Federal Reserve. Growing optimism regarding a diplomatic resolution to the conflict involving the United States, Iran, and the Strait of Hormuz appeared to take a backseat, with currency traders remaining firmly focused on macro yield differentials and central bank rhetoric across global exchanges.
Dollar Index Clears 100 as Key Macro Releases Approach
Surging through the psychological 100.00 threshold, the US Dollar Index climbed to two-month peaks, maintaining its composure even as US Treasury yields exhibited a mixed tone across the maturity curve. Market participants are bracing for the release of preliminary S&P Global Manufacturing and Services Purchasing Managers' Index figures for the current month. Additional market catalysts scheduled for release include the weekly MBA Mortgage Applications, the Energy Information Administration's commercial crude inventory report, and scheduled remarks from Federal Reserve official Barr.
European Currencies and Yen Face Lingering Pressure
The broader advance in the dollar left major European and Asian currencies navigating headwinds. The British Pound retreated to levels not seen since late July, settling near 1.3320 against the greenback. Investors across the English Channel are actively watching for flash September S&P Global PMIs spanning manufacturing and services to evaluate economic momentum across the continent.
In Asian trading hours, USD/JPY registered modest gains, hovering in the vicinity of 157.50. Lingering market concern over potential official intervention limited deeper losses for the Japanese Yen. The Bank of Japan voted 7-2 to increase its short-term interest rate target from 1.00% to 1.25%, pushing borrowing costs to a 31-year high in a widely anticipated continuation of its policy normalisation cycle. However, the relatively dovish tone surrounding the hike kept yen buyers on the back foot, while the Federal Reserve's hawkish stance and geopolitical tensions provided underlying support to the currency pair.
Australian Dollar Gains Capped Ahead of Trump-Xi Talks
The Australian Dollar found buying interest above 0.7100 during Tuesday's Asian session, buoyed by hawkish commentary from Reserve Bank of Australia Assistant Governor Sarah Hunter and Governor Michele Bullock. Even so, persistent geopolitical strain across the Middle East combined with the Federal Reserve's tightening narrative reinforced the dollar's strength, limiting the room for extended gains in AUD/USD.
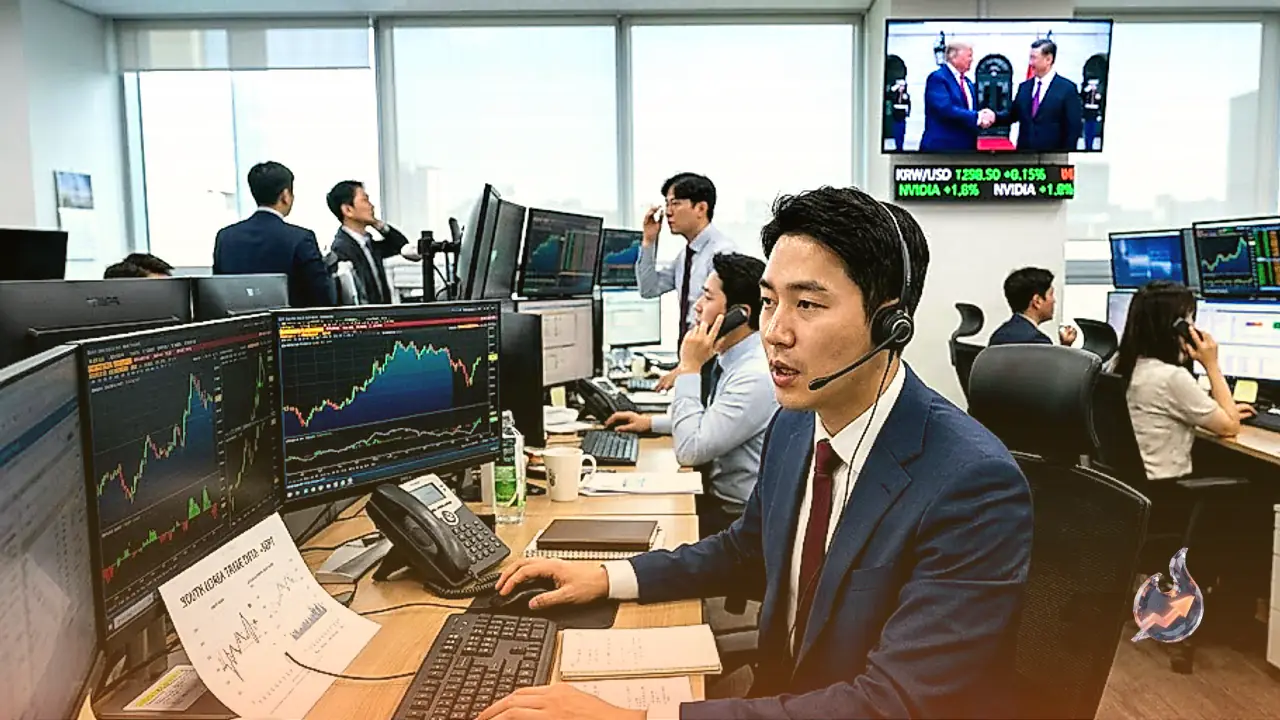
Global market participants are turning their attention to Washington, where US President Donald Trump and Chinese President Xi Jinping are scheduled to hold a summit meeting on Thursday. The diplomatic engagement between the leaders of the two largest economies is seen as pivotal in determining whether the bilateral trade truce can be sustained or if fresh geopolitical and commercial friction will emerge.
Crude Oil Slumps on Hormuz Hopes While Gold Rebounds
Commodities painted a divergent picture as front-month WTI crude oil futures broke decisively below the critical $90.00 per barrel benchmark, sliding to three-week lows. The selling pressure was triggered by revived expectations of a safe reopening of the vital Strait of Hormuz, easing imminent supply disruption fears across shipping routes.
Conversely, gold managed to reverse its earlier softer stance, gaining steady ground and making an approach toward the key $4,400 per troy ounce threshold. The precious metal held onto its gains despite headwinds from the firmer dollar and conflicting signals from US bond yields, highlighting lingering demand for safe-haven protection amid broader global uncertainties.