













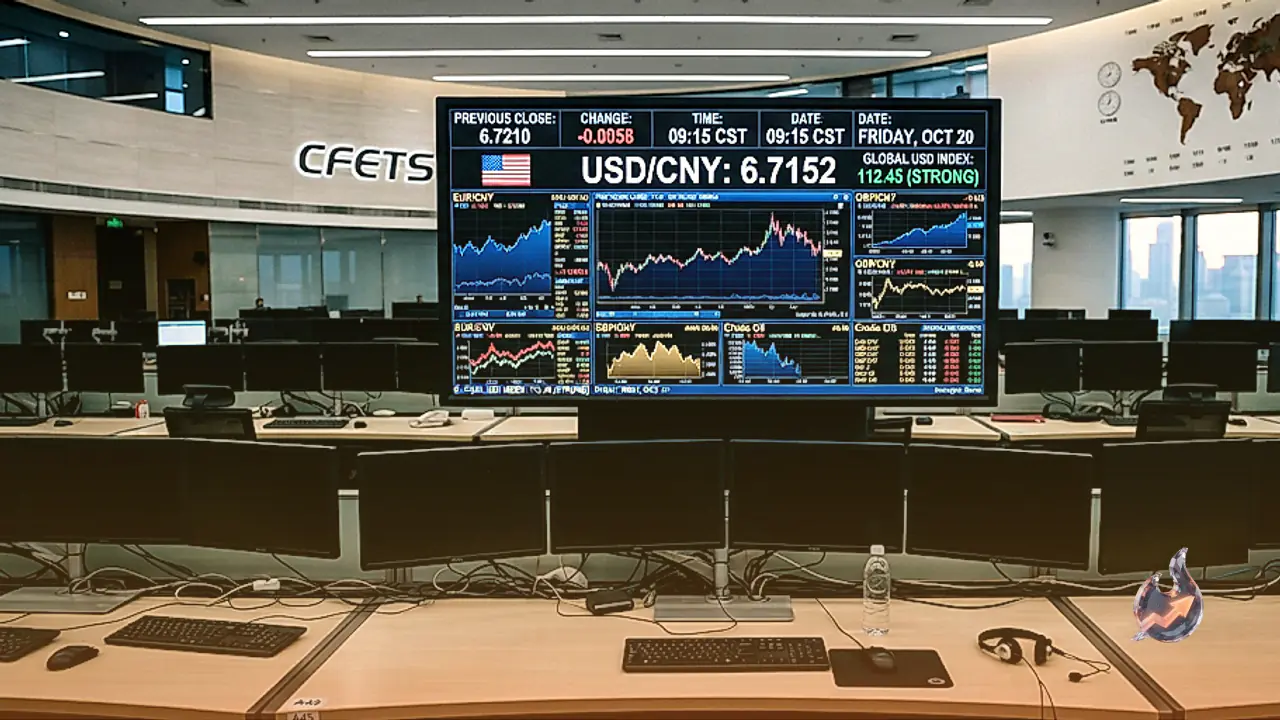

The People's Bank of China set the daily central parity rate for the Chinese Yuan against the US Dollar at 6.7152 ahead of Friday's trading session. This official fixing reflects a modest firming compared to the prior session's benchmark of 6.7174, while diverging from market projections where a Reuters estimate had pointed toward 6.6756. In the structure of Chinese foreign exchange management, this daily reference rate acts as the foundational anchor around which onshore currency trading fluctuates throughout the business day.
Core Policy Goals and Governance Structure of the PBOC
The People's Bank of China operates under explicit mandates centered on maintaining domestic price stability, ensuring orderly exchange rate conditions, and backing sustainable economic expansion. Beyond regular liquidity operations, the institution carries the responsibility of executing domestic financial reforms, with continuous initiatives directed toward opening access and maturing the mainland financial ecosystem.
Unlike many major Western monetary authorities, the PBOC does not function as an autonomous entity insulated from government control. Ownership resides entirely with the state under the People's Republic of China. Strategic oversight and operational direction are heavily driven by the Chinese Communist Party Committee Secretary, a leadership position nominated by the Chairman of the State Council. This post carries primary weight in steering bank decisions, traditionally surpassing the influence of the governor. At present, Pan Gongsheng occupies both critical roles simultaneously, uniting the administrative duties of the governor and the political direction of the party committee secretary under single leadership.
Monetary Toolkit and the Central Role of the Loan Prime Rate
To navigate its economic directives, the central bank deploys an extensive suite of policy instruments that contrasts sharply with standard Western central bank mechanics. Key operational mechanisms include the seven-day Reverse Repo Rate, the Medium-term Lending Facility, targeted foreign exchange market interventions, and adjustments to the Reserve Requirement Ratio that dictates mandatory commercial bank liquidity reserves.
Among these mechanisms, the Loan Prime Rate functions as China's definitive benchmark borrowing rate. Revisions to the LPR ripple across the real economy, altering the cost of commercial borrowing, household mortgage payments, and returns offered on consumer savings accounts. Adjustments applied to the LPR also provide the central bank with an indirect yet potent conduit to steer market valuations and capital flows tied to the Chinese Renminbi.
The Footprint of Private Banking in Mainland China
Private capital accounts for only a minor fraction of the domestic banking apparatus, which remains overwhelmingly anchored by state institutions. In total, 19 private banks operate across the country, an ecosystem that emerged after China authorized domestic lenders funded entirely by private capital to establish operations in 2014.
The most prominent players within this compact group operate primarily as digital institutions. WeBank and MYbank rank as the largest private digital lenders in the country, receiving operational and structural backing from technology conglomerates Tencent and Ant Group. Despite their scale in digital retail transactions, the private banking segment continues to represent a narrow slice within China's financial system.
Dollar Dominance Weighs on Major Foreign Exchange Pairs
Beyond Beijing's currency benchmark, the global currency arena continues to be defined by sustained US Dollar momentum. In Asian trading on Friday, AUD/USD hovered near a 10-month trough, facing persistent downside risk toward a potential breakdown beneath the 0.6800 threshold. Firming investor projections for ongoing Federal Reserve interest rate hikes, combined with dwindling expectations for US-Iran diplomatic breakthroughs, have preserved the greenback near levels unseen since April 2025. Concurrently, a dovish stance adopted by the Reserve Bank of Australia has deepened the downward trajectory for the Australian currency.
The greenback displayed similar resilience against the Japanese Yen, with USD/JPY consolidating near its highest trading levels since early September. Upward momentum showed signs of caution as spot prices neared 160.00, an area sensitive to potential intervention by Japanese authorities. Even so, the deep interest rate divergence separating the United States and Japan maintains active interest in the Yen carry trade. Possibilities of an aggressive Fed rate adjustment alongside unresolved Middle Eastern tensions have held the US Dollar near a 19-month peak, protecting the currency pair from significant declines.
Gold Staged a Mild Rebound as Crude Oil Disconnect Lingers
In precious metals, gold mounted a recovery of nearly 1 percent from the year-to-date trough registered on Thursday, pushing back above the $3,900 benchmark. This uptick materialized despite an overarching bearish fundamental environment. A temporary pause in the dollar's ascent from 19-month highs provided bullion some breathing room ahead of incoming US Producer Price Index inflation numbers. Sustained expectations of heavy Fed tightening, however, remain a substantial headwind against non-yielding metal assets.
Energy markets reflected a contrasting pattern, with Brent crude dropping roughly one-third of its value since the middle of October as traders priced in hopes of an end to the Iran conflict. In contrast, the associated expenses tied to diesel, marine freight, and agricultural fertilizers have failed to follow crude lower. These secondary overheads tend to filter gradually into consumer price metrics across an extended timeframe stretching into 2027. Consequently, even as retail motor fuel costs soften, lingering logistics and fertilizer overhead could keep underlying inflationary pressures elevated longer than expected.