













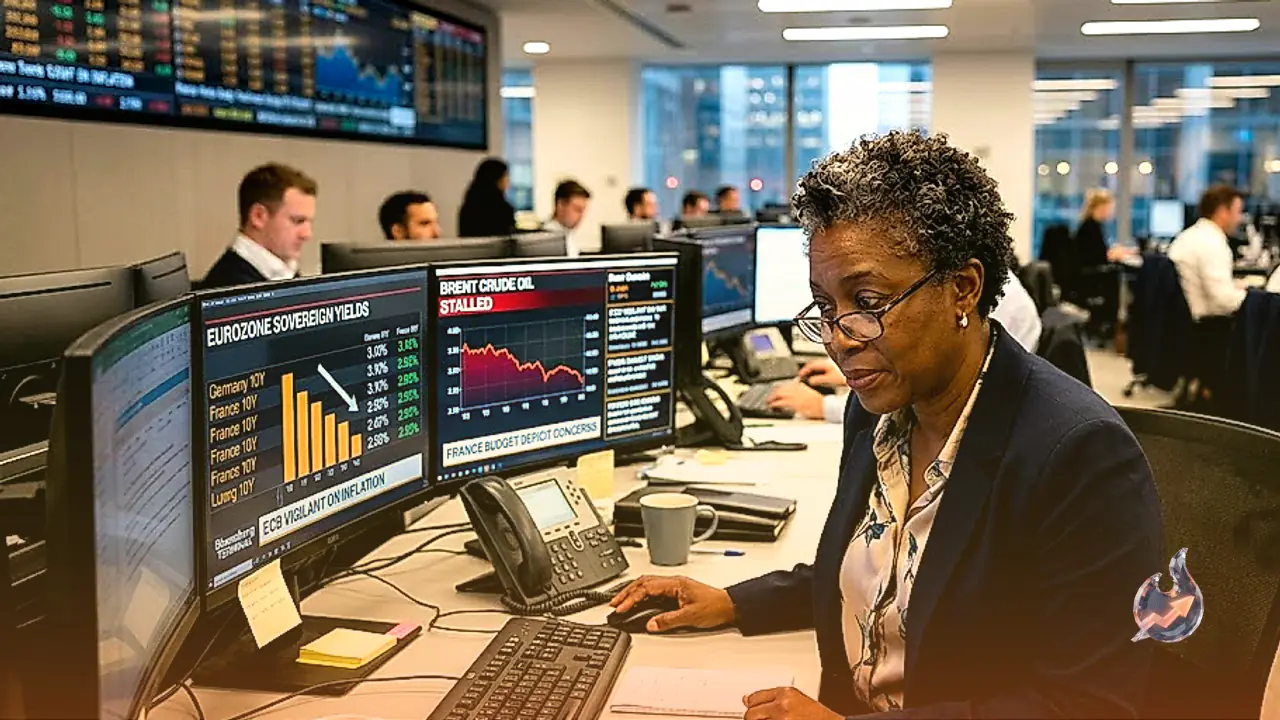

Sovereign bond yields across major international markets have retreated from multi-decade peaks after a temporary halt in crude oil price increases provided relief to debt investors following an intense market sell-off. The United States 10-year Treasury yield maintained stability around 5.25%, where steady demand for safe-haven assets helped counter mounting pressures stemming from projected Federal Reserve interest rate hikes and escalating sovereign debt concerns. Meanwhile, divergence widened across European debt markets due to distinct fiscal fundamentals. French government bonds, known as OATs, experienced a sharp yield surge exceeding 5.9% driven by anxieties over government budget deficit plans, whereas German 10-year Bund yields eased toward 3.47%. This temporary respite in energy costs has paused the aggressive upward momentum in global borrowing benchmarks, though underlying policy pressures remain active across developed economies.
Sovereign Yields Retreat in Britain and Japan
In the United Kingdom, 10-year gilt yields pulled back below 5.38% after previously reaching levels not observed since July 2007. The retracement coincided with the stabilizing price action in global crude markets, granting institutional investors a brief window of stability. Nevertheless, structural upward pressure on British yields persists due to stubborn inflation expectations fueled by high energy expenditures and unexpectedly resilient economic growth. These factors continue to validate expectations for a prolonged higher-for-longer interest rate regime. Key monetary policymakers at the Bank of England, including Governor Andrew Bailey, have indicated a willingness to implement additional rate increases should persistent energy costs continue to derail progress toward the central bank's inflation mandate.
Financial centers across Asia mirrored these Western trends, with Japan's 10-year government bond yield dropping beneath 3.1% and retreating from 30-year highs. Even so, domestic economic data suggests that Japanese sovereign yields could retain substantial underlying support. Core consumer price inflation in Tokyo registered an increase of 2.7% in September, breaking above the Bank of Japan's 2% objective for the first time in nine months and sustaining domestic borrowing cost pressures that may influence future policy deliberations.
Understanding Market Dynamics: Risk-On versus Risk-Off
In financial parlance, the paradigms of risk-on and risk-off describe investor tolerance for volatility and potential losses across specific trading periods. During a risk-on regime, market participants maintain a constructive economic outlook and actively reallocate capital into risk-sensitive asset classes seeking capital appreciation. Conversely, when a risk-off climate takes hold, defensive positioning predominates as market actors seek capital preservation over growth, rotating funds into lower-yielding securities that provide high repayment certainty.
Under typical risk-on conditions, global equity indices advance alongside broad industrial and energy commodities, while gold often lags because it does not pay a yield during periods of robust economic growth. The currencies of major commodity-exporting nations appreciate significantly as raw material trade flows expand, and speculative assets such as cryptocurrencies experience substantial inflows. During a risk-off shift, the dynamic reverses: sovereign government bonds rally as yields fall, gold attracts strong buying interest, and traditional sanctuary currencies like the Japanese Yen, Swiss Franc, and US Dollar see increased demand.
Foreign Exchange Reactions and Safe-Haven Currencies
Currencies tied to commodity trade, such as the Australian Dollar (AUD), Canadian Dollar (CAD), and New Zealand Dollar (NZD), alongside secondary foreign exchange units like the Russian Ruble (RUB) and South African Rand (ZAR), typically outperform during risk-on phases due to their reliance on raw material demand. In periods of broad retrenchment, international capital rotates toward the US Dollar (USD), Japanese Yen (JPY), and Swiss Franc (CHF). The US Dollar maintains unique status as the predominant global reserve currency, benefiting from foreign inflows into US sovereign debt because the world's largest economy is widely viewed as insulated from default risk. The Yen draws structural resilience from a large domestic investor base that rarely liquidates holdings during crises, while the Swiss Franc is bolstered by strict legal capital protections within Switzerland's banking framework.
Trading on Friday reflected these shifting dynamics. In Asian trading hours, AUD/USD rebounded toward 0.6950 as the US Dollar retreated from 17-month peaks amid profit-taking before key US employment data. The Australian Dollar also found backing in revived market pricing for a potential November policy rate increase, supported by firm yields and persistent inflationary pressures. Simultaneously, USD/JPY fluctuated without clear momentum near 158.00, retreating from weekly highs as a stronger-than-projected Tokyo CPI reading combined with Dollar profit-taking prompted currency traders to rebalance positions ahead of incoming macroeconomic releases.
Precious Metals and Digital Asset Price Action
Spot gold continued its lateral trajectory on Friday, fluctuating beneath the $4,200 threshold ahead of the European session as market participants withheld aggressive bids ahead of the US Nonfarm Payrolls figures. Expectations for the September employment report pointed to the addition of roughly 90K non-farm positions, reflecting a substantial deceleration from the 162K jobs recorded in the previous month. Any divergence from this projection has the potential to trigger volatility across the interest rate spectrum.
In the digital currency sector, Pi Network displayed short-term volatility, trading near $0.0900 on Friday after logging a loss exceeding 3% in the prior session. This pullback threatens a breach below a four-hour rising wedge pattern, raising concerns of a potential downward continuation. Pi Network continues to encounter strong technical resistance, remaining capped below the key psychological threshold of $0.1000 as the broader crypto landscape adjusts to high macro interest rates.